Blog

  • What Are the Best Mortgage Rates Currently? A Practical Comparison Guide

    What Are the Best Mortgage Rates Currently? A Practical Comparison Guide

    If you are asking what are the best mortgage rates currently, the most accurate answer is that there is no single rate available to every borrower. Your offer depends on the loan type, credit profile, down payment, property, location, and rate-lock period. The lowest advertised interest rate may also require expensive upfront payments that make it a poor deal for your situation.

    This guide does not provide verified live lender quotes, so it does not label a particular lender or percentage as today’s best. Instead, it explains how to find current benchmarks, obtain comparable offers, and identify the mortgage with the strongest overall value for you.

    What Does the Best Mortgage Rate Mean?

    A mortgage rate is the interest charged on a home loan, expressed as an annual percentage of the outstanding principal. For a fixed-rate mortgage, that rate generally stays unchanged throughout the loan term. With an adjustable-rate mortgage, it can change according to the loan’s rules after any initial fixed period.

    The best mortgage rate is not necessarily the lowest number on an advertisement. A useful definition is the lowest competitively available rate for your circumstances, paired with reasonable fees, suitable loan terms, and costs that fit how long you expect to keep the mortgage.

    Interest rate versus APR
    What Are the Best Mortgage Rates Currently? A Practical Comparison Guide
    What Are the Best Mortgage Rates Currently? A Practical Comparison Guide

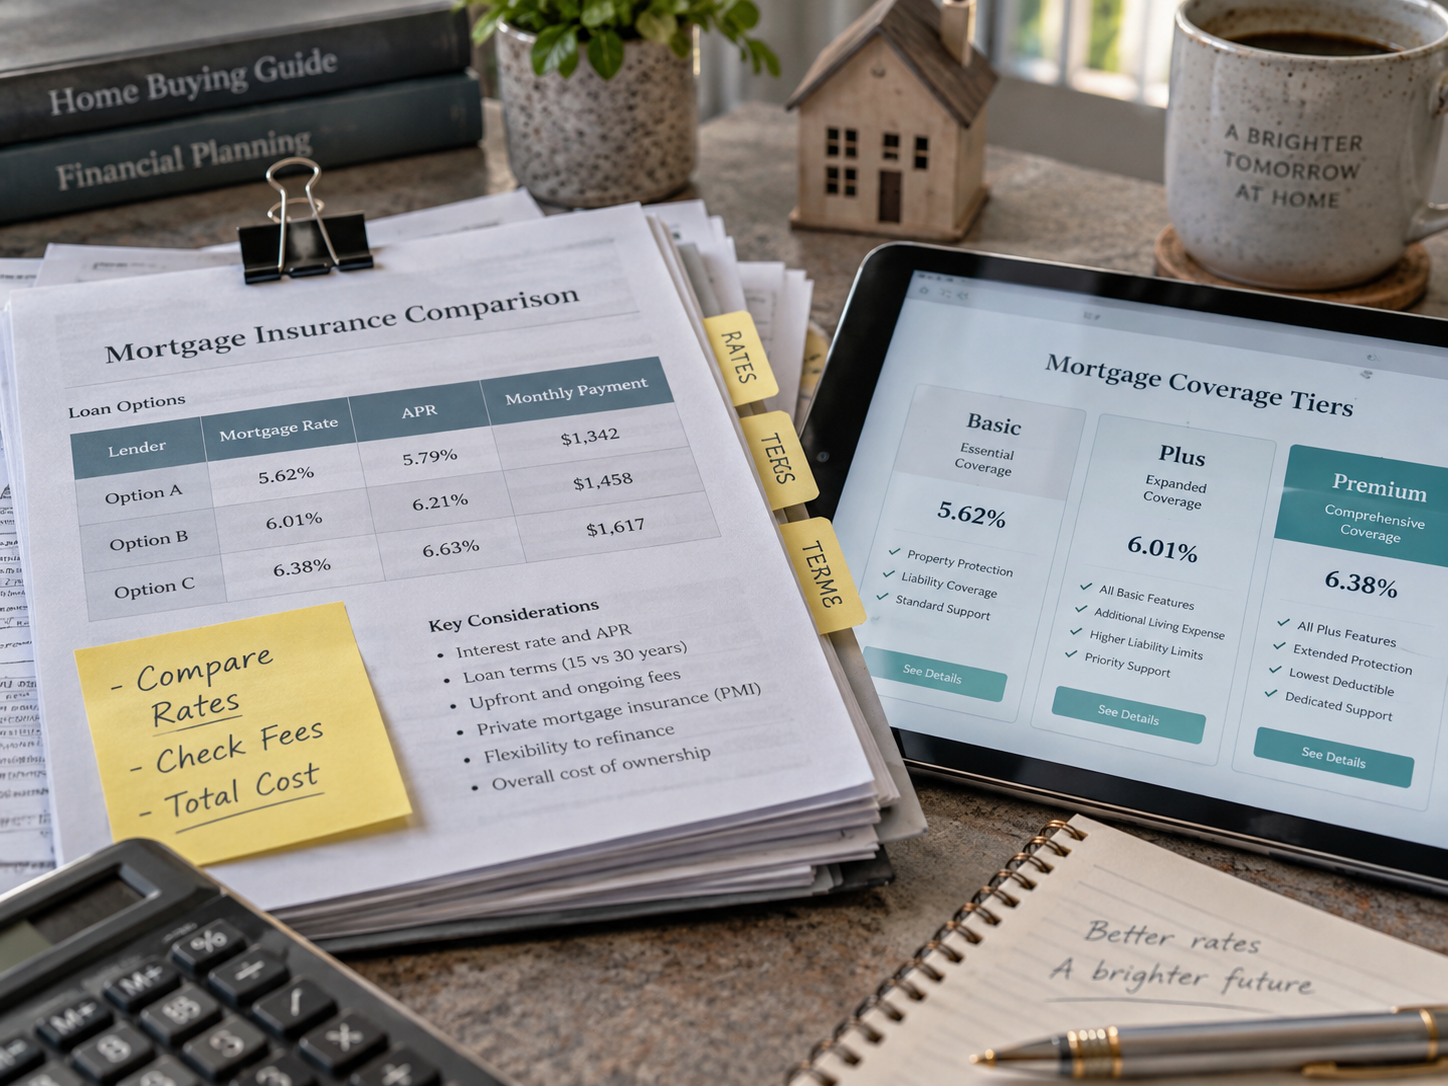
    The interest rate helps determine your monthly principal-and-interest payment. The annual percentage rate, or APR, incorporates the interest rate and certain additional financing costs, making it a broader cost measure.

    APR is useful when comparing similar loans, but it is not a complete decision tool. It does not represent every homeownership expense, and comparisons become less straightforward when loan terms or adjustable-rate structures differ. It may also be less relevant to your actual costs if you sell or refinance well before the loan ends.

    Where to Find Reliable Current Mortgage Information

    Start with a market benchmark, then obtain personalized quotes. National averages can show the general direction of borrowing costs, but they are not promises that a lender will offer you the same terms.

    • Freddie Mac’s Primary Mortgage Market Survey: Published at Freddie Mac PMMS, this is a widely followed source for weekly mortgage-rate benchmarks. Check the release date and methodology before using its figures.
    • Consumer Financial Protection Bureau: The CFPB’s Owning a Home resources explain loan options, closing disclosures, and how to compare Loan Estimates.
    • Personalized lender offers: Banks, credit unions, mortgage companies, and brokers can provide pricing based on your actual application and property details.

    Always distinguish the publication date from the day you are shopping. Mortgage pricing can change between a weekly benchmark’s release and your application, and sometimes within a single business day.

    This guide focuses on U.S. mortgage shopping. Its comparison method is to match loan characteristics, compare offers obtained close together, separate lender charges from other closing expenses, and evaluate costs over your expected ownership period.

    Why Your Rate May Differ From an Advertised Rate

    Credit profile and existing debt

    Lenders consider credit history alongside income, assets, and debt obligations. A stronger credit profile may help you qualify for better pricing, but the credit score shown in a consumer app may differ from the score used for mortgage underwriting.

    Before applying, review your credit reports and dispute inaccuracies. Avoid taking out unnecessary credit or increasing card balances during underwriting. Paying down revolving debt may help your overall application, but the effect on your score and mortgage pricing is not guaranteed.

    Down payment and loan amount

    Your down payment affects the loan-to-value ratio, which compares the mortgage balance with the property’s value. It can influence pricing and whether mortgage insurance is required.

    A larger down payment can reduce borrowing costs, but emptying your savings creates a separate risk. Preserve enough cash for closing, moving, repairs, and an emergency reserve. Money needed soon is generally better kept accessible than exposed to investment-market fluctuations.

    Property and occupancy

    Pricing may differ for a primary residence, second home, or investment property. Condominiums, multi-unit buildings, manufactured homes, and other property types may also have different underwriting requirements.

    Loan size matters too. Conforming and jumbo mortgages have different eligibility frameworks, and neither category is automatically cheaper. Compare the actual offers available for your property and borrowing amount.

    Timing and rate locks

    A quote is not necessarily a locked rate. Ask whether the offer is locked, when the lock expires, and what happens if closing is delayed. A longer lock may cost more, while an extension may involve additional fees.

    Some lenders offer a float-down feature that may allow a lower rate if market pricing improves. Availability, qualifying conditions, and charges vary, so obtain the terms in writing.

    Compare Mortgage Types Before Comparing Percentages

    Fixed-rate mortgages

    A fixed-rate mortgage offers predictable principal-and-interest payments. A longer term generally lowers the required monthly payment relative to a shorter term for the same balance, but it usually increases total interest paid if the loan is held to maturity.

    A shorter term often carries a lower rate, although that is not guaranteed. Its higher monthly payment can strain your budget or reduce room for retirement contributions and emergency savings.

    Adjustable-rate mortgages

    An adjustable-rate mortgage, or ARM, may offer an attractive initial rate. Its main disadvantage is uncertainty after the initial fixed period. Review the index, margin, adjustment frequency, and caps that govern future changes.

    Do not assume you will be able to refinance before the first adjustment. Falling home values, employment changes, or tighter lending standards could make refinancing difficult. Test whether your budget could handle payments after permitted rate increases.

    Government-backed mortgages

    FHA, VA, and USDA loans have distinct eligibility rules and cost structures. FHA loans include mortgage insurance. VA loans generally do not require monthly mortgage insurance, but a funding fee may apply unless the borrower qualifies for an exemption. USDA loans have location and income requirements, along with applicable program fees.

    These programs can make homeownership more accessible for eligible borrowers. However, a lower quoted interest rate does not automatically mean a lower total cost once insurance and program charges are included.

    How to Compare Current Offers Step by Step

    1. Set a realistic housing budget

    Estimate the full monthly housing expense, not just the mortgage payment. Include property taxes, homeowners insurance, mortgage insurance when required, association dues, and a maintenance allowance.

    A lender’s maximum approval amount is not a spending recommendation. Use a budgeting calculator to check whether the payment leaves room for savings, existing debts, and irregular expenses. Property taxes and insurance premiums can rise even with a fixed-rate mortgage.

    2. Choose a common comparison scenario

    Give each lender the same purchase price, down payment, loan amount, property type, occupancy status, and expected closing date. Request the same loan type, term, and lock period.

    For a clean starting point, ask for a quote with no discount points and have any lender credits shown separately. You can then request alternatives with points or credits to see the trade-off between upfront expense and ongoing payments.

    3. Shop across several channels

    Consider a bank, a credit union if you qualify for membership, and an independent mortgage lender or broker. Your existing bank may offer relationship pricing, but it should still compete on total cost.

    Ask a broker which lenders they can access and how compensation works. A broker can simplify shopping, but may not represent every lender. Group applications within a short shopping period; credit-scoring models commonly treat qualifying mortgage inquiries within a shopping window together, though the window varies by model.

    4. Request and review Loan Estimates

    For most covered U.S. mortgage applications, lenders must provide a Loan Estimate within three business days after receiving the required application information. This standardized form is more useful than a headline rate alone.

    Compare these items side by side:

    • Loan amount, term, type, and interest rate.
    • Monthly principal and interest, plus mortgage insurance.
    • Discount points, origination charges, and lender credits.
    • Required services and whether you can shop for their providers.
    • Estimated cash to close and rate-lock status.
    • Any prepayment penalty or balloon-payment feature.

    Separate lender-controlled charges from taxes, insurance prepayments, and escrow funding. A lower estimate for taxes or insurance does not necessarily make one lender cheaper; those figures may simply reflect different assumptions.

    5. Compare costs over your expected timeline

    Estimate how long you are likely to keep the loan. A mortgage that wins over its full term may lose over a shorter period because of upfront fees.

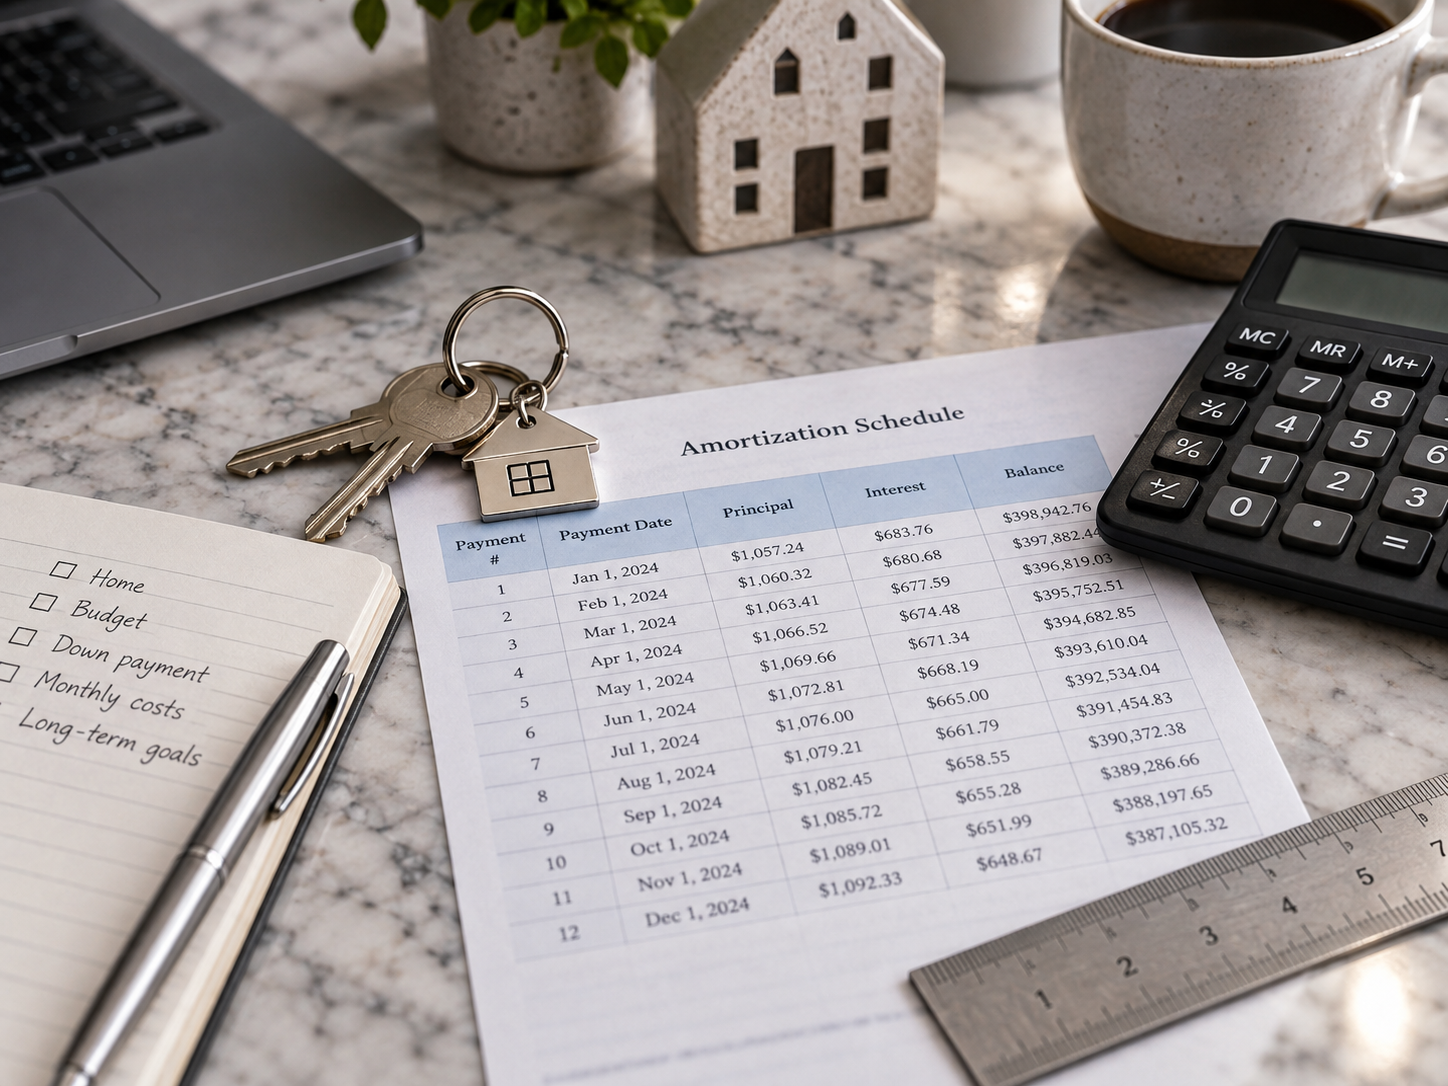
    Use an amortization calculator to compare payments, interest costs, and remaining balances at your expected sale or refinance date. If comparing different loan terms, account for principal repayment as well as monthly cash flow.

    Discount Points and Lender Credits: Pros and Cons

    Discount points are upfront charges paid to obtain a lower interest rate. One point equals one percent of the loan amount, but the rate reduction it buys varies by lender and market conditions.

    Potential benefit: Paying points can lower monthly payments and may reduce overall costs if you keep the mortgage long enough. Potential drawback: You spend more at closing and may sell or refinance before recovering that expense.

    A simple break-even calculation divides the additional upfront cost by the monthly payment savings. This is only a screening tool: it does not fully account for differences in remaining balances, the time value of money, or tax treatment.

    Lender credits generally reverse the trade-off. Accepting a higher rate may reduce upfront closing costs, which can preserve cash. The disadvantage is a higher ongoing borrowing cost. Compare both options rather than assuming either is inherently better.

    Limitations and Common Comparison Traps

    Advertised rates often assume a particular credit profile, loan size, down payment, and point payment. Offers may also depend on geographic availability or an existing banking relationship. Read the assumptions before treating an advertisement as a realistic target.

    Be cautious with temporary buydowns: an initially reduced payment does not necessarily mean the mortgage’s underlying interest rate is lower. Ask for the note rate and the payment required after the subsidy ends.

    Closing reliability and service matter alongside price. Ask about processing timelines, communication, and experience with your loan type. Reviews can reveal recurring issues but are not controlled evidence that a lender will perform well for your transaction.

    Finally, do not assume a future refinance will rescue an unaffordable purchase. Refinancing requires eligibility and usually involves costs. Choose a mortgage you can reasonably support under its existing terms.

    Concise Mortgage Rate Q&A

    What are the best mortgage rates currently?

    The best available rate for you requires current, personalized quotes. Check a dated benchmark such as Freddie Mac’s PMMS, then compare same-day offers with matching terms, fees, and lock periods.

    Is the lowest APR always the best mortgage?

    No. APR helps compare similar loans, but your holding period, upfront cash needs, payment risk, and loan structure also matter.

    Can I negotiate a mortgage offer?

    You can ask a lender to improve its rate, fees, or credits using a competing written offer. Improvements are not guaranteed; request an updated written disclosure when terms change.

    Should I wait for rates to fall?

    No one can reliably guarantee near-term rate movements. Base the decision on affordability, reserves, expected time in the home, and suitable current offers rather than a forecast alone.

    The Bottom Line

    Finding the best mortgage means comparing more than a percentage. Use current benchmarks for context, collect matching Loan Estimates, and weigh upfront costs against payments and your expected timeline. The strongest offer is one that remains affordable without relying on future refinancing or optimistic assumptions.

    Informational disclaimer: This article provides general educational information, not personalized financial, tax, or legal advice. Mortgage rates, eligibility requirements, and fees change. Verify current terms directly with lenders and consider qualified professional guidance before committing.

  • Canada Fixed vs. Variable Mortgage Rate Comparison: How to Choose

    Choosing between a fixed and variable mortgage rate is one of the most consequential decisions in Canadian personal finance. A Canada fixed variable mortgage rate comparison should look beyond the headline rate and consider payment stability, interest-rate risk, mortgage terms, penalties, refinancing plans, and your household budget.

    This guide explains how fixed and variable mortgages work in Canada, how to compare offers on an apples-to-apples basis, and which questions to ask before signing. It is intended for general information, not individualized mortgage, tax, or investment advice.

    What Is a Fixed or Variable Mortgage Rate?

    A fixed mortgage rate stays the same during the mortgage term. If your term is five years, the interest rate generally remains unchanged for those five years, although your payment structure depends on the mortgage contract. Fixed mortgages make budgeting easier because the interest rate is insulated from changes in the lender’s prime rate.

    A variable mortgage rate usually moves in relation to the lender’s prime rate. When the Bank of Canada changes its policy rate, lenders may adjust prime, which can cause a variable mortgage rate and possibly the borrower’s payment to change. The exact effect depends on whether the mortgage has a fixed payment, an adjustable payment, or another structure.

    These products are different from the mortgage term and amortization period. The term is the length of the current contract, while the amortization period is the estimated time required to repay the mortgage in full if payments and rates remain consistent. A mortgage can have a five-year fixed term with a 25-year amortization, or a five-year variable term with the same amortization.

    How Canadian Mortgage Rates Are Usually Set

    Variable mortgage rates are commonly expressed as the lender’s prime rate plus or minus a spread. For example, an offer might be described as “prime minus a discount.” The discount is not automatically permanent for the entire life of the mortgage; it generally applies according to the contract and term.

    Fixed mortgage rates are influenced by lenders’ funding costs and bond-market conditions. They do not necessarily move in lockstep with the Bank of Canada’s overnight policy rate. This is why a Bank of Canada announcement may affect variable mortgage pricing more directly than fixed pricing, while fixed rates can change in anticipation of future economic conditions.

    For an authoritative explanation of monetary policy and the overnight rate, consult the Bank of Canada. For consumer-focused information about mortgages, prepayment rights, disclosure, and renewal considerations, consult the Financial Consumer Agency of Canada (FCAC). These sources are more reliable for general rules than advertisements or informal rate lists.

    Fixed vs. Variable Mortgage Comparison

    Factor Fixed rate Variable rate
    Rate movement Normally stays constant during the term Usually changes with the lender’s prime rate
    Payment predictability Generally easier to budget May change, depending on the payment structure
    Interest-rate risk Lower during the current term Borrower carries more risk if rates rise
    Potential benefit if rates fall Usually limited until renewal or conversion May benefit as the lender’s prime rate declines
    Prepayment penalty May be based on a higher of a formula or interest-rate differential Often based on a specified number of months’ interest, but the contract controls

    The table provides a framework rather than a guarantee. Lenders offer different products, and terms can vary significantly. A variable mortgage with a fixed payment is not the same as one where the payment adjusts whenever the rate changes.

    Payment Types and the Trigger Rate

    Adjustable-payment variable mortgages

    With an adjustable-payment variable mortgage, the payment typically changes when the interest rate changes. A rate increase can raise the required payment, while a rate decrease can lower it. This structure makes the effect of rate changes visible in the household budget.

    Fixed-payment variable mortgages

    Some variable mortgages keep the scheduled payment unchanged for a period even as the interest rate moves. If the rate rises, a larger share of the payment can go toward interest and less toward principal. In certain contracts, a borrower may reach a trigger rate, meaning the payment no longer covers all of the interest accruing for the period.

    When a trigger rate is reached, the lender may require a higher payment, a lump-sum principal payment, a conversion to a fixed product, or another remedy described in the mortgage agreement. The details differ by lender. Ask for the trigger-rate policy in writing and understand how the lender will notify you.

    Pros and Cons of Fixed Mortgages

    Potential advantages

    • Predictable payments: A stable rate can make it easier to plan for childcare, utilities, insurance, savings, and debt repayment.
    • Protection from rising rates: The contracted rate normally remains unchanged during the term, subject to the mortgage agreement.
    • Simple comparison: Borrowers who prioritize certainty may find fixed offers easier to evaluate.

    Potential disadvantages

    • Higher break costs: Ending a closed fixed mortgage early can result in a substantial prepayment charge, often based on the lender’s interest-rate differential formula or another contractual calculation.
    • Less immediate benefit from falling rates: A fixed borrower generally does not receive a lower rate until switching, refinancing, or renewing.
    • Possible restrictions: Annual prepayment privileges, portability, conversion options, and penalty rules vary by lender.

    Pros and Cons of Variable Mortgages

    Potential advantages

    • Participation in falling rates: If the lender’s prime rate decreases, the mortgage rate may decline according to the contract.
    • Potentially lower break costs: Some variable closed mortgages use a simpler penalty formula than fixed mortgages, though this is not universal.
    • Conversion flexibility: Certain products permit conversion to a fixed mortgage, but conversion rates and conditions must be checked carefully.

    Potential disadvantages

    • Payment uncertainty: A higher prime rate may increase the payment or reduce the amount applied to principal.
    • Budget pressure: A household with limited monthly flexibility may have difficulty absorbing several rate increases.
    • Contract complexity: Trigger rates, payment changes, conversion rules, and the lender’s prime-rate definition require close review.

    Practical Steps for a Canada Fixed Variable Mortgage Rate Comparison

    1. Establish an affordable payment range

    Begin with the payment your household can comfortably manage, not the maximum amount a lender may approve. Include property tax, home insurance, utilities, condo fees, maintenance, commuting costs, and existing debt payments. A budgeting calculator can help separate essential costs from optional spending.

    Test the budget under a higher-rate scenario. The purpose is not to predict rates but to determine whether your finances could withstand an increase. If a modest payment change would require missed bills or new credit-card debt, payment certainty may deserve more weight.

    2. Compare the same term and amortization

    Do not compare a three-year fixed mortgage with a five-year variable mortgage as though the rates were directly equivalent. Request quotes using the same term, amortization, payment frequency, mortgage amount, and down-payment assumptions.

    Also identify whether the rate is insured or uninsured. In Canada, mortgage insurance requirements and pricing can affect the overall cost. The lender should explain whether insurance premiums are included in the mortgage balance or paid separately.

    3. Record the complete cost of each offer

    Ask for the annual interest rate, term, amortization, regular payment, total interest estimate for the term, lender fees, appraisal costs, legal costs, discharge fees, and prepayment privileges. A lower advertised rate may not be the least expensive option if it comes with restrictive conditions or high penalties.

    Review the federally required disclosure documents and the lender’s mortgage agreement. The FCAC provides educational material about mortgage costs and borrower rights. For a complex transaction, an independent mortgage professional or lawyer can help interpret the contract.

    4. Examine prepayment and refinancing rules

    Check the annual lump-sum privilege, payment-increase privilege, portability, assumability, and any restrictions on accelerated payments. If you may sell your home, move provinces, separate from a partner, or refinance for renovations, penalty rules could be more important than a small difference in the starting rate.

    Ask the lender to demonstrate a sample penalty calculation. Do not rely on a general statement that the penalty is “only three months’ interest.” That may apply to one situation but not another, especially for a fixed mortgage.

    5. Consider your likely time horizon

    If you expect to move before the term ends, a portable mortgage may be useful, but portability has conditions and may not eliminate all costs. If you plan to stay for the entire term and value stable payments, a fixed mortgage may fit your priorities. If your finances can tolerate changes and you expect to hold the mortgage through different rate conditions, a variable product may be worth evaluating.

    6. Compare lenders, not just rates

    Compare banks, credit unions, monoline lenders, and broker-channel products where appropriate. Review customer service, renewal practices, payment-change notices, online account access, and the lender’s policy for converting or discharging the mortgage. A rate quote is only one part of a banking product comparison.

    Mortgage Qualification and the Stress Test

    Many federally regulated borrowers must qualify using a prescribed minimum qualifying rate rather than simply the contract rate. The rule and its application can change, and eligibility may differ for uninsured mortgages, refinances, transfers, and other situations. The Office of the Superintendent of Financial Institutions (OSFI) publishes information about federal mortgage underwriting expectations, while lenders can explain how the rules apply to a particular application.

    Passing a qualification test does not mean a mortgage is affordable for every household. Approval models may not fully reflect irregular income, future childcare expenses, health-related costs, or a planned career change. Keep an emergency reserve and avoid using all available cash for the down payment if doing so leaves no room for repairs or income disruption.

    How Mortgage Choice Fits Into a Broader Financial Plan

    A mortgage decision should be considered alongside other borrowing and saving choices. High-interest credit-card balances may cost more than the expected benefit of making a small additional mortgage payment. A personal loan used for debt consolidation should be compared using the total repayment cost, not only the monthly payment.

    Keep cash needs in mind as well. A high-yield savings account may provide a suitable place for an emergency fund, although rates are variable and account conditions differ. Checking-account fees, credit-card rewards, car insurance, home insurance, retirement accounts, and registered plans such as TFSAs or RRSPs can all affect the amount available for mortgage payments and prepayments.

    Before applying, review your credit reports and correct errors. Credit-score improvement usually comes from making payments on time, keeping balances manageable, limiting unnecessary applications, and maintaining older accounts where appropriate. Do not close useful credit accounts or take on new debt solely to pursue a mortgage offer without considering the wider effect.

    Limitations of Mortgage Rate Comparisons

    Published rates are not personalized approvals. The rate offered may depend on credit history, income verification, property type, loan-to-value ratio, location, mortgage insurance, transaction size, and whether the mortgage is a purchase, renewal, transfer, or refinance.

    Online comparison tables can also become outdated. Rates may change during the day, and a displayed rate may require specific conditions. Confirm the quote directly with the lender and ask when the rate hold expires. A comparison should use the date, source, mortgage type, and conditions for every quoted offer.

    No comparison can predict future Bank of Canada decisions or bond-market movements. Instead of trying to forecast rates with certainty, assess how each mortgage behaves under several plausible scenarios and choose a structure that matches your risk capacity.

    Concise Q&A

    Is a fixed mortgage always safer?

    It usually provides more payment certainty during the term, but it may carry higher penalties if you break the mortgage. “Safer” depends on both rate risk and the likelihood that you will need to exit early.

    Can a variable mortgage payment stay the same?

    Some contracts keep the payment fixed temporarily while the interest portion changes. If rates rise enough to reach the trigger rate, the lender may require an adjustment. Read the specific contract.

    Should I choose the lowest advertised rate?

    Not automatically. Compare the full cost, penalties, prepayment privileges, portability, lender fees, and payment structure.

    Can I switch from variable to fixed?

    Some variable mortgages permit conversion, but the available fixed rate and conditions may not be as attractive as a new fixed offer. Verify the conversion clause before relying on it.

    Where can I verify Canadian mortgage information?

    Use the Bank of Canada for monetary-policy information, FCAC for consumer mortgage guidance, and OSFI for federal supervisory information. Your lender’s contract remains the controlling source for product-specific terms.

    Bottom Line

    A sound Canada fixed variable mortgage rate comparison balances the initial rate against payment stability, interest-rate exposure, prepayment penalties, flexibility, and your expected time in the home. Fixed mortgages can suit borrowers who prioritize certainty, while variable mortgages may suit borrowers who can absorb payment changes and accept the possibility of higher costs if rates rise. Compare equivalent offers, stress-test your budget, read the penalty and trigger-rate clauses, and obtain independent advice when the decision is difficult.

    Safety and informational disclaimer: Mortgage rates, qualification rules, lender policies, and legal requirements can change. This article is general educational information and is not financial, legal, tax, or mortgage advice. Confirm current details with the lender, FCAC, Bank of Canada, OSFI, and qualified professionals before making a borrowing decision.

  • How Has the Best Mortgage Rates? A Practical Guide to Comparing Lenders

    How Has the Best Mortgage Rates? A Practical Guide to Comparing Lenders

    People often search for “how has the best mortgage rates,” but the more useful question is: which lender can offer the best mortgage rate for my specific financial profile and loan? Mortgage pricing is personalized. The rate shown in an advertisement may depend on the borrower’s credit history, down payment, loan term, property type, location, loan amount, occupancy, and whether the borrower pays discount points.

    There is no single lender that always has the lowest rate for every borrower. A reliable comparison looks at the annual percentage rate (APR), fees, loan features, and estimated total cost—not just the headline interest rate. This guide explains how to compare mortgage offers, where to find current market information, and how to avoid common mistakes.

    What does “best mortgage rate” mean?

    A mortgage interest rate is the percentage charged by a lender for borrowing money to buy or refinance a home. The rate affects the monthly principal-and-interest payment and the amount of interest paid over the life of the loan.

    The APR is a broader measure. It generally includes the interest rate plus certain lender fees and other loan costs, expressed as an annualized percentage. APR can make it easier to compare offers, although it does not capture every possible ownership cost, such as property taxes, homeowners insurance, maintenance, or future refinancing expenses.

    A best-rate comparison should therefore consider:

    • The note interest rate and APR
    • Loan term, such as 15, 20, or 30 years
    • Fixed-rate or adjustable-rate structure
    • Origination charges, underwriting fees, and other closing costs
    • Discount points and lender credits
    • Mortgage insurance requirements
    • Prepayment terms and loan flexibility
    • Whether the payment estimate includes taxes, insurance, and association dues

    Who may have the best mortgage rates?

    What does “best mortgage rate” mean?
    What does “best mortgage rate” mean?

    The lender with the best offer depends on the borrower and the type of mortgage. Banks, credit unions, online lenders, mortgage brokers, and specialized loan companies may all provide competitive options at different times.

    Banks

    Banks may offer conventional, jumbo, government-backed, and refinancing products. Existing customers may receive relationship discounts, although the discount should be compared with the bank’s total rate and fees. A bank may also have stricter underwriting standards or a narrower product range.

    Credit unions

    Credit unions are member-owned financial institutions. They may offer competitive rates or lower fees, but membership requirements, geographic limits, or product availability can vary. Compare the complete Loan Estimate rather than assuming that a credit union is automatically cheaper.

    Online mortgage lenders

    Online lenders may provide a streamlined application process and transparent digital tools. Some have lower operating costs, but convenience does not guarantee a lower total cost. Check customer-service availability, closing timelines, lender fees, and the process for resolving documentation issues.

    Mortgage brokers

    A broker can request offers from multiple lenders and may help borrowers find products that fit unusual circumstances. Brokers are paid through lender-paid or borrower-paid compensation, so ask how the compensation works and whether it affects the pricing or fees in your offer.

    How to compare mortgage rates accurately

    1. Review your financial position

    Before requesting quotes, gather information about income, employment, assets, debts, credit history, and the expected purchase price. Lenders commonly assess debt-to-income ratio, loan-to-value ratio, credit profile, and the source of the down payment.

    Improving your credit score may help you qualify for more favorable pricing, but the effect varies by lender and loan program. Check your credit reports for errors through the official process available at AnnualCreditReport.com. Avoid opening unnecessary credit accounts or taking on new debt shortly before applying.

    2. Decide which loan types to compare

    Conventional mortgages are common for borrowers who meet the lender’s credit and down-payment requirements. Federal Housing Administration loans may have different qualification rules and mortgage insurance costs. Department of Veterans Affairs loans can provide eligible veterans, service members, and surviving spouses with distinct terms. The U.S. Department of Agriculture also supports certain rural housing programs.

    Compare fixed-rate and adjustable-rate mortgages carefully. A fixed-rate mortgage keeps the interest rate unchanged for the loan term, making payments more predictable. An adjustable-rate mortgage may begin with a lower rate, but the rate can change after the initial period according to the contract’s index, margin, adjustment schedule, and caps.

    3. Request multiple written estimates

    Ask several lenders for pricing based on the same assumptions: purchase price, down payment, loan amount, occupancy, property type, loan term, and lock period. Changing one assumption can make quotes appear more or less attractive without reflecting a genuine pricing difference.

    Once you provide the required application information, a lender generally provides a standardized Loan Estimate. The Consumer Financial Protection Bureau (CFPB) explains how to use this document to compare interest rate, APR, projected payments, closing costs, cash to close, and other terms. Requesting Loan Estimates from multiple lenders can help create an apples-to-apples comparison.

    4. Compare APR and total cash required

    A lower advertised rate may require discount points. One point generally represents a percentage of the loan amount, but the cost and effect on the rate vary by lender and market conditions. Ask how long it would take for the monthly savings to recover the upfront cost.

    For example, if paying points reduces the payment but you expect to move or refinance before the break-even period, the lower rate may not be the cheaper option. Conversely, paying points could make sense for someone who expects to keep the mortgage for many years and has sufficient cash reserves after closing.

    5. Check the rate-lock policy

    A rate lock holds an interest rate for a specified period, subject to the lender’s terms and the loan closing on time. Ask whether the lock is free, how long it lasts, what happens if closing is delayed, and whether the lender offers a float-down option if rates fall. A quote that is not locked can change before closing.

    6. Evaluate the lender’s execution and service

    Rate is important, but a delayed or poorly managed closing can create financial and practical problems. Ask who will handle the application, how documents are submitted, what the expected timeline is, and how quickly questions are answered. Review regulatory and licensing information through the Nationwide Multistate Licensing System and Registry where applicable, and check complaint information through official consumer-protection resources.

    Reliable sources for mortgage-rate research

    The CFPB provides explanations of mortgage disclosures, Loan Estimates, closing disclosures, APR, points, and common lending practices. Its guidance is useful for understanding what lenders are required to disclose and how borrowers can compare offers.

    Freddie Mac’s Primary Mortgage Market Survey tracks selected average mortgage rates and points based on its published methodology. It can provide market context, but it is not a personalized quote and may not reflect your credit profile, loan type, location, or exact timing.

    For government-backed loans, consult official resources from the U.S. Department of Veterans Affairs, the Federal Housing Administration within the U.S. Department of Housing and Urban Development, and the U.S. Department of Agriculture. These sources explain eligibility and program rules more reliably than generalized advertisements.

    A practical comparison methodology is to collect at least three written offers, hold the loan assumptions constant, compare rate and APR, separate recurring from one-time costs, calculate the break-even point for points or lender credits, and confirm the rate-lock terms. This method is more dependable than ranking lenders by a single advertised rate.

    How credit, down payment, and loan details affect rates

    Credit history can affect both eligibility and pricing. A stronger credit profile may help a borrower qualify for more favorable terms, while missed payments, high balances, or limited credit history can make borrowing more expensive. Credit improvement should focus on paying bills on time, reducing revolving balances where practical, checking reports for inaccuracies, and avoiding applications that are not necessary.

    A larger down payment can reduce the loan-to-value ratio and may reduce the need for private mortgage insurance on some conventional loans. However, using every available dollar for the down payment can leave too little for closing costs, repairs, emergencies, and moving expenses. A lower down payment may preserve cash but can increase the loan balance and insurance cost.

    Loan term also matters. A shorter term may have a lower interest rate and faster principal repayment, but the monthly payment is usually higher. A longer term may offer a more manageable payment but can result in more interest over time. Compare the payment with your budget rather than choosing solely based on the lowest rate.

    Neutral pros and cons of shopping for the lowest rate

    Potential advantages

    • A lower rate can reduce the scheduled principal-and-interest payment.
    • Comparing offers may reveal lower fees or more suitable loan features.
    • Multiple quotes can improve negotiating use with a lender.
    • Reviewing Loan Estimates can expose costs that advertisements do not emphasize.

    Potential drawbacks and limitations

    • The lowest rate may require points, a larger down payment, or stricter qualifications.
    • A low rate with high fees may cost more than a slightly higher rate with lower upfront costs.
    • Rates change, so an online table may not match a quote received later.
    • Average market surveys are not personalized offers.
    • Comparing too many lenders can create administrative complexity, even though mortgage-shopping inquiries may receive special treatment under some credit-scoring models.
    • Tax, insurance, maintenance, and possible homeowners association expenses can be larger than the difference between two mortgage offers.

    Mortgage comparison alongside other financial products

    Mortgage decisions affect the rest of a household budget. Before committing to a payment, review emergency savings and recurring obligations. A high-yield savings account may be appropriate for accessible reserves, while a checking account comparison can reveal monthly maintenance, overdraft, and transaction fees. These products serve different purposes, so a high savings rate does not compensate for an unaffordable mortgage.

    Also consider existing credit-card balances, personal loans, and debt-consolidation options. Consolidating unsecured debt into a mortgage can reduce the interest rate in some cases, but it may convert unsecured debt into debt secured by your home and can increase the repayment period. Compare the full cost and risks before proceeding.

    Do not neglect retirement accounts and IRAs when planning a down payment. Withdrawing retirement money may create taxes, penalties, lost investment growth, or reduced long-term financial security. Budgeting calculators can help test payment scenarios, and insurance quotes for homeowners, vehicles, and other coverage should be included in the household plan.

    Concise mortgage-rate Q&A

    Is the lowest mortgage rate always the best deal?

    No. A lower rate may come with points, higher fees, or conditions that do not suit your timeline. Compare APR, cash to close, projected payments, and the likely time you will keep the loan.

    How many mortgage lenders should I compare?

    There is no required number, but obtaining several comparable written offers can provide useful context. Include different lender types, such as a bank, credit union, online lender, or broker, when practical.

    Does checking mortgage rates hurt my credit?

    A lender may need permission to review your credit for a formal quote or application. Mortgage-related inquiries made within a qualifying shopping period may be treated as one inquiry by some scoring models, but policies and scoring models differ. Ask lenders how they will access your credit.

    Should I choose a fixed or adjustable mortgage?

    A fixed-rate loan generally provides more payment certainty. An adjustable-rate loan may be useful for some borrowers who understand the adjustment rules and expect to move or refinance, but future payments can rise. Read the complete terms before choosing.

    Can I negotiate a mortgage rate?

    You can ask whether the lender can improve the rate, reduce fees, match a competing offer, or provide different points and credit options. Any revised offer should be provided in writing and compared using the same assumptions.

    Final checklist

    • Check your credit reports and estimate your affordable payment.
    • Compare suitable loan programs, not just advertised rates.
    • Request written Loan Estimates using identical assumptions.
    • Review APR, points, lender credits, fees, insurance, and cash to close.
    • Calculate the break-even period for paying points.
    • Confirm rate-lock duration, extension costs, and float-down rules.
    • Include taxes, homeowners insurance, maintenance, and other debts in your budget.
    • Keep adequate emergency savings after closing.

    Informational disclaimer: Mortgage rates, fees, eligibility rules, and tax treatment change over time and vary by borrower and location. This article is for general education, not personalized financial, legal, tax, or lending advice. Review official disclosures and consider speaking with a qualified mortgage professional and an independent financial adviser before making a borrowing decision.

  • Best Checking Account Rates 2025: How to Compare APY, Fees, and Features

    Best Checking Account Rates 2025: How to Compare APY, Fees, and Features

    Finding the best checking account rates 2025 shoppers can access requires more than choosing the account with the largest advertised APY. A checking account may offer interest, cash rewards, or a competitive sign-up benefit, but fees, balance requirements, direct-deposit rules, overdraft policies, and access to cash can have a greater effect on your finances.

    This guide explains how to compare interest-bearing checking accounts and other everyday banking products. It does not rank a specific bank or guarantee that any account will be the best choice for every customer. Rates and terms can change, so confirm current information in the institution’s official account agreement and fee schedule before applying.

    What are checking account rates?

    A checking account rate is the return a bank or credit union pays on eligible money held in the account. It is usually shown as an annual percentage yield, or APY, which reflects the stated interest rate and the effect of compounding under the account’s terms. Some checking accounts pay no interest, while interest-bearing, rewards, and high-yield checking accounts may pay more when customers meet specific requirements.

    Common requirements include receiving qualifying direct deposits, making a minimum number of monthly debit-card purchases, enrolling in electronic statements, or keeping the balance below or above a specified threshold. An advertised APY may apply only to a limited balance tier. Money above that tier may earn a lower rate or no interest at all.

    Checking accounts are designed for frequent transactions rather than maximum savings growth. If you are building an emergency fund or saving for a near-term goal, compare the account with high-yield savings accounts as well. Savings accounts may offer competitive yields but can have different withdrawal rules, transfer procedures, or access arrangements.

    How to identify the best checking account rates in 2025

    What are checking account rates?
    What are checking account rates?

    There is no single account that is best for everyone. A useful comparison should weigh the interest rate against the account’s total cost, convenience, protections, and eligibility rules.

    1. Compare APY using your expected balance

    Start with the balance you normally keep in checking, not an unusually high temporary balance. Review the APY tiers and calculate how much interest the account could produce under realistic conditions. For example, an account paying a high rate on only a small qualifying balance may produce less interest than an account with a lower rate that applies to more of your funds.

    Use the institution’s disclosures to check whether the APY is variable, when interest is credited, and whether the rate can change without notice. Most deposit account rates are variable unless the bank or credit union states otherwise. A rate comparison is therefore a snapshot, not a promise of future earnings.

    2. Examine monthly maintenance fees

    A monthly fee can offset interest earnings and reduce the value of a checking account. Look for the standard monthly charge and every available waiver. Waivers may depend on direct deposit, a minimum daily balance, combined balances, recurring transfers, or another relationship with the institution.

    Choose an account whose waiver requirements you can meet consistently. If your income varies, a no-monthly-fee account may be more practical than an account with a higher APY but a difficult waiver. Review other checking account fees, including out-of-network ATM charges, incoming or outgoing wire fees, paper statement fees, stop-payment charges, and account closure fees.

    3. Review overdraft and insufficient-funds policies

    Overdraft coverage differs widely. Some institutions decline a transaction, some may transfer money from a linked account, and others may pay the transaction subject to a fee or an approved credit arrangement. Ask whether the account offers a grace period, low-balance alerts, or fee-free overdraft protection.

    Do not assume that opting into debit-card overdraft coverage prevents all fees. Read the account agreement and understand how checks, recurring electronic payments, ATM withdrawals, and card transactions are handled. Setting up alerts and maintaining a small cash buffer can reduce the chance of an accidental overdraft.

    4. Check ATM and branch access

    A high APY may not be worthwhile if you frequently pay ATM fees or cannot conveniently deposit cash. Check whether the institution operates branches, participates in a shared ATM network, reimburses some out-of-network fees, or accepts mobile check deposits.

    Online banks may offer competitive rates and lower fees but may have fewer in-person services. Community banks and credit unions may provide local access, while credit unions generally require membership eligibility. The National Credit Union Administration provides information about federal credit union share insurance and membership, while the Federal Deposit Insurance Corporation explains deposit insurance for participating banks.

    5. Evaluate digital banking and customer support

    Review the mobile app’s available functions, including account alerts, card controls, mobile check deposit, person-to-person payments, external transfers, and secure messaging. Also check support hours and the process for disputing an unauthorized transaction.

    Convenience is part of account value. An account with a strong rate but slow transfers or limited support may be unsuitable if you use it for rent, payroll, bill payments, or frequent travel.

    Potential types of high-rate checking accounts

    Interest-bearing checking accounts

    These accounts pay interest on qualifying balances, often without requiring debit-card rewards. They may be straightforward, but their APY can be lower than specialized rewards accounts. Read the minimum opening deposit, balance requirements, and rate tiers.

    Rewards checking accounts

    Rewards checking accounts may offer a higher APY, cash rewards, or other benefits when you complete monthly activities. Typical conditions can include direct deposit and a minimum number of debit transactions. The account can work well for someone who already uses a debit card regularly, but it may be a poor fit if you would make unnecessary purchases merely to meet a requirement.

    Online checking accounts

    Online checking accounts often emphasize low fees, digital tools, and broad ATM access. Their limitations may include fewer cash-deposit options, no branches, and slower solutions when an account problem requires in-person help. Confirm how quickly external transfers and mobile deposits become available.

    Credit union checking accounts

    Credit unions are member-owned financial institutions. Some provide competitive rates or low fees, but membership rules, branch availability, and technology vary. Verify whether the credit union is federally insured or covered by another authorized share-insurance arrangement, and understand the applicable coverage rules.

    A practical comparison method

    Use the following process before opening an account:

    1. Define your priorities. Decide whether your main goal is interest, no monthly fee, local branches, cash access, budgeting tools, or a combination.
    2. Estimate your normal balance. Include the amount you expect to keep after bills clear, not money reserved for rent, taxes, or other near-term obligations.
    3. Collect official disclosures. Record the APY, balance tiers, minimum deposit, monthly fee, waiver conditions, overdraft terms, ATM fees, and transaction limits.
    4. Calculate net value. Estimate interest and rewards, then subtract fees you are likely to incur. Treat rewards as uncertain if they depend on behavior you may not maintain.
    5. Confirm eligibility. Check direct-deposit definitions, membership requirements, geographic limits, identity-verification rules, and whether joint accounts are supported.
    6. Test operational fit. Review transfer timing, bill-pay features, cash deposits, customer service, and the procedure for replacing a lost card.
    7. Recheck after opening. Save the fee schedule and monitor statements, rate changes, and waiver requirements. An account that was competitive at opening may not remain so.

    Sources and comparison methodology

    This article uses a disclosure-first methodology rather than claiming a live ranking. Compare the current official account agreement, rate sheet, and fee schedule for each institution. The Consumer Financial Protection Bureau provides consumer guidance on checking accounts, overdrafts, and deposit products. The FDIC provides information about deposit insurance and bank deposit accounts. For credit unions, consult the NCUA and the institution’s own disclosures.

    Independent comparison sites can help you create a shortlist, but their information may become outdated or may reflect advertising relationships. Use them for research, then verify every important term directly with the bank or credit union. When comparing institutions, use the same assumptions for balance, monthly activity, direct deposit, ATM usage, and fees.

    How checking compares with other financial products

    A checking account should fit into a broader personal finance plan. Keep enough for routine bills and a reasonable cash buffer in checking, then consider whether surplus cash belongs in a high-yield savings account, certificate of deposit, or another appropriate deposit product.

    When choosing a credit card, compare the annual fee, interest rate, rewards rules, redemption limits, and your ability to pay the balance in full. Best credit cards and rewards are not necessarily the cards with the largest advertised bonus; a simple card with no annual fee may be more suitable for someone who wants predictable costs.

    If high-interest debt is affecting your cash flow, compare personal loans and debt-consolidation options carefully. A lower monthly payment can result from a longer repayment period and may increase total interest. For a home purchase, a mortgage rate comparison should include the annual percentage rate, lender fees, points, closing costs, and loan features rather than the headline rate alone.

    Insurance is another part of the comparison process. When reviewing car insurance and home insurance, compare coverage limits, deductibles, exclusions, claims service, and premium changes. A lower premium is not automatically better if it leaves an important coverage gap.

    For long-term goals, compare retirement accounts and IRAs based on tax treatment, investment choices, fees, employer contributions, withdrawal rules, and risk tolerance. Budgeting calculators and tools can help estimate how much money should remain in checking for monthly expenses. Free credit reports, on-time payments, low credit utilization, and correcting inaccurate report information can support credit score improvement, although no legitimate service can guarantee a particular score increase.

    Pros and cons of high-rate checking accounts

    Potential advantages

    • Interest or rewards can provide value on money already needed for everyday spending.
    • Online institutions may offer lower routine fees and useful digital tools.
    • Automated alerts and budgeting features can make cash-flow management easier.
    • Keeping spending and bill money in one account can simplify routine finances.

    Potential disadvantages

    • The highest advertised APY may require activities that are easy to miss.
    • Rates are commonly variable and may fall after the account is opened.
    • Balance caps can limit the amount that earns the advertised rate.
    • Online-only service may be inconvenient for cash deposits or complex disputes.
    • Rewards and interest may not compensate for fees, overdrafts, or unnecessary spending.

    Limitations to keep in mind

    Account comparisons cannot predict future rates, service quality, fraud outcomes, or how consistently you will meet monthly requirements. Advertised APYs may be introductory, variable, conditional, or limited to a particular balance. Deposit insurance has coverage limits and rules, and it does not protect against investment losses, market declines, or every type of financial institution failure. Review current disclosures and seek qualified advice for tax, legal, debt, or investment questions.

    Q&A

    Are high-rate checking accounts safe?

    A checking account at an eligible FDIC-insured bank or federally insured credit union generally provides deposit protection within applicable limits. Verify the institution and coverage directly; insurance does not eliminate every banking risk or guarantee a particular rate.

    Is checking APY more important than fees?

    Not always. If your balance is modest, a monthly fee or repeated ATM charges can exceed the interest earned. Compare estimated interest, rewards, and likely fees together.

    Should all emergency savings stay in checking?

    Usually, no. Keep enough for near-term bills and a cash buffer in checking, but consider a suitable savings product for funds that do not need daily access. Compare withdrawal access, rate, and account protections.

    Can I change checking accounts easily?

    You can usually open a new account and move recurring deposits and payments, but do not close the old account until outstanding checks, card transactions, and automatic debits have cleared. Use a checklist to avoid missed payments.

    Informational disclaimer: This article is for general education and is not personalized financial, tax, legal, or investment advice. Verify rates, fees, insurance status, and eligibility with the financial institution before making a decision, and protect account credentials with strong passwords and multifactor authentication.

  • How Much Do Banks Charge for Checking Accounts? A Practical Fee Comparison Guide

    How Much Do Banks Charge for Checking Accounts? A Practical Fee Comparison Guide

    Checking accounts are designed for everyday money management, including receiving income, paying bills, withdrawing cash, and making debit-card purchases. However, the account advertised as “free” may still have charges for certain services or for failing to meet stated requirements. The answer to how much do banks charge for checking accounts depends on the institution, account type, balance, transaction habits, location, and whether you qualify for fee waivers.

    A useful comparison does not focus only on the monthly maintenance fee. It also reviews overdraft policies, ATM access, minimum balance rules, incoming and outgoing transfer fees, paper statements, foreign transactions, and other costs that may affect your actual spending. This guide explains common checking account fees, how to compare them, and how to reduce avoidable charges without assuming that one account is best for every customer.

    What Is a Checking Account Fee?

    A checking account fee is a charge connected with maintaining or using a transaction account. Some fees are recurring, such as a monthly maintenance charge. Others apply only when you use a particular service or when an account event occurs, such as an overdraft or use of an out-of-network ATM.

    Some checking accounts have no monthly maintenance fee, but “no monthly fee” does not necessarily mean “no possible fees.” A bank may still charge for overdraft services, wire transfers, stop-payment requests, cashier’s checks, foreign transactions, or certain ATM withdrawals. The fee schedule and account agreement are more reliable than a marketing label.

    How Much Do Banks Typically Charge?

    What Is a Checking Account Fee?
    What Is a Checking Account Fee?

    There is no single industry-wide checking account price. Common pricing patterns include:

    • Monthly maintenance fees: Some traditional checking accounts charge a recurring fee, while others waive it when you meet conditions such as maintaining a qualifying balance, receiving regular direct deposits, or linking eligible accounts.
    • Online checking accounts: Many online banks offer accounts without a monthly maintenance charge, although eligibility, ATM policies, and service availability differ.
    • Basic or second-chance accounts: These may have different fee structures, transaction limits, or eligibility requirements. They can be useful for people rebuilding banking access, but the account agreement should be reviewed carefully.
    • Premium accounts: Some accounts charge a higher recurring fee in exchange for added services, relationship benefits, or special support. The value depends on whether you actually use those features.
    • Credit union accounts: Credit unions may have different pricing and membership requirements. A credit union is a member-owned financial cooperative, not simply a bank with a different name.

    Because fee amounts and waiver requirements change, a comparison should use the current fee schedule for each account. Do not rely on an old article, a search result snippet, or a general statement that an account is “free.”

    Common Checking Account Fees to Compare

    Monthly maintenance fee

    This is the most visible recurring charge. Ask whether it is charged every statement cycle and exactly how it can be waived. Requirements may include direct deposit, a minimum daily balance, a minimum combined balance across linked accounts, or qualifying debit-card activity.

    A waiver is not always free in practice. For example, maintaining a required balance may mean keeping money in a low-interest account instead of a high-yield savings account. Compare the cost of the fee with the potential opportunity cost of meeting the waiver condition.

    Overdraft and insufficient-funds charges

    An overdraft can occur when a transaction exceeds the available balance and the bank pays it, subject to the account’s policies. An insufficient-funds event can occur when a transaction is rejected or returned because the account lacks enough available money. Policies vary widely, and some institutions do not charge for certain declined transactions while others may charge for paid or returned items.

    Ask whether the bank offers low-balance alerts, linked savings transfers, a line of credit, or an overdraft grace period. These services may have their own terms or costs. Opting into debit-card overdraft coverage can affect whether certain everyday card transactions are approved when funds are insufficient, so read the disclosure before making a choice.

    ATM fees

    Your bank may charge for using another institution’s ATM, and the ATM owner may impose a separate surcharge. Some banks reimburse certain out-of-network ATM fees, subject to limits or conditions. Others provide access to a broad network but offer little or no reimbursement outside it.

    ATM access is especially important if you regularly use cash, travel, live in an area with few network machines, or bank primarily through an online institution. Compare the network locator, reimbursement rules, withdrawal limits, and international ATM policies.

    Transfer, wire, and payment fees

    Electronic transfers between your own accounts may be free, but some banks charge for expedited transfers, outgoing wires, incoming wires, or international transactions. Bill-pay services can also have separate rules for expedited payments or payments sent by paper check.

    If you frequently move money between banks, examine transfer timing as well as price. A free transfer that takes several business days may be less useful than a paid service when timing is important. Never assume that a transfer is complete merely because it appears as pending.

    Paper statement and account service fees

    Some institutions charge for paper statements, cashier’s checks, money orders, stop-payment requests, research requests, or account closure within a stated period. These fees are often infrequent, but they matter when comparing accounts for specific needs.

    Foreign transaction and currency-conversion fees

    Debit-card purchases made abroad or processed by a foreign merchant may involve a foreign transaction fee or a currency-conversion cost. The bank, card network, ATM operator, or merchant may each play a role. Travelers should check the bank’s international fee disclosure and use caution when an ATM or merchant offers to convert the transaction into the customer’s home currency.

    How to Compare Checking Accounts Step by Step

    1. List your normal account activity

    Write down how you use banking services in a typical month. Include direct deposits, cash withdrawals, debit-card purchases, bill payments, transfers, checks, travel, and the lowest balance you usually maintain. Also consider whether you need branches, weekend support, cash deposits, or access to a safe-deposit service.

    2. Identify the fees most likely to affect you

    A person who rarely uses cash may care more about transfer limits and overdraft controls than ATM reimbursement. Someone who receives paper checks or deposits cash may prioritize branch availability. A frequent traveler may focus on international card and ATM charges.

    3. Read the official disclosures

    Use the account’s current fee schedule, deposit agreement, privacy notice, and consumer disclosures. The Consumer Financial Protection Bureau, or CFPB, explains many deposit-account concepts and consumer protections. The Federal Deposit Insurance Corporation, or FDIC, provides information about deposit insurance and bank accounts. These sources can help you understand terminology, but the bank’s own agreement determines the account-specific price and conditions.

    4. Calculate the likely annual cost

    Estimate the recurring fee for a full year, then add the services you are likely to use. Subtract a waiver only if you can reliably satisfy its requirements. For example, an account with a maintenance fee may cost less than an apparently free account if the latter regularly charges for out-of-network cash withdrawals or transfers that you use often.

    Use a simple worksheet with columns for monthly fees, ATM costs, overdraft-related costs, transfer fees, foreign transaction fees, and other likely services. Compare both a normal month and an unexpected month in which your balance is lower or you need a special service.

    5. Check access, technology, and protections

    Price is only one part of a checking account comparison. Review mobile deposit limits, check-writing availability, customer service hours, branch access, security alerts, account lock features, and how quickly you can report unauthorized transactions. Confirm whether the institution is FDIC-insured or, for an eligible credit union, federally insured through the National Credit Union Administration. Deposit insurance coverage has rules and limits, so review the insurer’s official guidance for your situation.

    6. Recheck the terms periodically

    Banks can change fees and requirements with notice under applicable rules. Review statements and notices, especially after a merger, account conversion, change in employment direct deposit, or move to a new location. An account that was economical when you opened it may no longer fit your habits.

    Ways to Reduce Checking Account Fees

    • Set a low-balance alert and an alert for large or unusual transactions.
    • Keep a small cash buffer if doing so does not interfere with essential bills or higher-priority savings goals.
    • Use the bank’s ATM network and verify the location before withdrawing cash.
    • Ask whether direct deposit or a linked account waives the monthly charge.
    • Turn on account notifications for pending and posted transactions.
    • Review automatic payments and cancel subscriptions you no longer use.
    • Use electronic statements if they are secure and convenient for you.
    • Ask customer service about fee reversals when an unusual event occurs, but do not treat a courtesy reversal as a guaranteed policy.
    • Maintain a separate emergency reserve or savings account when possible so a single timing error is less likely to disrupt bill payments.

    Pros and Cons of Different Checking Account Types

    Traditional branch checking

    Pros: Branch access, cash services, in-person support, and a familiar range of banking products may be useful. Customers who deposit cash or need cashier’s checks may value local access.

    Cons: The account may have a monthly charge or waiver requirements. Branch hours, ATM availability, and service quality vary by location, and some accounts may pay little or no interest.

    Online checking

    Pros: Online institutions may offer low recurring costs, strong digital tools, and broad ATM partnerships. Lower operating costs can sometimes support simpler fee structures.

    Cons: Cash deposits, urgent in-person assistance, and certain specialized services may be less convenient. ATM reimbursement and transfer limits require careful review.

    Interest-bearing checking

    Pros: The account may earn interest on eligible balances while retaining checking functionality.

    Cons: The advertised rate may require direct deposit, a minimum balance, a transaction threshold, or other conditions. Compare the actual yield with a high-yield savings account and consider whether withdrawals, access, and insurance arrangements meet your needs.

    How Checking Accounts Fit Into a Broader Personal Finance Plan

    A checking account is usually the operating hub of a household budget, not the entire financial plan. A budgeting calculator or spending tool can help you forecast bills, track irregular expenses, and identify the minimum balance you need each month. A linked savings account may be appropriate for emergency reserves, while a credit card can provide convenience or rewards if you pay the balance as agreed and understand its interest rate and fees.

    Checking fees should also be separated from borrowing costs. Personal loans and debt consolidation involve interest, origination fees, repayment periods, and credit consequences. Mortgage rate comparison requires attention to the annual percentage rate, points, closing costs, loan type, and qualification assumptions. Car insurance and home insurance comparisons should consider coverage, deductibles, exclusions, and claims service rather than premium alone.

    Longer-term decisions include retirement accounts and IRAs, where taxes, investment risk, contribution rules, and withdrawal restrictions matter. Improving a credit score generally involves consistent on-time payments, managing balances responsibly, reviewing credit reports, and disputing inaccurate information. A checking account can support these goals by making income and bill timing easier to manage, but it does not replace an emergency fund, appropriate insurance, or a diversified long-term plan.

    Limitations of Checking Account Comparisons

    Published comparisons can become outdated when banks revise fee schedules, change ATM networks, or alter waiver requirements. A fee may also depend on state law, account history, customer status, transaction type, or how a bank calculates the available balance. Advertised rates and benefits may be available only to eligible customers and may change over time.

    Comparison tables can simplify complex terms and may not capture service quality, fraud response, accessibility, or the convenience of a local branch. Before opening an account, confirm the current terms directly with the institution and save a copy of the disclosures. If a fee or transaction is unclear, ask the bank to explain how it was calculated.

    Concise Q&A

    Is a free checking account really free?

    It may have no monthly maintenance fee, but other charges can still apply. Check the full fee schedule, including ATM, overdraft, wire, transfer, foreign transaction, and special-service fees.

    What is the most important checking account fee?

    For many customers, the monthly maintenance fee is the easiest cost to notice, but the most important fee is the one you are most likely to incur. Cash users may focus on ATM costs, while people with variable income may prioritize overdraft policies and alerts.

    Can a bank change checking account fees?

    Generally, banks can revise account terms subject to applicable laws and required notices. Read statements, email notices, and updated disclosures so you can compare alternatives if the account changes.

    Should I choose the account with the lowest fees?

    Not automatically. Consider access, security tools, customer support, cash services, transfer speed, deposit insurance, and whether the fee waivers are realistic for your circumstances.

    Bottom Line

    When asking how much banks charge for checking accounts, look beyond the advertised monthly price. Compare the complete fee schedule, model your actual usage, verify waiver conditions, and consider access and consumer protections. The most suitable account is usually the one whose total cost, features, and service model match your regular habits—not necessarily the account with the lowest headline fee.

    Informational disclaimer: This article is for general educational purposes and is not personal financial, tax, legal, or investment advice. Banking fees, insurance rules, and account terms can change. Review current disclosures and consider consulting a qualified professional before making a financial decision.

  • What Is the Chase Bank Checking Account Fee? A Clear Guide to Monthly Charges and Ways to Avoid Them

    What Is the Chase Bank Checking Account Fee? A Clear Guide to Monthly Charges and Ways to Avoid Them

    If you are comparing bank accounts, you may be asking, what is Chase Bank checking account fee? The short answer is that Chase does not have one universal checking-account charge. Monthly service fees and waiver rules depend on the specific Chase account, your age or student status, and qualifying activity such as direct deposits or maintaining a required balance. Other charges—such as overdraft, out-of-network ATM, wire-transfer, and paper-statement fees—may apply separately.

    This guide explains how Chase checking fees generally work, how to check the current terms, and how to compare the account with alternatives. Fees can change, so treat this article as an educational overview rather than a substitute for the account agreement or current fee schedule.

    What is a Chase Bank checking account fee?

    A Chase Bank checking account fee is a charge connected with maintaining or using a Chase checking account. The most commonly discussed fee is the monthly service fee, sometimes called a maintenance fee. It is charged each statement period unless you meet the account’s waiver conditions. Depending on the product, those conditions may include a qualifying electronic deposit, a minimum daily balance, or a combination of balances held with Chase.

    There can also be transaction-specific fees. Examples include fees for certain overdraft situations, non-Chase ATM use, outgoing wire transfers, cashier’s checks, replacement documents, and optional paper statements. A checking account may advertise a way to avoid its monthly fee while still charging for these other services.

    How Chase checking account fees are structured

    What is a Chase Bank checking account fee?
    What is a Chase Bank checking account fee?

    Monthly service fee

    Chase offers several consumer checking products, and each has its own pricing. A standard everyday account may have a monthly fee that can be waived when you satisfy a listed requirement. Premium or relationship accounts may use different balance rules and may provide additional features. Student, minor, and other specialized accounts can have separate eligibility and fee terms.

    Because account names, prices, and waiver requirements may change, the reliable answer is found in the current Chase checking account pages and the applicable deposit account disclosures. Look for the section labeled “Monthly Service Fee,” “How to Avoid the Monthly Service Fee,” or similar wording.

    Common ways a monthly fee may be waived

    Depending on the account, Chase may allow a customer to avoid the monthly fee through one or more of the following methods:

    • Receiving qualifying electronic deposits, such as payroll, a government benefit, or another eligible recurring deposit.
    • Maintaining a specified minimum daily balance.
    • Keeping a required combined balance across eligible Chase deposit or investment accounts.
    • Meeting an age, student, or other account-specific eligibility condition.

    Not every deposit qualifies. A transfer from another bank, a cash deposit, or a payment from one Chase account may not meet the definition of a qualifying electronic deposit. Read the precise account disclosure rather than assuming that any incoming money will waive the fee.

    ATM and cash-access fees

    Using a Chase ATM is generally different from using an ATM outside the Chase network. A non-Chase ATM operator may impose its own surcharge, and Chase may also apply an out-of-network fee under the account’s terms. International ATM use can involve additional charges and exchange-rate considerations.

    Before withdrawing cash, check the ATM screen for a surcharge and review the account’s current fee schedule. If the machine displays a fee you do not want to pay, cancel the transaction before confirming it.

    Overdraft and insufficient-funds charges

    Overdraft rules are separate from the monthly service fee. A transaction may be declined, returned, or paid into overdraft depending on the account, transaction type, available balance, and applicable service. Some accounts have policies that can reduce or eliminate certain overdraft fees, but that does not mean every overdraft-related event is free.

    Chase may offer alerts, balance tools, and account controls that help customers monitor spending. These tools are useful, but they do not guarantee that a transaction will be prevented or that timing differences will not occur. Card authorizations, deposits, recurring payments, and pending transactions can affect the amount available to spend.

    How to find the exact current Chase checking fee

    1. Identify the exact account name. “Chase checking” is not a single product. Find the account name in online banking, your statements, or the account-opening documents.
    2. Open the current fee schedule. Use Chase’s official website or contact Chase through a verified phone number, secure message, or branch. Do not rely solely on an old article or a search-result summary.
    3. Read the waiver conditions. Check whether the rule requires a minimum daily balance, a qualifying deposit, a combined balance, or another condition.
    4. Review nonmonthly charges. Look for ATM, overdraft, wire, stop-payment, cashier’s-check, foreign-exchange, and paper-statement fees if those services matter to you.
    5. Confirm timing. Ask when the monthly fee is assessed and how a qualifying deposit or balance is measured. Some rules use a statement cycle or daily balance rather than a simple end-of-month snapshot.
    6. Keep records. Save the disclosure or fee schedule that applied when you opened the account, then check for later notices of changes.

    Worked example: why the advertised fee may not be your actual cost

    Suppose an account has a monthly service fee but offers a waiver for a qualifying direct deposit. A customer whose employer sends eligible payroll to the account may pay no monthly service fee. Another customer with irregular freelance income might not receive a qualifying deposit and could be charged the fee. A third customer may qualify through a balance requirement but lose the waiver after a large bill reduces the balance during the measurement period.

    The practical cost is therefore not just the listed monthly fee. It is the total of fees you are likely to incur based on your real habits. A useful comparison should include account access, ATM availability, deposit needs, overdraft preferences, minimum-balance risk, and any interest paid on the balance.

    Pros and cons of a Chase checking account

    Potential advantages

    • Large branch and ATM presence: Customers who value in-person banking or frequent cash access may find a major national network convenient.
    • Digital banking tools: Mobile and online banking can support transfers, alerts, bill payments, mobile check deposit, and balance monitoring.
    • Multiple account tiers: Customers with different needs may be able to choose among everyday, student, and relationship-oriented products.
    • Broader banking relationship: Some customers prefer having checking, savings, credit cards, or lending products with one institution, although each product has separate terms.

    Potential disadvantages

    • Fee-waiver conditions: A monthly fee may apply if you cannot meet the account’s deposit or balance requirement.
    • Limited checking interest: An everyday checking account may not be designed to maximize the return on idle cash.
    • Out-of-network costs: People who often use non-Chase ATMs may pay more than they would with an account offering broad ATM-fee reimbursement.
    • Complexity: The difference between account-specific charges, transaction fees, and waiver rules can make comparisons less straightforward.

    How Chase compares with other checking options

    There is no universally best checking account. Compare Chase with a local credit union, a community bank, and an online bank. An online account may offer a lower monthly fee or a larger ATM network, but it may provide fewer branches or make cash deposits less convenient. A credit union may have member eligibility requirements. A local bank may offer personal service while maintaining a smaller ATM footprint.

    Use a simple comparison table with these categories:

    • Monthly service fee and the easiest realistic waiver.
    • Minimum opening deposit and minimum balance.
    • Direct-deposit requirements and early-pay availability, if offered.
    • ATM access, out-of-network charges, and international-use terms.
    • Overdraft options, alerts, and linked savings features.
    • Mobile deposit, bill pay, customer support, and branch access.
    • Interest rate, if the account pays interest, and whether a high-yield savings account would be better for reserves.

    For a fair comparison, use official disclosures from each institution. The Consumer Financial Protection Bureau’s bank-account guidance is another useful named source for understanding account features and questions to ask. The Federal Deposit Insurance Corporation’s consumer education resources explain deposit insurance and banking basics. These sources support the comparison methodology; they do not replace the current terms for a specific Chase account.

    Ways to reduce checking-account costs

    Use alerts and a cash-flow calendar

    Set low-balance, deposit, and transaction alerts where available. List paydays, rent, utilities, loan payments, subscriptions, and credit-card due dates on a calendar. This can reduce the chance of an avoidable overdraft or a missed fee-waiver condition.

    Separate spending money from savings

    Keep near-term spending in checking and emergency reserves in an account suited to savings. A high-yield savings account may offer a more competitive rate than checking, but review withdrawal rules, access, and account fees before moving money.

    Reassess after life changes

    A new job, loss of direct deposit, graduation, relocation, or retirement can change whether an account remains suitable. Recheck the waiver rules after such events rather than waiting for repeated charges to appear.

    Limitations and important cautions

    Fees and eligibility rules can vary by account, state, customer status, and the date of the disclosure. Promotional offers may have additional conditions. A bank’s fee schedule may not describe every circumstance in plain language, and pending transactions can make available-balance calculations difficult. If you see an unfamiliar charge, review the transaction detail and contact Chase through an official channel.

    Do not provide passwords, one-time verification codes, or full account numbers to someone who contacts you unexpectedly. Banks and legitimate financial institutions do not need your online-banking password to investigate a routine fee. If you are comparing accounts, verify website addresses and phone numbers independently.

    Concise Q&A

    Is the Chase checking account free?

    It may be free of a monthly service fee if you meet the applicable waiver condition. It is not necessarily free of every possible transaction or service charge.

    What is the easiest way to avoid a Chase checking fee?

    For many customers, meeting the account’s qualifying electronic-deposit rule is practical, but the easiest method depends on the specific account and your income pattern. Confirm the definition and timing in the current disclosure.

    Does a transfer from another bank count as direct deposit?

    Not necessarily. A qualifying electronic deposit is defined by the account terms, and ordinary bank-to-bank transfers may not qualify.

    Can I change to a different Chase checking account?

    Possibly, subject to eligibility and Chase’s current procedures. Compare the new account’s fee, waiver rules, features, and any consequences before switching.

    Where should I verify the exact fee?

    Use the official Chase account page, your account agreement, the current fee schedule, secure online banking, or a verified Chase representative. The exact account name is essential.

    Bottom line

    The answer to “what is Chase Bank checking account fee?” depends on the account you have and whether you meet its waiver requirements. Start with the exact monthly service fee, then examine ATM, overdraft, wire, and other charges. Compare your likely annual cost—not just the advertised fee—with alternatives that fit your need for branches, cash access, digital tools, and savings returns. Reviewing official Chase disclosures and reputable consumer guidance can help you make a better-informed banking decision.

    Informational disclaimer: This article is not financial, legal, or tax advice. Banking fees and account terms can change. Verify current terms directly with Chase before opening, changing, or closing an account.

  • What Are Truist Checking Account Fees? A Practical Guide to Monthly, ATM, Overdraft, and Other Charges

    What Are Truist Checking Account Fees? A Practical Guide to Monthly, ATM, Overdraft, and Other Charges

    Truist checking account fees depend on the account type, how you use the account, and whether you qualify for a fee waiver. For many customers, the main charge to examine is the monthly maintenance fee. Other possible costs include overdraft fees, out-of-network ATM fees, wire transfer charges, cashier’s check fees, and fees related to special account services.

    This guide explains what are Truist checking account fees, how the most common charges work, and how to compare a Truist account with other banking products. Fee amounts and waiver rules can change, so confirm the current terms in the applicable Truist fee schedule and account agreement before opening an account.

    What Are Truist Checking Account Fees?

    Truist checking account fees are charges that may apply when you maintain or use a Truist checking account. They generally fall into four groups:

    • Account maintenance fees: recurring charges for keeping an account open.
    • Transaction and access fees: charges for certain ATM withdrawals, wire transfers, cashier’s checks, or other services.
    • Overdraft and returned-item fees: charges that may apply when a transaction exceeds the available balance or is returned unpaid.
    • Optional service fees: charges for products or services that are not required for ordinary checking use.

    The relevant fee is not always the listed price. A monthly fee may be waived if you meet the account’s eligibility requirements, while an account advertised as having no monthly fee may still charge for out-of-network ATM use, expedited services, or certain transactions.

    Common Truist Checking Account Charges

    What Are Truist Checking Account Fees?
    What Are Truist Checking Account Fees?

    Monthly maintenance fee

    Truist One Checking has a standard monthly maintenance fee listed by Truist as $12. Truist describes several ways customers may qualify to have this fee waived, including meeting a qualifying direct-deposit requirement, maintaining the required balance, or qualifying through an age-based condition. The exact requirements and definitions apply according to the account agreement and current fee schedule.

    That distinction matters. A direct deposit may need to meet Truist’s definition of a qualifying deposit, and the bank may evaluate eligibility during a specified statement cycle. Transfers between your own accounts may not receive the same treatment as payroll, government, or other qualifying deposits. Before relying on a waiver, read the disclosure for the account you plan to open.

    Truist also offers other checking products, including Truist Confidence Account. This account is designed for customers who want a lower-risk account structure and does not include traditional overdraft capability. It has its own monthly fee and waiver rules, so its pricing should not be assumed to match Truist One Checking.

    Overdraft and returned-item fees

    Truist’s published personal deposit account fee schedule lists a $36 overdraft fee for an item paid into overdraft, subject to the terms and limits in the schedule. A returned-item fee may also apply when a transaction is returned unpaid. The bank’s policies can vary by account and transaction type, and an overdraft protection service may change how a transaction is handled.

    Do not evaluate overdraft exposure by looking only at the stated fee. Consider when transactions post, whether pending transactions affect available funds, whether recurring payments can overdraw the account, and whether the account has an overdraft grace period or other limit. Some transactions may be declined rather than paid, which can create separate problems such as a late payment or merchant fee.

    ATM fees

    Using a Truist ATM is generally different from using a non-Truist ATM. A non-Truist ATM operator may charge its own fee, and Truist may charge an additional out-of-network ATM fee depending on the account and transaction. The ATM should display the operator’s surcharge before you confirm the withdrawal.

    ATM access is an important comparison point if you regularly withdraw cash. A bank with a smaller branch and ATM network may be less convenient even when its monthly fee is lower. Check the account’s current ATM fee policy, the size of the network in places you visit, and whether reimbursement is available.

    Wire transfers and other banking services

    Truist may charge fees for domestic or international outgoing wire transfers, incoming wires, cashier’s checks, official checks, stop-payment requests, and other special services. These charges are usually separate from the monthly maintenance fee. The price may also differ between online, branch, and other service channels.

    For occasional services, ask for the current price before submitting the request. For recurring use, such as sending wires for a business, supporting family overseas, or managing a real estate transaction, compare the full service fee with alternatives such as an online bank or a regulated payment provider. Exchange-rate markups and intermediary-bank charges can affect the total cost of an international transfer even when the visible bank fee looks modest.

    Truist Checking Account Fee Comparison

    Fee category What to review Why it matters
    Monthly maintenance Listed fee, waiver conditions, and evaluation period A recurring fee can outweigh a higher interest rate elsewhere.
    Overdraft Paid-item fee, returned-item fee, grace period, and transaction controls Occasional mistakes can become expensive if the account routinely runs near zero.
    ATM access Network size, out-of-network fees, and reimbursement policy Frequent cash withdrawals can make ATM charges more important than the monthly fee.
    Special services Wire transfers, official checks, stop payments, and expedited services These costs matter when you use banking services beyond ordinary card and bill transactions.
    Account restrictions Minimum opening deposit, eligibility, transaction limits, and balance rules A lower-cost account may have features or limits that do not fit your routine.

    How to Avoid or Reduce Truist Checking Fees

    1. Identify the account and its exact disclosure

    Start with the account name, not a general search for Truist fees. Truist One Checking, Truist Confidence Account, and other deposit products can have different fees and features. Download or review the current fee schedule and the account’s Truth in Savings disclosure. Save a copy for your records because terms can be updated later.

    2. Test whether the monthly-fee waiver is realistic

    Write down the waiver conditions and compare them with your actual finances. If the requirement involves direct deposit, confirm that your employer or benefits payer sends a deposit that qualifies. If it involves a balance, determine whether maintaining that balance would reduce your emergency savings or cause you to carry a costly credit-card balance.

    A waiver is useful only when it occurs consistently. Do not keep unnecessary cash in a checking account solely to avoid a fee if the money could serve a more important purpose, such as paying high-interest debt or building an emergency fund.

    3. Use balance alerts and transaction controls

    Set low-balance and large-transaction alerts through online or mobile banking. Review pending and posted transactions regularly, especially around rent, mortgage payments, subscriptions, and automatic transfers. Keep a small buffer only if doing so fits your budget. A buffer is not a substitute for checking the account because authorization and posting times can differ.

    4. Plan ATM use

    Use Truist’s ATM locator before traveling or withdrawing cash. When a non-Truist ATM is unavoidable, read the fee disclosure on the screen and consider whether a larger, planned withdrawal is less costly than multiple small withdrawals. Avoid choosing an ATM based only on convenience if the combined operator and bank fees are material to your budget.

    5. Ask before ordering special services

    Before requesting a wire transfer, cashier’s check, stop payment, or expedited delivery, ask the bank to state the applicable fee and any third-party charge. For international transfers, ask how the exchange rate is determined and whether an intermediary bank could deduct a charge from the amount received.

    Pros and Cons of a Truist Checking Account

    Potential advantages

    • Branch and ATM access: Customers who value in-person service may prefer a regional bank with branches and ATMs in their area.
    • Fee-waiver options: Customers who already receive qualifying direct deposits or can meet the balance requirement may avoid the standard monthly maintenance fee.
    • Account choices: Truist offers more than one checking structure, including an account designed to limit traditional overdraft risk.
    • Integrated banking: Customers using Truist savings, credit cards, mortgages, or other services may find one-bank account access convenient.

    Potential disadvantages

    • Monthly fee risk: The standard fee can be meaningful for customers who do not meet the waiver conditions.
    • Complexity: The lowest-cost option depends on account-specific rules, qualifying deposits, statement cycles, and service usage.
    • Possible overdraft costs: A customer who regularly misjudges available funds can incur charges or have payments declined.
    • Different digital-bank pricing: Some online checking accounts may offer lower monthly fees or broader ATM reimbursement, although they may provide fewer branches or cash services.

    How Truist Compares With Other Checking Accounts

    A fair comparison should use your expected annual cost rather than the advertised monthly fee alone. Add the monthly maintenance fee you are likely to pay, expected ATM charges, wire or service fees, and any overdraft-related cost based on your own behavior. Then compare that total with accounts from online banks, credit unions, and other full-service banks.

    Also compare the features that have value even when they do not appear as a line-item fee:

    • Access to branches and cash deposits
    • ATM network and reimbursement policy
    • Mobile deposit, bill pay, and transfer speed
    • Overdraft settings and account safeguards
    • Customer support availability
    • Interest paid on checking balances, if any
    • Connection to savings, credit cards, loans, or mortgage products

    For a broader personal finance comparison, keep checking money separate from savings goals. A checking account is usually designed for payments and liquidity, while a high-yield savings account may be more appropriate for cash that does not need to cover immediate transactions. A rewards credit card may offer benefits, but interest charges can exceed those rewards when balances are carried. Similarly, an advertised loan or mortgage rate should be compared with the annual percentage rate, fees, repayment terms, and your credit profile.

    Limitations of Fee Comparisons

    Published fee tables do not predict the cost for every customer. Your total may depend on account eligibility, location, service channel, transaction type, balance history, deposit timing, and policy changes. A bank may also change its fee schedule after you open an account, subject to applicable notice requirements.

    There is also a difference between a bank fee and a fee charged by another party. An ATM owner, payment network, intermediary bank, merchant, or biller may impose a separate charge. When comparing accounts, identify who receives each fee and whether it can be avoided.

    Sources and Comparison Methodology

    This article uses the Truist Personal Deposit Accounts Fee Schedule, Truist checking-account disclosures, and Truist product information as the primary sources for account-specific pricing and waiver conditions. It also follows consumer account-comparison principles described by the Consumer Financial Protection Bureau, including reviewing overdraft practices, account disclosures, and the total cost of banking services. Because pricing and eligibility rules can change, the current Truist documents control over any summary in this article.

    To compare products, list the fees you are likely to incur over a typical year, check the waiver conditions, and verify the network and features that affect your daily use. Use the same assumptions for every bank or credit union in the comparison. Do not compare a waived fee at one institution with an unavoidable fee at another without checking whether you can realistically qualify for the waiver.

    Q&A

    Does Truist One Checking always charge a monthly fee?

    No. Truist One Checking has a listed monthly maintenance fee, but qualifying customers may have it waived under the account’s current rules. Confirm the direct-deposit, balance, age, or other eligibility conditions before assuming the waiver applies.

    What is the listed Truist One Checking monthly fee?

    Truist lists a $12 monthly maintenance fee for Truist One Checking. The applicable account disclosure and fee schedule should be checked for current pricing and waiver requirements.

    Can Truist charge an overdraft fee?

    Truist’s published fee schedule lists a $36 fee for an item paid into overdraft, subject to account terms and applicable limits. Transactions may instead be declined or returned, and those outcomes can have different consequences.

    Is the Truist Confidence Account the same as a regular checking account?

    No. The Confidence Account uses a different structure and is intended to help limit overdraft risk. It has its own monthly fee, waiver rules, and transaction features, so compare its disclosure separately.

    How can I find the exact fee for my account?

    Check your account agreement, current Truist Personal Deposit Accounts Fee Schedule, online banking disclosures, or a Truist representative. Ask which fee applies before ordering a special service or making a transaction through a non-Truist provider.

    Informational disclaimer: This article is for general educational purposes and is not banking, tax, legal, credit, or investment advice. Bank fees and account terms can change. Verify the current Truist disclosures and consider your own budget and financial circumstances before opening or changing an account.

  • How to Waive Chase Checking Account Fees: Requirements, Options, and Alternatives

    How to Waive Chase Checking Account Fees: Requirements, Options, and Alternatives

    Chase checking accounts can be convenient for everyday banking, but some accounts may charge a monthly service fee unless you meet specific waiver requirements. Learning how to waive Chase checking account fees can help you avoid unnecessary costs and compare the account fairly with other checking products, high-yield savings accounts, and banking alternatives.

    The exact requirements depend on the Chase checking account you have, your age, and whether you qualify for a special relationship or account feature. Fees and eligibility rules can change, so review your current account agreement and Chase’s official fee schedule before relying on any requirement.

    What Does It Mean to Waive a Chase Checking Account Fee?

    A fee waiver means that Chase does not charge the standard monthly service fee because you satisfy one or more qualifying conditions during the statement period. The account remains open and available, but the monthly maintenance charge is reduced to zero for that period.

    For many Chase checking accounts, qualifying conditions may include receiving eligible electronic deposits, maintaining a required balance, linking certain Chase accounts, or meeting an age-based exemption. These conditions are not interchangeable across every product. A requirement that applies to one Chase account may not apply to another.

    It is also important to distinguish a monthly service fee from other possible charges. Overdraft fees, out-of-network ATM fees, wire-transfer fees, stop-payment fees, returned-item fees, and optional service charges may have separate rules. Meeting a monthly fee waiver requirement does not necessarily eliminate every other account fee.

    Common Ways to Waive Chase Checking Account Fees

    What Does It Mean to Waive a Chase Checking Account Fee?
    What Does It Mean to Waive a Chase Checking Account Fee?

    1. Receive an eligible direct deposit

    One of the most common ways to waive a monthly checking fee is to receive an eligible direct deposit during the statement period. This may include payroll, government benefits, pension income, or other qualifying recurring payments, depending on Chase’s current terms.

    An electronic payment that merely resembles a direct deposit may not qualify. Transfers from another bank, mobile-payment applications, cash deposits, checks, and manual account-to-account transfers can be treated differently. If your employer permits it, routing your regular paycheck to the Chase account is usually the simplest way to satisfy a direct-deposit condition.

    Before changing your payroll instructions, confirm the definition of an eligible deposit with Chase. Ask whether the deposit must come from an employer or government agency, whether multiple smaller deposits count, and which statement period is used. Keep in mind that payroll changes can take one or more pay cycles to begin.

    2. Maintain the required balance

    Some Chase checking products allow a monthly fee waiver when you maintain a specified minimum daily balance or an average balance. These are different tests. A minimum daily balance may require that your balance never fall below a threshold, while an average balance requirement may calculate the average over the statement period.

    Do not assume that a balance shown at the end of the month is enough. A large deposit made just before the statement closes might not satisfy a daily-balance requirement. Likewise, pending transactions can reduce your available balance before they appear as fully posted transactions.

    Using a balance requirement can make sense if you already keep sufficient cash in checking for bills and emergencies. However, holding extra money in a low-interest checking account has an opportunity cost. Compare the checking yield, if any, with rates available from high-yield savings accounts, certificates of deposit, or other appropriate cash-management products.

    3. Link qualifying Chase accounts or services

    Some account packages may offer a fee waiver when you have qualifying linked accounts or meet relationship requirements. The qualifying relationship may involve another Chase deposit account, an eligible investment relationship, or a specific account structure.

    Linking accounts can simplify transfers and provide a consolidated view of your finances, but it should not be done solely to avoid a fee without examining the broader terms. A linked product may have its own fees, investment risks, minimums, or eligibility rules. Review each product independently rather than treating the relationship benefit as a complete measure of value.

    4. Use an age-based or student exemption

    Chase offers certain account options or fee exemptions for eligible students and younger customers, subject to age, enrollment, and account-specific requirements. Eligibility may end when you reach a specified age or no longer meet the relevant student condition.

    If you qualify for a student account, check whether proof of enrollment is required and what happens when the account changes to another product. A conversion may affect monthly fees, overdraft settings, interest, and other features. Read the notice provided by the bank and update your account before the exemption expires.

    5. Choose a different Chase checking product

    If you cannot reliably meet the waiver requirements, switching to another Chase checking product may be worth considering. The alternative could have a lower monthly fee, different eligibility rules, fewer features, or different ATM and overdraft terms.

    Do not compare accounts by monthly fee alone. Consider branch access, ATM availability, mobile-banking features, cash-deposit options, check-writing needs, overdraft policies, wire fees, international-use costs, and customer-service preferences. A product with a lower stated fee may be less suitable if it adds costs elsewhere or lacks an important feature.

    Practical Steps to Avoid the Monthly Fee

    Step 1: Identify your exact account

    Sign in to Chase online banking, inspect your monthly statement, or contact Chase to confirm the account name. “Chase checking” is not one uniform product. Requirements can vary between accounts marketed for everyday banking, premium relationships, students, and other customer groups.

    Step 2: Find the current fee and waiver section

    Look at the account’s current fee schedule, deposit account agreement, and disclosures. Chase’s official website and account documents are the primary sources for current requirements. The Consumer Financial Protection Bureau also provides general information about bank account fees and deposit accounts, although it does not replace the account’s own contract.

    Step 3: Choose a waiver method you can maintain

    Select a condition that fits your normal cash flow. Direct deposit may be practical for a salaried worker, while a balance requirement may suit someone with predictable savings. Avoid selecting a method that requires frequent transfers or leaves too little money for rent, debt payments, or emergency expenses.

    Step 4: Track the relevant dates and balances

    Use account alerts, a budgeting app, or a spreadsheet to monitor deposits, statement dates, and balances. Set alerts for low balances and upcoming bills. Remember that the available balance can differ from the ledger balance because of pending debit-card transactions, holds, or deposits that have not yet cleared.

    Step 5: Review the statement each month

    Check whether the fee was waived. If a fee appeared even though you believe you qualified, contact Chase promptly and ask which condition was not met. Keep records of direct deposits, transfers, account notices, and conversations. A bank representative can explain how the requirement was calculated and whether a correction is available under the bank’s policies.

    What May Not Count Toward a Fee Waiver?

    Many customers confuse any incoming money with an eligible direct deposit. A transfer from a savings account, a payment from another person, a check deposit, a cash deposit, or a payment from a brokerage account may not qualify under the account’s definition. Likewise, a balance requirement may be based on daily or average balances rather than the amount visible on one date.

    Transfers between Chase accounts may also be treated differently from outside electronic deposits. If your strategy depends on a particular transaction, confirm the treatment with Chase before assuming it will waive the fee. Bank employees may give general guidance, but the written account disclosures control if there is a conflict.

    Pros and Cons of Common Waiver Strategies

    Direct deposit

    • Pros: It can be automatic, convenient, and easy to repeat when your employer or benefits provider supports it.
    • Cons: Changing payroll instructions may take time, and eligibility can depend on the type of deposit rather than simply its amount.

    Maintaining a balance

    • Pros: It may work without changing where your income is deposited and can provide a cash cushion for regular bills.
    • Cons: Money held in checking may earn little or no interest, and unexpected withdrawals can cause you to miss the requirement.

    Using a relationship or linked account

    • Pros: Linking accounts may simplify transfers and provide a consolidated banking relationship.
    • Cons: The linked account may have separate fees, minimums, or investment risks, and a relationship feature may not be worth the cost by itself.

    Changing accounts

    • Pros: A different account may have waiver terms that better match your income and spending patterns.
    • Cons: The new account may have fewer features, a different fee schedule, or conversion rules that require updating automatic payments.

    How to Compare Chase With Other Banking Products

    A personal finance comparison should examine total annual cost, not just the advertised monthly fee. List the fees you are most likely to incur, including ATM charges, overdraft-related charges, wire fees, check costs, foreign transaction costs, and fees for cashier’s checks or money orders. Then compare those costs with the account’s benefits.

    Also consider whether you need a linked savings account. A checking account is designed for transactions, while a high-yield savings account may be more appropriate for emergency savings or short-term goals. Savings accounts can have withdrawal or transfer rules, so they should not automatically replace checking for bill payments.

    Other related products require separate comparisons. A rewards credit card should be judged by annual fees, interest rates, redemption rules, and your ability to pay the balance in full. Personal loans and debt-consolidation loans should be compared using total repayment cost rather than the monthly payment alone. Mortgage rates, car insurance, home insurance, retirement accounts, and IRAs each involve different fees, risks, tax rules, and eligibility requirements.

    Budgeting calculators can help estimate whether maintaining a balance is realistic. Credit-score tools may help you monitor credit behavior, but a checking-account fee waiver generally does not require a particular credit score. Avoid taking on debt or opening an unnecessary product simply to qualify for a banking benefit.

    Limitations and Important Exceptions

    Account terms can change, and promotional or relationship pricing may have expiration dates. A bank may also revise how it defines eligible deposits, qualifying balances, or linked relationships. This article provides general educational information and does not determine the requirements for your specific account.

    Fee waivers may not apply retroactively, and a customer-service adjustment is not guaranteed. If your account is overdrawn or a payment is returned, that event may create costs unrelated to the monthly service fee. Read notices about account conversions, age-based eligibility, and changes to deposit agreements.

    Concise Q&A

    Can a transfer from another bank waive a Chase checking fee?

    Not necessarily. An external transfer may not meet the account’s definition of an eligible direct deposit. Confirm the transaction type with Chase and review the current disclosure.

    Does a large one-time deposit usually qualify?

    A one-time deposit may not satisfy a direct-deposit requirement, and it may not satisfy a balance test if the required balance must be maintained daily or averaged over time.

    Can I ask Chase to remove the fee?

    You can contact Chase and explain the situation, but a refund or courtesy adjustment is discretionary. The most reliable approach is to meet the written waiver requirement or select an account whose terms fit your circumstances.

    What is the safest way to avoid missing a requirement?

    Use account alerts, maintain a cash buffer, monitor pending transactions, and review every statement. Avoid relying on a last-day transfer when the terms use daily balances or processing dates.

    Bottom Line

    To waive Chase checking account fees, first identify your exact account and its current monthly-fee conditions. Eligible direct deposit, a required balance, a qualifying relationship, an age or student exemption, or a different account may provide a solution. The best option is the one you can maintain without sacrificing emergency savings, paying unnecessary linked-account costs, or taking on debt.

    For current requirements, use Chase’s official account disclosures and fee schedule, and compare them with general consumer guidance from the Consumer Financial Protection Bureau. Banking terms can change, so verify details directly before changing payroll, closing an account, or moving substantial funds. This article is for general informational purposes only and is not financial, tax, legal, or banking advice.

  • What Is Wells Fargo Checking Account Fees? A Clear Guide to Monthly, ATM, Overdraft, and Other Costs

    What Is Wells Fargo Checking Account Fees? A Clear Guide to Monthly, ATM, Overdraft, and Other Costs

    What is Wells Fargo checking account fees? It is the total cost of using a Wells Fargo checking account, including any monthly service charge, ATM fees, overdraft-related charges, wire fees, and fees for optional services. The amount you pay depends on the specific Wells Fargo account, how you use it, and whether you meet conditions that waive or reduce certain charges.

    This guide focuses mainly on the Wells Fargo Everyday Checking account, a commonly compared consumer account. Fees and waiver requirements can change, so review the current account agreement and fee schedule before opening an account. A checking account comparison should consider the full cost of regular use rather than focusing only on the advertised monthly fee.

    Definition: What Are Wells Fargo Checking Account Fees?

    Wells Fargo checking account fees are charges connected with maintaining and using a Wells Fargo deposit account. They may include:

    • A monthly service fee for maintaining the account.
    • Out-of-network ATM fees or fees charged by another ATM operator.
    • Overdraft or returned-transaction charges, depending on the transaction and the bank’s current policies.
    • Fees for cashier’s checks, wire transfers, stop payments, expedited services, or other optional transactions.
    • Foreign transaction or international ATM costs when using a debit card outside the United States.

    These charges are separate from interest rates, credit card fees, personal loan costs, and mortgage charges. A checking account generally exists for everyday spending, bill payments, direct deposits, and cash access. It is not the same as a high-yield savings account, which is usually designed for holding money rather than making frequent payments.

    How Much Is the Wells Fargo Everyday Checking Monthly Fee?

    Definition: What Are Wells Fargo Checking Account Fees?
    Definition: What Are Wells Fargo Checking Account Fees?

    Wells Fargo’s published disclosures have listed a $10 monthly service fee for Everyday Checking. The bank has also listed ways to avoid that fee, including meeting one of several qualifying conditions during the monthly fee period. Commonly published waiver conditions include:

    • Receiving at least $500 in qualifying electronic deposits.
    • Maintaining a minimum daily balance of $1,500.
    • Having an account owner who is at least 17 and no older than 24, subject to the account’s eligibility rules.

    Qualifying electronic deposits generally refer to recurring electronic deposits such as payroll, government benefits, or other eligible payments sent through an electronic payment network. Transfers between Wells Fargo accounts, branch deposits, ATM deposits, mobile deposits, and some person-to-person transfers may not qualify. The precise definition is controlled by Wells Fargo’s account disclosures, so do not assume that every deposit will satisfy the waiver.

    The monthly fee is not necessarily the most important cost. For example, an account with a fee waiver may still become expensive if you regularly use non-Wells Fargo ATMs, overdraft the account, send wires, or use international services. Conversely, a customer who receives qualifying direct deposit and uses Wells Fargo ATMs may pay no monthly service fee and few additional fees.

    Other Wells Fargo Checking Account Costs to Review

    ATM fees

    Wells Fargo generally does not charge its customers for using Wells Fargo ATMs, but charges can apply when you use another financial institution’s ATM. The ATM owner may also impose its own surcharge. International ATM withdrawals can involve additional Wells Fargo fees, currency-conversion costs, and charges from the foreign ATM operator or payment network.

    Before comparing checking accounts, estimate how often you withdraw cash and where you normally do it. A bank with a nearby ATM network may be less expensive for a cash-heavy household than an account with a lower monthly fee but limited ATM access. Some online banks reimburse certain ATM fees, while others do not.

    Overdraft and declined-transaction costs

    Overdraft treatment depends on the transaction type, account settings, and the bank’s current policy. A transaction may be declined, paid into overdraft, or covered through an optional protection service. Wells Fargo disclosures have described overdraft-related fees and limits that can vary by product and circumstance. The exact current amounts should be confirmed in the account fee schedule.

    Overdraft protection can sometimes link a checking account to another deposit account or an eligible line of credit. It may reduce the chance that a payment is returned, but it can have transfer fees, interest charges, or other costs. Protection is not free simply because it prevents a traditional overdraft charge.

    To limit overdraft risk, turn on low-balance alerts, keep a buffer for pending transactions, review automatic payments, and avoid treating available balance as a guarantee that every pending transaction has posted. Debit card transactions, checks, and electronic payments can appear at different times.

    Checks and official bank services

    Paper checks, cashier’s checks, money orders, stop-payment requests, and expedited delivery may have separate charges. Customers who rarely use these services may not consider them important. Customers who pay rent, buy vehicles, close on property, or send large payments should review the applicable fee before requesting one.

    Wire transfers and international use

    Incoming and outgoing wire transfers typically have different prices. Domestic and international wires may also use different fee schedules. A recipient’s bank, an intermediary bank, or currency conversion may create additional costs that are outside Wells Fargo’s own fee.

    Debit card use abroad can also involve foreign transaction costs or exchange-rate differences. If you travel frequently, compare the bank’s international ATM and card policies instead of judging the account only by its domestic monthly fee.

    Practical Steps to Find Your Actual Wells Fargo Checking Cost

    1. Identify the exact account

    Wells Fargo offers more than one checking product, and eligibility, fees, and benefits can differ. Start with the account name shown in your application, statement, online banking profile, or account agreement. Do not apply the Everyday Checking fee schedule to another product without checking its own disclosures.

    2. Check the monthly fee waiver

    Write down which waiver you expect to use. If it is qualifying electronic deposit, confirm that your employer or benefit provider sends the payment in a way Wells Fargo recognizes. If it is a balance waiver, calculate whether the required balance can be maintained without interfering with emergency savings, debt payments, or other financial goals.

    3. Review your expected transactions

    Estimate your monthly use of ATMs, paper checks, wires, cashier’s checks, international withdrawals, and optional protection services. Then review the related fee entries in the bank’s current schedule. A simple budgeting calculator or spreadsheet can help compare annual costs.

    4. Separate avoidable fees from necessary costs

    Some charges are avoidable through account habits, such as using in-network ATMs or enabling alerts. Others may be necessary for a particular transaction. This distinction matters when comparing banks. A low advertised fee does not automatically mean a lower total cost if the account does not fit your normal behavior.

    5. Read the account agreement before opening the account

    Look for the monthly service fee, fee-waiver rules, overdraft provisions, ATM fees, transaction limits, and rules for qualifying deposits. Also review how the bank defines the fee period and when deposits count. Keep a copy of the disclosures because the terms may be updated later.

    Neutral Pros and Cons of Wells Fargo Checking

    Potential advantages

    • The monthly service fee may be avoidable for customers who meet a qualifying electronic-deposit, balance, or age-based condition.
    • Customers who regularly use Wells Fargo branches and ATMs may find the account convenient.
    • Online and mobile banking can make it easier to monitor transactions, deposit checks, and set account alerts.
    • A large bank may offer a broad range of related products, including credit cards, savings accounts, mortgages, and personal loans.

    Potential disadvantages

    • Customers who cannot meet the waiver requirements may pay a recurring monthly fee.
    • Out-of-network and international ATM use can add costs beyond the monthly charge.
    • Customers who need a high savings yield may find a checking account less suitable for idle cash than a competitive high-yield savings account.
    • Large banks may not always offer the highest deposit rates or the lowest fees across every product category.
    • Fee terms, account eligibility rules, and overdraft policies can change, so older comparisons may become inaccurate.

    How It Compares With Other Banking Options

    A fair banking product comparison should match the account to the customer’s priorities. An online checking account may offer no monthly fee or broader ATM reimbursement, but it might provide fewer branches and limited cash-deposit options. A credit union may offer competitive fees and local service, but membership requirements and technology vary.

    Keep emergency savings separate from routine spending where practical. A high-yield savings account may be better for funds that do not need frequent debit-card access, although withdrawal rules and rates should be reviewed. A checking account is usually better for direct deposit and recurring bills.

    Other personal finance decisions should also be compared independently. For example, a credit card with rewards is not automatically valuable if interest charges outweigh the rewards. A personal loan advertised for debt consolidation should be assessed using the annual percentage rate, fees, repayment term, and total repayment amount. Mortgage rate comparison should include points, lender fees, closing costs, and the planned time in the home. Checking fees are only one part of a broader household budget.

    Limitations of This Comparison

    This article does not provide a personalized recommendation or a complete list of every Wells Fargo fee. Account pricing can vary by product, state, customer age, account ownership, transaction type, and changes to the bank’s disclosures. Waiver rules may depend on how a deposit is coded and when it posts. ATM operators and other financial institutions may charge separate fees.

    The safest way to confirm a current charge is to review the official Wells Fargo consumer account fee schedule and account agreement for the exact product. For a broader view of bank-account protections and overdraft practices, the Consumer Financial Protection Bureau is another useful source. These sources are more reliable for current terms than an old comparison article, forum post, or search-result snippet.

    Concise Q&A

    Can I avoid the Wells Fargo checking monthly fee?

    Often, yes, if you meet an eligible waiver condition. For Everyday Checking, commonly published conditions include qualifying electronic deposits, maintaining the required minimum daily balance, or meeting the account’s age requirement. Verify the current requirements with Wells Fargo.

    Does every direct deposit count?

    No. The deposit generally must meet Wells Fargo’s definition of a qualifying electronic deposit. Payroll and eligible government payments may qualify, while internal transfers, mobile deposits, cash deposits, and some person-to-person payments may not.

    Are Wells Fargo ATMs free?

    Wells Fargo customers generally can use Wells Fargo ATMs without a Wells Fargo ATM fee, but other ATM operators may charge their own fees. Non-Wells Fargo and international ATM transactions may have additional costs.

    Is a Wells Fargo checking account a savings account?

    No. Checking is designed for payments and frequent access. Savings accounts are generally intended for holding money and may provide different rates, withdrawal rules, and fees.

    Where can I verify the current fees?

    Use Wells Fargo’s official consumer account disclosures and fee schedule for the specific account. You can also contact the bank or review the disclosures presented during account opening. The CFPB’s consumer banking resources can help explain general account and overdraft concepts.

    Sources and Methodology

    This article uses a comparison methodology based on publicly available account disclosures rather than personal experience, testing, or promotional claims. The primary source is Wells Fargo’s official consumer checking account fee information and account agreement, which should be consulted for current prices and waiver rules. A secondary source is the Consumer Financial Protection Bureau’s bank-account guidance, including its explanations of account fees and overdraft-related issues. Wells Fargo’s Everyday Checking product page is also useful for current eligibility and account details, but the formal fee schedule and agreement control where information differs.

    Informational disclaimer: This article is for general education and is not financial, legal, tax, or investment advice. Fees and eligibility requirements can change. Confirm the current terms directly with Wells Fargo and consider your own budget, cash-flow needs, and risk tolerance before opening or changing an account.

  • Why Are High Interest Savings Accounts Good? Benefits, Limits, and How to Compare Them

    Why Are High Interest Savings Accounts Good? Benefits, Limits, and How to Compare Them

    High interest savings accounts can be useful for people who want their cash to earn more interest while remaining relatively accessible. They are commonly used for emergency funds, short-term goals, tax payments, and money set aside for a planned purchase. The central appeal is simple: compared with a basic savings account, a high interest savings account may pay a more competitive annual percentage yield (APY), allowing deposited cash to grow faster without taking the market risk associated with stocks or other investments.

    However, a higher savings rate is not automatically the best choice for every situation. Rates can change, withdrawals may be limited or inconvenient, and an account with a strong advertised APY may have conditions such as a minimum balance or direct-deposit requirement. This guide explains why high interest savings accounts can be good, how they compare with other banking products, and what to check before opening one.

    What Is a High Interest Savings Account?

    A high interest savings account is a deposit account designed to pay a relatively competitive rate on cash balances. The term is not a single legal account type, and there is no universal threshold that makes an account “high interest.” In practice, the label usually refers to an account whose APY is substantially above rates commonly available from traditional savings accounts at the time of comparison.

    APY stands for annual percentage yield. It reflects the interest rate and the effect of compounding over a year, assuming the money remains deposited and the rate does not change. This makes APY more useful than the stated interest rate when comparing accounts, although real earnings can differ if the rate changes, the balance changes, or fees apply.

    High interest savings accounts are normally intended for saving rather than frequent spending. They may be offered by online banks, credit unions, and some traditional banks. Before depositing money, verify whether the institution is insured by the Federal Deposit Insurance Corporation (FDIC) or, for an eligible credit union, the National Credit Union Administration (NCUA). Coverage rules and ownership categories matter.

    Why Are High Interest Savings Accounts Good?

    What Is a High Interest Savings Account?
    What Is a High Interest Savings Account?

    They can improve the return on cash

    The most direct benefit is the possibility of earning more interest on money that would otherwise sit in a low-paying account. The difference can be meaningful over time, especially when the balance is substantial or the savings goal extends for many months or years.

    For example, a person building an emergency fund may need the money to remain stable and available. Moving that fund from a low-rate account to a competitive savings account can increase interest without changing the underlying purpose of the money. The benefit comes from using a better deposit product, not from taking investment risk.

    They generally preserve access to the principal

    Unlike investments that can fall in market value, an insured savings account is designed to protect the deposited principal within applicable insurance limits. The account value does not normally fluctuate because of stock-market movements. This can make savings accounts appropriate for short-term goals where avoiding a loss is more important than pursuing a higher potential return.

    Access is usually available through electronic transfers, linked checking accounts, ATM networks, or branch services, depending on the provider. Transfer times vary, so the account should not be treated as an instant replacement for cash kept in a checking account.

    They support separate savings goals

    A separate high interest savings account can help create a boundary between spending money and money reserved for a goal. Common uses include:

    • An emergency fund for unexpected expenses
    • A home down payment or moving costs
    • Annual insurance premiums and tax bills
    • Education expenses or major planned purchases
    • A temporary cash reserve while paying down debt

    Some banks permit multiple accounts or savings “buckets,” which can make budgeting easier. A budgeting calculator or spreadsheet can estimate the monthly contribution needed to reach a target, while the savings account provides a place to hold the money.

    They are usually easier to understand than market investments

    A savings account has a relatively straightforward structure: deposit money, receive interest according to the account terms, and withdraw or transfer funds subject to the provider’s rules. There are no stock selections, trading decisions, or market timing questions. This simplicity can be valuable for short-term cash, even for someone who uses retirement accounts and investments for long-term goals.

    How High Interest Savings Accounts Compare With Other Accounts

    Checking accounts

    Checking accounts are built for regular transactions such as bill payments, debit-card purchases, and direct deposits. They may offer little or no interest, but they often provide more convenient payment features. A practical arrangement is to keep near-term spending money in checking and move surplus cash into a savings account.

    When comparing banks, review checking account fees alongside savings yields. A high savings APY may not compensate for monthly maintenance fees, overdraft charges, out-of-network ATM fees, or costly wire transfers. The best banking product comparison considers the whole relationship rather than one headline feature.

    Certificates of deposit

    A certificate of deposit (CD) may offer a fixed rate for a defined term. In exchange for that predictability, withdrawing money before maturity can result in an early-withdrawal penalty. A high interest savings account generally offers more flexibility but usually has a variable rate. A CD may suit money that can remain untouched until a known date; a savings account may be better for an emergency fund.

    Money market deposit accounts

    Money market deposit accounts may combine savings features with some check-writing or debit-card access. Their rates, minimum balances, and transaction rules vary. Do not confuse a bank money market deposit account with a money market mutual fund, which is an investment product and is not insured in the same way as an FDIC-insured deposit account.

    Credit cards and rewards

    High interest savings accounts and rewards credit cards serve different purposes. A rewards card can provide value when the balance is paid in full and fees are reasonable. Carrying a credit-card balance at a high interest rate generally costs more than a savings account earns. Building savings should not be used to justify expensive revolving debt without a clear repayment plan.

    Personal loans and debt consolidation

    If high-interest debt is the main financial problem, the interest saved by reducing that debt may exceed the return from a savings account. However, an emergency reserve remains important because eliminating all cash savings can lead to new borrowing after an unexpected expense. Debt-consolidation loans should be compared by total cost, fees, repayment term, and whether the borrower can avoid adding new debt.

    Practical Steps for Comparing High Interest Savings Accounts

    1. Identify the purpose and time horizon

    Decide whether the money is for immediate emergencies, a goal within a year, or a longer-term reserve. The shorter and more important the goal, the more weight you may place on stability, access, and low fees instead of chasing a small difference in yield.

    2. Compare APY, not only the advertised rate

    Use APY as the initial comparison measure, then check whether it is variable. Most savings rates can change when market conditions or a bank’s pricing changes. A rate that is attractive today is not a guarantee of future earnings.

    3. Read the fee schedule

    Look for monthly maintenance fees, excess-withdrawal fees where applicable, returned-payment fees, wire fees, ATM charges, and account-closing requirements. Also check whether fees can be avoided with a minimum balance or another condition.

    4. Check minimums and eligibility rules

    Some accounts require a minimum opening deposit, a minimum balance to earn the stated APY, or a particular type of transaction. Confirm whether the rate applies to the entire balance or only a particular balance tier. A lower-rate account with no requirements may be more useful than a higher-rate account that is difficult to maintain.

    5. Confirm insurance and institution details

    The FDIC states that standard deposit insurance is generally up to $250,000 per depositor, per FDIC-insured bank, for each ownership category. NCUA coverage applies to qualifying accounts at federally insured credit unions under its own rules. Confirm the institution’s insurance status through the official FDIC or NCUA resources rather than relying solely on a comparison website.

    6. Evaluate access and transfer speed

    Review how quickly money can move to your checking account, whether the provider has an ATM network, and how customer support is delivered. Online banks may offer competitive rates but fewer branches. If you regularly deposit cash or need in-person service, convenience may justify choosing a different institution.

    7. Estimate after-tax earnings

    Interest from a taxable savings account is generally taxable income in the United States, subject to applicable tax rules. The account’s stated APY is therefore not necessarily the amount you keep. Compare the expected interest with your tax situation and consider whether the account provides a tax form for reported interest.

    8. Automate contributions and review periodically

    Automatic transfers after payday can make saving consistent. Review the APY, fees, balance requirements, and account terms periodically. If the rate falls substantially, compare alternatives, but avoid moving money solely for a temporary promotional rate without reading the conditions.

    Neutral Pros and Cons

    Potential advantages

    • May earn more interest than a basic savings account
    • Can keep short-term money relatively stable and accessible
    • Often has no market-price volatility for the deposit balance
    • Can support emergency funds and goal-based budgeting
    • May be eligible for FDIC or NCUA insurance when held at an insured institution

    Potential disadvantages

    • The interest rate is usually variable and may decline
    • Access can be slower or less convenient than a checking account
    • Fees or minimum-balance rules can reduce the effective return
    • Interest may be taxable outside tax-advantaged arrangements
    • The return may not keep pace with inflation over every period
    • Higher long-term growth may be available through investments, with substantially greater risk

    Limitations to Keep in Mind

    A high interest savings account is not a complete financial plan. It is generally suitable for cash management, not for every long-term objective. Money intended for retirement may need to be evaluated in relation to employer plans, traditional or Roth IRAs, investment risk, fees, and time horizon. A savings account can protect short-term funds but may provide less growth potential over decades.

    Inflation is another limitation. If the purchasing power of goods and services rises faster than the account’s after-tax return, the real value of the money can decline even while the account balance increases. Conversely, investing emergency money in volatile assets can create a different risk: having to sell after a market decline.

    Insurance coverage also has limits. Keep track of balances across banks and ownership categories if your deposits could exceed the applicable coverage amount. Coverage does not protect against every possible issue with a financial product, and it does not apply to ordinary investment losses.

    Concise Q&A

    Is a high interest savings account safe?

    It can be a relatively low-risk place for cash when offered by an FDIC-insured bank or an NCUA-insured credit union and used within applicable coverage rules. Verify the institution and terms directly.

    Can the rate change?

    Yes. Savings APYs are commonly variable. The provider can change the rate, so compare current terms rather than assuming today’s yield will last.

    Should an emergency fund be in a high interest savings account?

    Often, yes, if the account provides suitable access, low fees, and adequate insurance. Keep enough immediately available in checking for bills and urgent needs.

    Are high interest savings accounts investments?

    They are deposit accounts, not market investments. They may offer lower growth potential than long-term investments but generally provide more stability for cash reserves.

    How much should be kept in one?

    The amount depends on income stability, essential expenses, insurance, debt, and upcoming goals. A personal budget can help determine a suitable reserve rather than relying on a universal target.

    Sources and Comparison Methodology

    This article’s comparison framework uses publicly available guidance from the Federal Deposit Insurance Corporation (FDIC) on deposit insurance and from the Consumer Financial Protection Bureau (CFPB) on bank accounts and consumer considerations. For credit-union coverage, consult the National Credit Union Administration (NCUA). A sound comparison should rank accounts by current APY, rate variability, fees, minimums, insurance status, access methods, transfer timing, and tax treatment—not by APY alone. Always confirm current terms on the provider’s official disclosure before applying.

    Informational disclaimer: This article is for general educational purposes and is not individualized financial, tax, legal, or investment advice. Account rates and terms change. Consider your goals, cash needs, debt costs, tax situation, and insurance coverage, and consult a qualified professional when appropriate.