Blog

  • How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison

    How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison

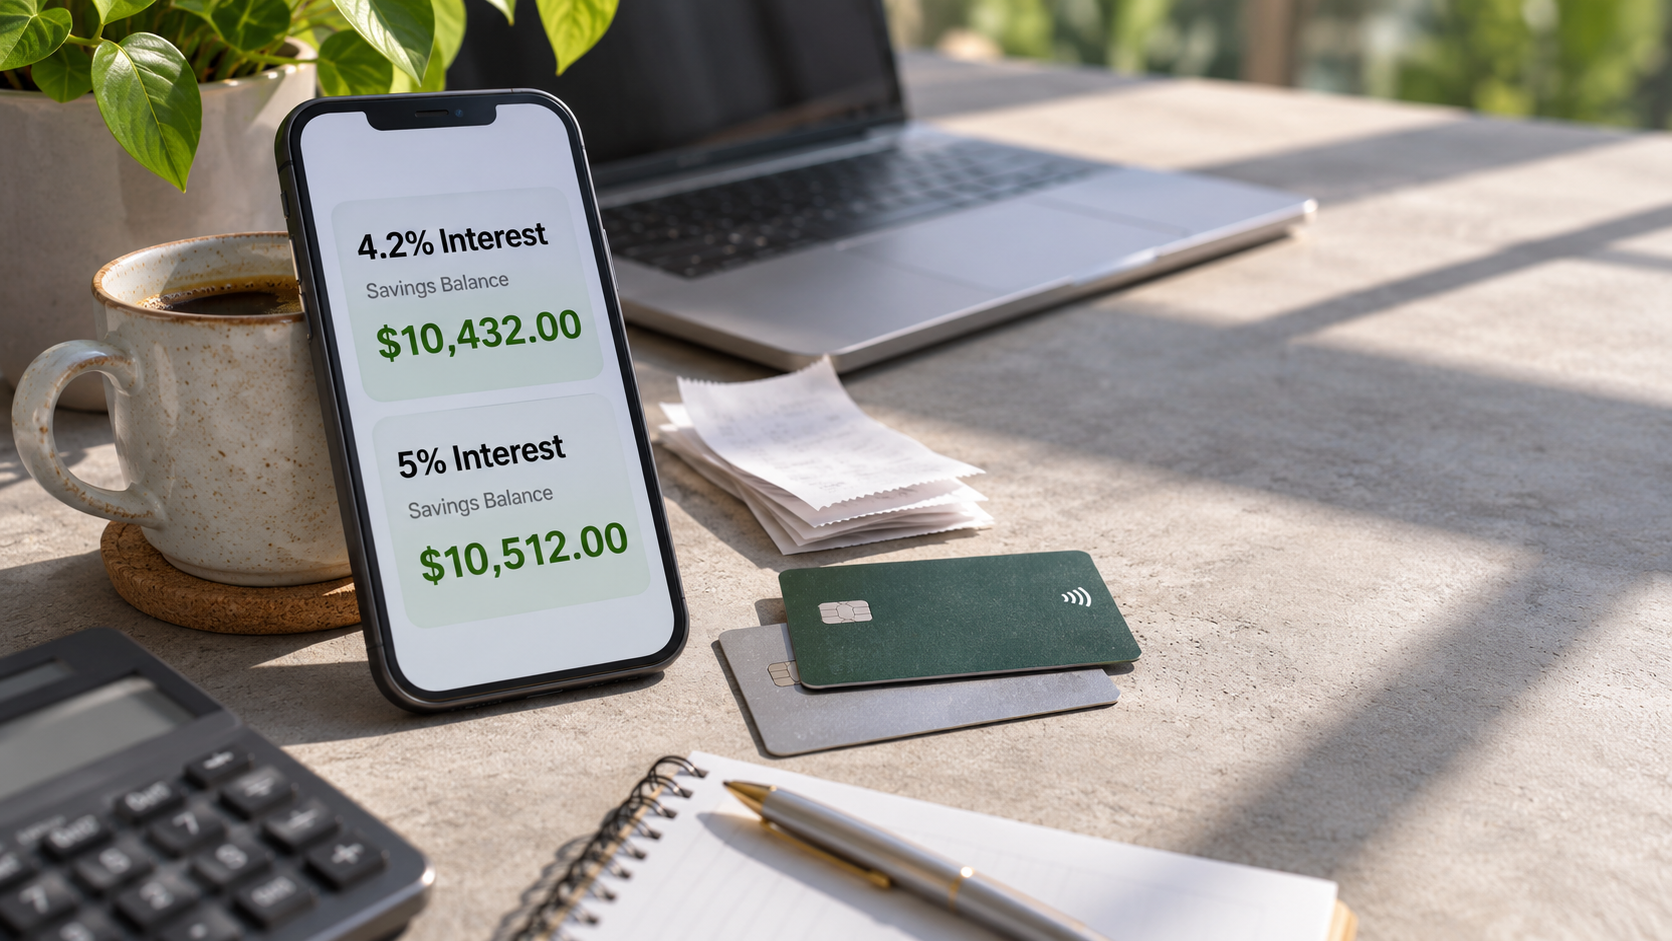
    Comparing a 4.2% rate with a 5% rate can look like a small decision. On a savings balance, though, the difference grows with the amount saved, the time it stays in the account, and how interest is calculated. The practical question is not just which percentage is higher: it is how much extra interest the higher rate may earn, and whether the account’s conditions fit your needs.

    This guide estimates the difference using transparent assumptions, explains how to compare savings accounts, and notes why advertised rates may not match what you ultimately earn. The figures are examples, not rate quotes or a forecast.

    What Does “4.2% Versus 5%” Mean?

    A savings account’s annual percentage yield (APY) expresses the interest an account would earn over one year, including the effect of compounding, assuming the rate and balance remain unchanged. A 5% APY is 0.8 percentage points higher than a 4.2% APY. It is not simply “0.8% more” in every sense: the dollar difference depends on your balance and holding period.

    APY is useful for comparing deposit accounts because it accounts for compounding. The stated interest rate, sometimes called the nominal rate, may not include that compounding effect. When comparing accounts, use APY against APY and check the institution’s terms for how often interest compounds and when it is credited.

    How Much More Could You Earn?
    What Does “4.2% Versus 5%” Mean?: How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison
    What Does “4.2% Versus 5%” Mean?: How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison

    The table below estimates interest on a single deposit that stays in the account for one year, with no additional deposits or withdrawals. It assumes the APY stays constant for the entire year and the balance qualifies for that APY. The figures use the APY relationship directly: ending balance equals starting balance multiplied by one plus APY. They are rounded to the nearest cent.

    Starting balance At 4.2% APY At 5% APY Difference
    $1,000 $42.00 $50.00 $8.00
    $5,000 $210.00 $250.00 $40.00
    $10,000 $420.00 $500.00 $80.00
    $25,000 $1,050.00 $1,250.00 $200.00
    $50,000 $2,100.00 $2,500.00 $400.00

    Under these assumptions, the extra interest is about $8 per year for every $1,000 kept in the account. That is a helpful shortcut for a one-year comparison. It does not mean you will receive that exact amount: variable rates can change, account rules can affect eligibility, and taxes can reduce the amount you keep.

    What If You Add Money Regularly?

    Regular contributions change the calculation because each deposit earns interest only after it enters the account. For example, money deposited near the end of the year has less time to earn than money deposited at the beginning. A calculator that models monthly deposits can give a closer estimate, but you will need to enter the deposit timing, compounding assumptions, and whether the rate is fixed or variable.

    For a straightforward comparison, apply the same deposit schedule to both rates. Comparing one account with monthly contributions to another with a single starting balance would not isolate the effect of the APY.

    Practical Steps to Compare the Accounts
    How Much More Could You Earn?: How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison
    How Much More Could You Earn?: How Much Interest Does 4.2% Versus 5% Earn? A Savings Comparison
    1. Confirm the APY and when it was checked. Savings rates can change. Record the displayed APY and the date you reviewed it. An advertised rate is not a promise that it will last for the full year.
    2. Check whether the rate applies to your balance. Some accounts use balance tiers, set a maximum balance for the top APY, or offer a promotional rate with eligibility requirements. Review the full terms, not just the headline.
    3. Look for fees and minimums. A monthly maintenance fee, minimum opening deposit, or minimum balance requirement can affect whether an account is practical. Ask whether a fee can be avoided and what happens if your balance falls below a threshold.
    4. Review access and transfer timing. Check how you can deposit and withdraw money, whether the provider offers convenient transfers, and whether any limits or processing times matter for your plans. Keep money you may need immediately accessible.
    5. Compare the estimated dollar outcome. Use your own balance and expected saving period. If you expect the rate to change, treat a one-year estimate as an illustration rather than a guarantee.
    6. Verify the institution and account terms. Confirm who holds the deposit, what protections apply, and which legal entity is responsible. A comparison article is a starting point, not a substitute for the account agreement.

    Using Published Comparisons Responsibly

    Several established personal-finance publishers maintain comparisons of savings accounts. Forbes Advisor’s best high-yield savings account awards is one place to review account options and the publisher’s stated evaluation. The Motley Fool’s savings-rate roundup dated November 7, 2026 presents rates in a time-specific format. Money’s high-yield savings account comparison provides another editorial comparison.

    These are named editorial sources, not guarantees of the current rate or suitability of any account. Check each article’s publication or update date, the publisher’s methodology and disclosures, and the financial institution’s own current terms. A list can help you identify candidates, but the account agreement determines the actual conditions.

    Pros and Cons of Chasing the Higher APY

    Potential advantages

    • A higher APY can earn more interest on the same eligible balance if the rate holds and the account conditions are met.
    • Interest may help a reserve for planned expenses or emergencies grow without taking the investment risk associated with market-based assets.
    • Comparing accounts can reveal fees, minimums, or access conditions that matter beyond the headline rate.

    Potential disadvantages

    • A higher APY may be temporary, variable, limited to a balance band, or conditional on specific account activity.
    • Moving money can add administrative work and may temporarily disrupt access while transfers are processed.
    • A fee or restrictive condition can outweigh some or all of the added interest, especially on a small balance.
    • Interest is generally taxable income in the United States, subject to applicable tax rules. The after-tax amount may be lower than the table’s estimate.

    How Savings Fits With Other Financial Comparisons

    A savings account comparison is only one part of personal finance. If you carry credit-card debt, the interest charged on that debt may be much higher than the interest earned on savings. Paying down expensive debt can therefore be worth evaluating alongside building cash reserves, while keeping enough accessible money for near-term needs. The right balance depends on your obligations and circumstances.

    For credit cards, compare annual fees, purchase APRs, rewards rules, and whether you can pay the statement balance in full. Rewards do not necessarily offset interest costs if you carry a balance. For checking accounts, review monthly fees, overdraft terms, ATM access, and minimum balance rules. For personal loans or debt consolidation, compare the total repayment cost and fees, not just the advertised payment.

    The same comparison habits apply elsewhere: mortgage rates need to be evaluated with points, closing costs, and loan terms; auto and home insurance comparisons should account for coverage and deductibles; and retirement accounts and IRAs have different tax treatment and investment risks from bank deposits. Budgeting calculators can help model cash flow, while credit-score tools can help track progress. In every case, compare like with like and read the full terms.

    Limitations to Keep in Mind

    The table assumes one deposit, a constant APY, no fees, no withdrawals, and no taxes. Actual account interest may be calculated using daily balances and credited on a schedule set by the institution. If rates change during the year, your return will differ from the constant-rate example. A promotional APY may expire, and a balance that exceeds a stated limit may earn a different rate.

    These examples also do not account for inflation, which affects what savings can buy over time. A savings account can be useful for cash reserves and near-term goals, but its role is different from long-term investing. Deposit insurance eligibility and limits depend on the institution, account ownership category, and applicable rules. Confirm coverage with the relevant official insurer and the institution rather than relying on a comparison page alone.

    Concise Q&A

    How much more does 5% earn than 4.2%?

    If both are APYs and remain unchanged for one year, 5% earns about $8 more per $1,000 of starting balance. The difference scales with the balance under the same assumptions.

    Is 5% always the better account?

    Not automatically. Check whether the rate is variable or temporary, whether your balance qualifies, and whether fees or access restrictions reduce the benefit.

    Does compounding make the difference larger?

    APY already reflects the effect of compounding over a year. If you are given nominal interest rates instead, compounding frequency matters, so compare APYs where possible.

    Can I use this estimate for monthly deposits?

    Use a calculator that models the timing of each deposit. The table assumes the full starting balance is present for the entire year.

    Bottom Line

    At a constant one-year APY, the gap between 4.2% and 5% is approximately $8 per $1,000 saved. That can be meaningful on a larger balance, but the best choice depends on the rate’s durability, eligibility rules, fees, and access. Compare current account disclosures, use your own expected balance and timeline, and treat published rate roundups as a way to find options rather than as a guarantee.

    Informational only; this article is not personalized financial, tax, or legal advice. Verify current rates, account terms, and applicable protections directly with the provider and qualified professionals when needed.
  • Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guide

    Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guide

    Finding a savings account that offers 5 percent APY can be appealing, but the headline rate is only one part of the comparison. High-yield savings account rates can change, some offers may be limited to new customers or a particular balance range, and a rate that is available today may not be available next month.

    This guide explains how to evaluate accounts advertised near or at 5 percent APY, how to verify whether an offer is genuine, and how savings products fit alongside checking accounts, credit cards, debt repayment, insurance, and retirement planning. It does not identify a single account as permanently offering 5 percent because savings rates are generally variable and depend on the institution’s current terms.

    What does 5 percent APY mean?

    APY means annual percentage yield. It expresses the amount an account could earn over one year when interest is compounded, assuming the rate remains unchanged and the money stays in the account. A 5 percent APY is not the same as a 5 percent interest rate in every circumstance because compounding and account terms affect the final result.

    For example, if $10,000 remained in an account for a full year at a constant 5 percent APY, the balance would be approximately $10,500 before taxes and assuming no fees, withdrawals, or changes to the rate. That illustration is not a promise of earnings. Variable-rate accounts can change their APY at the bank’s discretion, usually in response to broader interest-rate conditions.

    APY also differs from a promotional annual percentage rate on a credit card. Credit card APR usually represents borrowing costs, while savings APY represents interest earned on deposits. Comparing them directly can lead to poor financial decisions.

    Which savings accounts may offer 5 percent APY?

    What does 5 percent APY mean?: Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guide
    What does 5 percent APY mean?: Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guide

    Accounts offering 5 percent APY, or rates close to it, generally fall into several categories. Availability changes frequently, so consumers should confirm the current disclosure, eligibility rules, and account agreement before opening an account.

    1. Promotional high-yield savings accounts

    Some banks and credit unions use a temporary promotional rate to attract new deposits. The offer may apply only to new customers, require a qualifying deposit, or expire after a stated period. A bonus may also be paid separately from the ongoing APY, which means the advertised first-year return may not continue.

    Before relying on a promotional account, check the standard APY after the promotion ends, the length of the promotional period, minimum deposit requirements, and whether early withdrawal or account closure affects the bonus.

    2. High-yield savings accounts with balance conditions

    Which savings accounts may offer 5 percent APY?: Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guid
    Which savings accounts may offer 5 percent APY?: Which Savings Accounts Offer 5 Percent APY? A Practical Comparison Guid

    Some accounts advertise a high rate only on part of a balance or only when the balance stays below or above a specified threshold. Others may require recurring deposits, linked checking activity, electronic statements, or a minimum number of monthly transactions.

    An account that offers 5 percent on the first $5,000 but a much lower rate above that amount may be less attractive than an account with a lower headline rate applied to the entire balance. The account’s tier schedule is therefore as important as its top APY.

    3. Credit union savings products

    Credit unions sometimes offer competitive deposit rates, but membership eligibility can apply. A credit union may also use the term dividend rate rather than interest rate. Compare the dividend APY, membership requirements, minimum balance, access methods, and deposit insurance coverage.

    4. Money market deposit accounts

    A money market deposit account can offer a competitive yield while providing certain checking-like features, such as limited check-writing or debit access. It is still important to distinguish a bank money market deposit account from a money market mutual fund. The former may be eligible for FDIC or NCUA insurance when held at an eligible institution; the latter is an investment product and is not a bank deposit.

    5. Limited-time savings bonuses

    Some institutions combine a relatively ordinary ongoing APY with a cash bonus. When comparing the total value, calculate the bonus separately and read the conditions. A bonus may require a large deposit, a long holding period, direct deposit, or a particular account relationship. A bonus should not be treated as a permanent 5 percent APY.

    Where to research current high-yield savings rates

    Rate tables are useful starting points, but they are not substitutes for the bank’s official terms. The following named sources provide comparison information and can help identify accounts worth investigating:

    These sources use editorial comparison methods that can differ. They may consider yield, fees, minimum deposits, access, customer service, and account features. A product appearing on a list is not a guarantee that it is the best choice for every saver.

    How to compare accounts offering 5 percent APY

    Step 1: Confirm the current APY

    Look for the date on the comparison page and the bank’s own rate page. Search the account disclosure for language such as variable APY, introductory APY, or rates subject to change. If the rate is not shown clearly, contact the institution and ask whether the quoted rate applies to your balance and location.

    Step 2: Check whether the rate applies to the full balance

    Read the tiered-rate table. A 5 percent APY may be limited to a narrow balance range or may apply only after a qualifying action. Calculate the estimated interest on the amount you actually plan to deposit, rather than using the maximum advertised rate.

    Step 3: Review fees and access rules

    Check for monthly maintenance fees, excessive withdrawal fees, wire fees, expedited transfer fees, and minimum-balance charges. Also review how long transfers take, whether the account supports mobile check deposit, and whether customer service is available when you need it.

    Federal rules and bank policies concerning savings-account withdrawals have changed over time, so do not assume every institution uses the same limit or fee policy. Read the current account agreement.

    Step 4: Verify deposit insurance

    For a bank, look for FDIC insurance. For a federally insured credit union, look for NCUA insurance. Coverage generally applies to eligible deposit accounts up to applicable legal limits and ownership categories, not to every product offered by a financial company. Confirm that the institution is insured and understand how accounts at the same bank are combined for coverage purposes.

    Step 5: Compare the account with your existing bank

    A separate high-yield savings account may earn more, but moving money can add administrative work. Consider whether you need instant access, branch service, ATM access, cash deposits, or a direct connection to your checking account. A slightly lower rate may be reasonable if it provides features that prevent missed bills or overdrafts.

    Pros and cons of pursuing a 5 percent savings APY

    Potential advantages

    • Higher earnings: A higher APY can increase interest earned on emergency savings, a planned purchase, or short-term reserves.
    • Lower investment risk: An insured deposit account is generally less exposed to market-price fluctuations than stocks or bond funds, although insurance conditions and limits apply.
    • Simple access: High-yield savings accounts can be easier to understand and access than many investment products.
    • Useful separation: A separate account can make it easier to organize money for taxes, home repairs, travel, or an emergency fund.

    Potential disadvantages

    • Variable rates: The APY can fall without the account balance changing, reducing future interest income.
    • Restrictions: Promotional rates, balance tiers, transfer delays, and eligibility requirements may reduce the practical value of the offer.
    • Taxable interest: Interest income is generally taxable, subject to applicable law and your personal circumstances.
    • Limited growth potential: Cash accounts can be appropriate for short-term goals but may not provide the long-term growth potential associated with diversified investments.
    • Operational inconvenience: An online-only account may not provide branches, cash deposits, or immediate access to funds.

    When a high-yield savings account may not be the priority

    Before moving money solely to earn a higher savings rate, address expensive debt. Paying down a credit card balance with a high interest rate may provide a more predictable financial benefit than earning interest on cash, although an emergency reserve should generally be considered before using all available savings to repay debt.

    For borrowers considering personal loans or debt consolidation, compare the total cost, origination fees, repayment period, and variable or fixed rate. A lower monthly payment can still cost more overall if the repayment term is extended.

    Likewise, compare checking account fees before opening a separate savings account. A savings account that pays more may not compensate for monthly fees, overdraft charges, or costly transfers in a linked checking account.

    How savings fits into a broader personal finance comparison

    A 5 percent APY comparison is one part of a wider financial plan. Use a budgeting calculator or spreadsheet to identify how much cash you need for fixed bills, irregular expenses, and emergencies. Keep money needed soon in an accessible account rather than choosing a product solely for its yield.

    Credit card rewards should also be evaluated carefully. A rewards card may offer points or cash back, but interest charges can outweigh rewards when balances are carried. Paying the statement balance on time is usually more important than maximizing rewards.

    For longer-term goals, compare retirement accounts and IRAs based on tax treatment, investment choices, contribution rules, and withdrawal restrictions. Cash in a savings account can support near-term stability, while retirement accounts are designed for longer time horizons.

    Insurance comparisons matter as well. Reviewing car insurance and home insurance deductibles, exclusions, liability limits, and premiums may produce larger savings than switching bank accounts. Mortgage rate comparison should consider closing costs, points, loan term, and the total interest paid—not just the advertised rate.

    Practical checklist before opening an account

    1. Write down the amount you plan to deposit and the date you may need the money.
    2. Confirm the current APY directly with the bank or credit union.
    3. Determine whether the APY is variable, promotional, tiered, or conditional.
    4. Check minimum deposits, minimum balances, monthly fees, and transfer policies.
    5. Verify FDIC or NCUA insurance and understand applicable coverage limits.
    6. Review the privacy policy, account agreement, and rate disclosure.
    7. Estimate interest using the rate that applies to your actual balance.
    8. Compare the account with debt repayment, checking needs, and other financial priorities.
    9. Set a reminder to review the rate after the promotional period or in several months.

    Limitations of rate comparisons

    Online comparison articles can become outdated because financial institutions change rates, eligibility standards, fees, and product availability. Editorial rankings may also use different criteria, and an account that is competitive for one balance may be less competitive for another. Search results and comparison tables should be treated as research aids, not personalized financial advice.

    Questions and answers

    Is a 5 percent APY savings account available to everyone?

    Not necessarily. The offer may be limited by location, membership, balance, deposit size, promotional status, or customer eligibility. Confirm the terms with the institution.

    Can a savings account keep paying 5 percent forever?

    Usually, you should not assume that it will. Many high-yield savings accounts have variable rates, and promotional rates may expire. Review the ongoing APY and rate-change provisions.

    Is a savings account safer than investing?

    An eligible deposit account at an insured institution generally does not fluctuate in value like a market investment, within applicable insurance limits. It can still lose purchasing power to inflation, and insurance does not cover every financial product.

    Should I move my entire emergency fund for a higher rate?

    Only if the account provides suitable access, insurance, and terms. A small difference in yield may not justify transfer delays or loss of convenient banking features.

    What should I do if the advertised APY is unavailable when I apply?

    Ask the institution whether the offer ended, whether a condition was missed, or whether the rate is available only to a particular balance tier. Do not deposit money until you understand the applicable rate and account agreement.

    Informational disclaimer: This article is for general education and is not individualized financial, tax, legal, or investment advice. Rates, fees, insurance rules, and tax treatment can change. Verify current terms with the financial institution and consider consulting a qualified professional about decisions affecting your money.

  • Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose

    Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose

    Choosing a cash-back card often comes down to a simple trade-off: take a steady rate on most purchases, or earn more in selected categories while accepting limits and extra rules. The right choice depends less on a card’s headline rate than on where you spend, how much effort you want to put into tracking rewards, and whether you can pay the balance in full.

    This guide explains the difference between flat-rate and bonus-category cash-back cards, how to compare their value, and when a combination of both may make sense. It also covers common limitations that can make an advertised reward rate less useful in practice.

    What Are Flat-Rate and Bonus-Category Cards?

    Flat-rate cash-back cards

    What Are Flat-Rate and Bonus-Category Cards?: Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose
    What Are Flat-Rate and Bonus-Category Cards?: Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose

    A flat-rate card earns the same cash-back rate on eligible purchases, regardless of whether you buy groceries, pay a utility bill, or book a hotel. The card’s terms still determine which transactions qualify, but the reward structure is generally consistent across spending categories.

    For example, if a card earns a stated rate on all eligible purchases, you do not have to identify which of your expenses fall into a special category to get that rate. “Flat rate” describes the earning structure, not a promise that every transaction will qualify or that rewards have no other conditions.

    Bonus-category cash-back cards

    A bonus-category card earns a higher rate on specified purchases and a base rate on other eligible spending. Categories may include groceries, dining, gas, travel, or rotating groups of merchants. The exact categories, earning rates, spending limits, activation requirements, and reward rules vary by card and can change over time.

    Some cards use fixed categories; others require the cardholder to activate rotating categories during set periods. A high advertised rate may apply only to a limited amount of spending, and purchases above that limit may earn a lower rate. Always check the current issuer terms before applying.

    How the Two Structures Compare

    Flat-rate cash-back cards: Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose
    Flat-rate cash-back cards: Flat-Rate vs. Bonus-Category Cash-Back Cards: How to Choose
    Factor Flat-rate card Bonus-category card
    Reward pattern One general rate on eligible purchases Higher rates for selected categories; a base rate elsewhere
    Tracking Usually straightforward May require category tracking or activation
    Best fit Mixed spending or a preference for simplicity Concentrated spending in the card’s bonus categories
    Main limitation May earn less than a category card on targeted purchases Rewards depend on category definitions, caps, and rules

    Neither structure is automatically better. A bonus rate is valuable only on purchases that qualify and only if its benefit exceeds what you would earn with a simpler alternative. A flat rate may be more useful when a large share of your budget falls outside bonus categories or when managing multiple reward rules would be inconvenient.

    Compare the Value Using Your Own Spending

    Start with your typical spending rather than a card’s most prominent advertised rate. Use a recent budget or several months of statements to estimate how much you spend in each relevant category. Avoid treating exceptional one-time expenses as normal unless you expect them to recur.

    1. List eligible spending. Estimate monthly or annual spending in categories that matter to you, such as groceries, dining, gas, and general purchases. Do not include payments that the issuer excludes from rewards unless the card terms say they qualify.
    2. Check how categories are defined. A merchant’s name may not determine its category. Issuers commonly rely on transaction coding, and a store with several departments may not code every purchase as groceries or gas.
    3. Apply any caps or activation rules. Calculate bonus earnings only up to the applicable limit, if there is one. Account for any required activation, enrollment, or qualifying conditions.
    4. Compare against a flat-rate baseline. Estimate the rewards you would earn using a flat-rate card on the same eligible spending. Then compare that result with the bonus card’s estimated rewards, including its base rate for purchases outside bonus categories.
    5. Subtract costs and practical friction. Consider annual fees, interest if you sometimes carry a balance, and the effort of tracking categories. Do not assume rewards will offset interest or fees without doing the calculation.

    A simple estimate is: estimated rewards = eligible spending in each category × the applicable reward rate, added across categories. For a bonus card, use the bonus rate only for purchases that meet the terms and remain within any applicable cap. The estimate is a comparison tool, not a guarantee of future earnings.

    For instance, someone with varied spending and little time to monitor offers might prefer the predictability of a flat-rate structure. Someone who consistently spends heavily in a card’s eligible categories may find that a bonus-category structure earns more, provided the category rules fit their purchases and any caps do not erase the advantage. The result depends on individual spending and current card terms, not a universal break-even point.

    Pros and Cons

    Flat-rate cards

    • Pros: The reward structure is easier to understand; purchases outside common bonus categories still earn the general rate; there is usually less need to track changing categories.
    • Cons: The rate may be lower than a category card’s bonus rate on qualifying purchases; a single card may not maximize rewards for someone with concentrated spending in eligible categories.

    Bonus-category cards

    • Pros: They can reward spending in selected categories at a higher rate; fixed categories may match recurring expenses; some cards let cardholders choose among options, subject to their terms.
    • Cons: Categories may not match how a purchase is coded; rotating categories can require activation; spending caps and lower base rates can reduce overall earnings; keeping track of several cards adds complexity.

    In either case, cash back does not make a purchase cheaper if it encourages spending you would otherwise avoid. Rewards should be a secondary benefit of purchases already in your budget.

    When a Two-Card Setup Makes Sense

    Some people use a flat-rate card for general purchases and a bonus-category card for a few predictable expenses. This can capture category rewards without requiring every purchase to be routed through a separate card. It can also introduce more moving parts: separate due dates, different terms, and more opportunities to miss a payment or category activation.

    Consider a two-card setup only if you can keep both accounts organized and pay them on time. A budgeting app, calendar reminder, or account alert may help you track payment dates, but these tools do not replace reviewing statements. If managing one card already feels difficult, a simpler setup may be more suitable even if its estimated rewards are lower.

    What to Check Before Applying

    • Annual fee: Compare the fee with the rewards you realistically expect, not with a best-case spending scenario.
    • Purchase APR and fees: If you carry a balance, interest costs can outweigh cash back. Review the cardholder agreement and current pricing disclosures.
    • Reward exclusions: Check which purchases earn rewards and how refunds, cash-like transactions, balance transfers, and other excluded transactions are handled.
    • Caps and time limits: Look for category spending limits, expiration rules, activation windows, and any conditions on redeeming rewards.
    • Credit eligibility: Approval is not guaranteed. Applying can affect your credit profile, and the issuer may consider factors such as credit history and income under its application process.
    • Redemption options: Confirm how cash back can be redeemed and whether minimum redemption amounts or other conditions apply.

    Compare more than the rewards rate. A card that is less generous on paper may be a better fit if its costs, rules, and day-to-day management suit your circumstances.

    How to Use Published Comparisons

    Editorial rankings can help you identify cards to investigate, but their selections are not a personalized recommendation. Money’s best credit cards overall page and Yahoo Finance’s best credit card comparison are starting points for reviewing card options. The pages may be updated, and their featured products or assessments may not reflect your own budget, eligibility, or preferred reward structure.

    NerdWallet’s announcement of its 2026 Best-Of Awards winners is a company news release. Treat an awards announcement as one source of product context, not as a substitute for comparing current card terms. Award categories and editorial criteria may not answer whether a card is the best match for your spending.

    A practical comparison method is to use independent editorial roundups to create a shortlist, then verify each candidate against its issuer’s current rates, fees, reward rules, and application disclosures. Compare cards using the same spending assumptions and include the base rate, caps, annual fee, and ease of use. This approach avoids treating a ranking, award, or advertised maximum rate as a guarantee of value.

    Common Mistakes to Avoid

    • Choosing by the highest advertised rate alone. The rate may apply only to a narrow category or a capped amount of spending.
    • Assuming a merchant qualifies by name. Transaction coding and issuer definitions determine whether a purchase earns a category bonus.
    • Ignoring the base rate. Spending outside the bonus categories still matters to the overall comparison.
    • Forgetting activation. If a card requires enrollment in a rotating category, missing the activation window may mean purchases earn only the base rate.
    • Carrying a balance for rewards. Interest and fees can exceed the value of cash back. Paying on time and in full is generally important for avoiding interest on purchases, subject to the card’s terms and circumstances.
    • Applying for several cards without a plan. Each application has its own eligibility process, and additional accounts add payment and account-management responsibilities.

    Limitations and Changes Over Time

    Card terms, reward categories, rates, fees, and editorial recommendations can change. A purchase can earn differently than expected if it is processed under an unexpected merchant category, excluded by the issuer, refunded, or subject to a cap. Any calculations in this article are a framework for comparing options, not a promise of rewards.

    Credit-card rewards are only one part of personal finance. A cash-back card does not replace an emergency fund, a debt repayment plan, or a budget. When comparing financial products, consider how a card fits with your existing banking arrangements, savings goals, and overall ability to manage payments.

    Q&A

    Is a flat-rate cash-back card better for beginners?

    It can be easier to manage because the reward rate is less dependent on category tracking. But suitability depends on the card’s terms, costs, and the person’s spending and credit profile.

    Can a bonus-category card earn less than a flat-rate card?

    Yes. If little of your spending qualifies for the bonus, a cap is reached, or the card has a low base rate, total rewards may be lower than with a flat-rate option.

    Do cash-back rewards make it worthwhile to carry a balance?

    No. Rewards should not be treated as a reason to borrow. Interest and fees can outweigh the cash back earned; compare the card’s current terms and prioritize a repayment plan if you carry debt.

    Should I use multiple cash-back cards?

    Only if the added rewards justify the extra tracking and you can manage payment dates and balances reliably. A single card can be preferable when simplicity matters more than optimizing every category.

    Bottom Line

    Choose between flat-rate and bonus-category cash-back cards by comparing your normal eligible spending against each card’s full reward structure. Flat-rate cards emphasize consistency; bonus-category cards may offer more on selected purchases but come with category rules and possible caps. Check current issuer disclosures, account for costs, and avoid spending more to earn rewards.

    Informational disclaimer: This article is for general educational purposes and is not individualized financial, credit, tax, or legal advice. Card terms and eligibility vary; verify current details with the issuer and consider a qualified professional for advice about your circumstances.

  • Are Travel Credit Cards Worth the Annual Fee? A Practical Guide

    Are Travel Credit Cards Worth the Annual Fee? A Practical Guide

    Are travel credit cards worth the annual fee? They can be, if the rewards and benefits you actually use outweigh the fee and deliver more value than a suitable card with no annual fee. The comparison should reflect your normal spending, realistic travel plans, and ability to pay your bill. The FDIC recommends weighing rewards against fees and interest rather than choosing a card for its incentives alone. ([fdic.gov](https://www.fdic.gov/consumers/consumer/news/march2019.html?utm_source=openai))

    This guide uses a recurring annual value comparison: estimate usable rewards, add benefits that replace planned expenses, subtract costs, and compare the result with a practical alternative. Treat welcome bonuses separately so they do not disguise an expensive second year.

    What is a travel credit card?

    A travel credit card earns rewards that can be redeemed toward travel, often through an issuer’s rewards program or an airline or hotel loyalty program. Depending on the card, benefits may include travel credits, airport lounge access, or travel protections. An annual fee is the yearly charge for holding the account, separate from interest and transaction fees. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/are-travel-credit-cards-worth-it/?utm_source=openai))

    Travel cards include general travel rewards cards, airline cards, and hotel cards. Their usefulness depends on where you travel and how you redeem rewards. An airline benefit is less useful if you usually fly another carrier; hotel perks deserve the same scrutiny. Chase’s explanation of travel rewards credit cards describes these different structures and benefits. ([chase.com](https://www.chase.com/personal/credit-cards/education/basics/are-credit-cards-worth-it?utm_source=openai))

    What comparison sources can tell you

    What is a travel credit card?: Are Travel Credit Cards Worth the Annual Fee? A Practical Guide
    What is a travel credit card?: Are Travel Credit Cards Worth the Annual Fee? A Practical Guide

    Independent lists can help identify candidates, but their category winners do not replace a personal calculation. The three sources below illustrate why the meaning of “best” matters:

    • Money’s best credit cards guide separates cards by purpose and considers rewards, fees, introductory offers, and other benefits. Its methodology supports comparing the annual fee with the value a card provides. ([money.com](https://money.com/best-credit-cards-overall/))
    • NerdWallet’s 2026 Best-Of Awards announcement, published January 7, 2026, named Chase Sapphire Preferred its all-purpose travel rewards winner, Capital One Venture X its premium travel winner, and Wells Fargo Autograph its travel card winner without an annual fee. These are distinct categories, not interchangeable recommendations. ([investors.nerdwallet.com](https://investors.nerdwallet.com/news-releases/news-release-details/nerdwallet-announces-its-2026-best-awards-winners?utm_source=aiseotracker.com))
    • Yahoo Finance’s best credit cards comparison, dated September 1, 2026 in the reviewed version, selected Chase Sapphire Preferred for rewards and American Express Gold for travel. Its discussion connects value to everyday spending categories as well as travel benefits. ([finance.yahoo.com](https://finance.yahoo.com/personal-finance/credit-cards/article/best-credit-card-202825345.html?utm_source=openai))

    Use these publications to build a shortlist. Then check current issuer disclosures before applying. Money and Yahoo Finance disclose commercial relationships, and Money notes that its comparison does not include every available offer. ([money.com](https://money.com/best-credit-cards-overall/))

    Calculate whether the annual fee pays for itself

    For this article’s comparison method, use the following calculation:

    Annual net value = usable rewards + usable credits + other benefits you value − annual fee − additional costs.

    Next, calculate the alternative card’s annual net value using the same spending and travel assumptions. The difference between the two results is the potential advantage of paying the fee. This avoids comparing a rewards card with earning nothing.

    A hypothetical comparison

    What comparison sources can tell you: Are Travel Credit Cards Worth the Annual Fee? A Practical Guide
    What comparison sources can tell you: Are Travel Credit Cards Worth the Annual Fee? A Practical Guide

    The following figures are illustrative assumptions, not actual card offers, observed prices, or promised returns. Assume both cards receive the same $15,000 in annual purchases, and all statement balances are paid in full.

    Annual item Travel card No-fee alternative
    Usable rewards $450 $300
    Credits replacing planned spending $60 $0
    Other benefits personally valued $40 $0
    Annual fee −$100 $0
    Additional costs $0 $0
    Annual net value $450 $300

    The travel card leads by $150 under these assumptions. But the result depends on actually receiving $450 of useful rewards and using the benefits. If its rewards were worth only $300 and neither extra benefit were used, its net value would fall to $200—below the alternative.

    Find your spending break-even point

    When comparing rewards alone, divide the annual fee by the travel card’s additional effective reward rate. For example, a hypothetical $100 fee and a one-percentage-point advantage require $10,000 of eligible annual spending to break even: $100 ÷ 0.01.

    Use the rate for your actual spending mix, not the highest advertised category. If the paid card has no rewards advantage, additional spending will not cover the fee through rewards alone; usable benefits must justify it.

    How to value rewards and benefits realistically

    Start with spending you already planned

    Review a year of statements and group purchases into categories such as groceries, dining, transportation, and travel. Apply each candidate’s earning rules to those amounts. Check exclusions and caps rather than assuming every merchant qualifies. The FDIC’s rewards card guidance emphasizes understanding program conditions and considering borrowing costs. ([fdic.gov](https://www.fdic.gov/consumers/consumer/news/march2019.html?utm_source=openai))

    Keep the spending budget fixed across candidates. Increasing purchases to make a card appear worthwhile defeats the purpose of this comparison. If a welcome bonus requires spending beyond your existing budget, exclude that bonus from your estimate.

    Use a redemption you can reasonably make

    For your worksheet, estimate points using a trip you would actually book. Subtract unavoidable award taxes and fees from the comparable cash cost before dividing by the required points. Also compare a reasonable cheaper itinerary: an expensive flight you would never purchase can exaggerate practical savings.

    Build a conservative scenario as well as an expected one. Rewards can lose value, and redemption problems can prevent consumers from obtaining anticipated benefits. The CFPB documented devaluation, promotional conditions, redemption difficulties, and revoked rewards in its review of consumer complaints. That evidence identifies risks; it does not establish that every program has those problems. ([consumerfinance.gov](https://www.consumerfinance.gov/data-research/research-reports/issue-spotlight-credit-card-rewards/?utm_source=openai))

    Count credits at their personal value

    Check the qualifying purchases, booking channel, enrollment requirements, and expiration rules for each credit. For example, Capital One’s card comparison describes a Venture X travel credit tied specifically to Capital One Travel, illustrating why a travel credit should not automatically be treated as unrestricted cash. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/capital-one-credit-cards/?v=1792544075872&utm_source=openai))

    In your calculation, count only the spending the credit replaces. If redeeming it requires a more expensive booking, subtract that price difference. Divide benefits available only once every several years across the relevant period rather than counting the entire amount annually.

    Give convenience a separate value

    Lounge access may improve a trip without producing equivalent cash savings. Assign it an amount you would willingly pay, and check whether eligible lounges serve your routes. Access may require enrollment and can be subject to capacity restrictions, as Capital One explains in its travel card guidance. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/are-travel-credit-cards-worth-it/?utm_source=openai))

    Keep two totals if helpful: measurable savings and personal convenience. This makes it clear whether the fee buys financial value, comfort, or a mixture of both.

    Pros and cons of paying an annual fee

    Potential advantages

    • Useful travel benefits: Eligible credits and perks may reduce expenses on trips you already planned.
    • Rewards flexibility: Some programs provide several redemption routes, including travel bookings or transfers to participating partners.
    • Included protections: Depending on the card and its terms, benefits may include rental car coverage or other travel protections.

    These benefits vary by product; the card’s specific terms determine availability and eligibility. Capital One’s overview describes examples, rather than benefits guaranteed across all travel cards. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/are-travel-credit-cards-worth-it/?utm_source=openai))

    Potential disadvantages

    • A recurring cost: The annual fee reduces value even in a year when your travel plans shrink.
    • More administration: Earning and redeeming rewards can involve conditions that require attention.
    • Uncertain future value: Reward values and program benefits can change.
    • Borrowing costs: Interest can offset the benefit of rewards.

    The CFPB explains that reward benefit changes may not receive the same advance notice as certain pricing changes. Its interest guidance also shows why repayment behavior belongs in any card comparison. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/can-my-credit-card-company-change-the-terms-of-my-account-en-70/?utm_source=openai))

    When a no-fee card may be the better choice

    Under this comparison method, favor a no-fee candidate when the paid card wins only with optimistic assumptions. That includes counting every available credit, valuing rewards at a redemption you are unlikely to make, or assigning large amounts to perks you would not otherwise buy.

    Travel frequency alone should not decide the outcome. One planned trip could use a valuable benefit, while several trips might offer little opportunity to use a particular card’s perks. Compare your itinerary and spending with the actual benefit rules.

    If you expect to carry a balance, prioritize borrowing cost. The CFPB’s explanation of credit card grace periods notes that, when an applicable grace period is available and you are not carrying a balance, paying in full by the due date can avoid interest on new purchases. Losing the grace period can cause new purchases to accrue interest as well. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47/?intcmp=NoOff_consumerfinance_blog_blog-post__text-content_ext&utm_source=openai))

    Practical steps before applying or renewing

    1. Choose a baseline. Identify a no-fee card you would realistically use.
    2. Build an annual worksheet. Use the same purchase budget and planned trips for every candidate.
    3. Read the disclosures. Record the annual fee, APR, transaction fees, earning rules, and benefit restrictions.
    4. Separate the welcome bonus. Produce a first-year estimate and a recurring-year estimate.
    5. Stress-test the result. Remove uncertain credits and reduce expected redemption value.
    6. Review actual use before renewal. Compare benefits received with your original estimate.

    This process follows the CFPB’s broader recommendation to compare card costs and terms when choosing an account. A budgeting calculator or simple spreadsheet is sufficient; elaborate points tracking is optional. ([files.consumerfinance.gov](https://files.consumerfinance.gov/f/documents/cfpb_adult-fin-ed_how-to-find-the-best-credit-card.pdf?utm_source=openai))

    If the fee no longer works, ask the issuer whether a cheaper product change is available and how it would affect rewards. Before closing an account, consider available credit: the CFPB explains that closure can increase credit utilization and potentially lower a score, depending on the overall credit profile. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/slug-en-1231/?utm_source=openai))

    Keep the card decision within your financial priorities

    Set a time budget for comparing cards alongside other financial decisions. Your review might also include checking account fees, high yield savings accounts, or personal loans and debt consolidation. Compare those products on their own costs and suitability rather than allowing a travel bonus to determine the choice.

    Likewise, keep mortgage rate comparison, car insurance and home insurance reviews, retirement accounts and IRAs, and credit score improvement on your broader checklist. The suggested priority is practical: resolve an immediate borrowing or budgeting problem before spending hours optimizing optional travel perks.

    Questions and answers

    Are travel credit cards worth the annual fee for occasional travelers?

    Possibly. Use the annual worksheet to test whether benefits on your planned trips, plus incremental rewards, exceed the fee. There is no universal minimum number of trips.

    Should I subtract every advertised credit from the fee?

    No. In this method, subtract only the value of credits you expect to use for planned purchases, after accounting for additional costs.

    Does a welcome bonus make the card worth keeping?

    It can improve the first-year calculation. Evaluate renewal separately, excluding a bonus you will not receive again.

    Will canceling a travel card hurt my credit?

    It can, because losing available credit may increase utilization. The effect varies; an annual fee that outweighs benefits can still be a valid reason to close an account. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/slug-en-1231/?utm_source=openai))

    Comparison limits and informational disclaimer

    This article provides a decision framework, not an exhaustive ranking or a test of individual card performance. Illustrative figures are assumptions. Published awards reflect their stated dates and methodologies; current issuer terms, eligibility, and your own usage should determine the final calculation.

    This content is general financial information, not personalized financial advice. Review the issuer’s current rates, fees, rewards terms, and benefit guides before applying or renewing, and borrow only within a realistic repayment plan.

  • Cash Back vs Travel Rewards: Which Is Better for Your Budget?

    Cash Back vs Travel Rewards: Which Is Better for Your Budget?

    When comparing cash back vs travel rewards, which is better depends on how you spend, how you redeem rewards, and what the card costs. Cash back is a practical starting point if you want straightforward savings. Travel rewards deserve consideration when you have specific trips planned and can use the benefits without increasing your spending. Chase’s comparison identifies these same trade-offs: simplicity and flexibility versus travel benefits and potentially higher fees. ([chase.com](https://www.chase.com/personal/credit-cards/education/basics/cash-back-vs-travel-credit-cards?utm_source=openai))

    This guide uses a practical decision rule: choose the card that produces the most usable value after costs. Treat advertised bonuses and premium benefits as inputs to check, rather than reasons to apply.

    What Are Cash Back and Travel Rewards?

    Cash back is a credit card reward calculated as a percentage of eligible spending. Depending on the program, you may redeem it as a statement credit, bank deposit, or another permitted option. Travel rewards are points or miles that can be redeemed toward travel through an issuer or loyalty program. Their dollar value depends on the program and redemption method. Capital One’s guide to cash back and points rewards explains these different reward structures. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/cash-back-vs-point-rewards/))

    The labels can overlap. Some cash back cards technically earn points, while some travel cards allow cash redemptions. Chase explains that eligible Ultimate Rewards cards offer different redemption choices, including cash back, travel, and transfers to selected travel partners. An airline or hotel card may instead earn rewards within that partner’s loyalty program. Check the actual redemption rules before comparing balances. ([chase.com](https://www.chase.com/personal/credit-cards/education/rewards-benefits/cashback-vs-points?utm_source=openai))

    Cash Back vs Travel Rewards at a Glance

    What Are Cash Back and Travel Rewards?: Cash Back vs Travel Rewards: Which Is Better for Your Budget?
    What Are Cash Back and Travel Rewards?: Cash Back vs Travel Rewards: Which Is Better for Your Budget?

    Use this table as a decision framework. It describes what to prioritize when comparing individual offers, rather than assuming every card in a category works the same way.

    Comparison question Favor cash back when… Consider travel rewards when…
    What is your goal? You want savings you can direct toward different expenses. You have a specific travel expense you want to offset.
    How much effort will you spend? You prefer a simple earning and redemption routine. You are willing to compare bookings and redemption options.
    Can you justify the fee? A low-cost card meets your needs. Usable rewards and benefits exceed the additional cost.
    How certain are your plans? Your priorities change or travel is unlikely. Your likely trips fit the program’s available options.
    What should you measure? Dollars redeemed after costs. Travel spending avoided after costs.

    Cash Back: Advantages and Limitations

    Why cash back can be a good fit

    Cash Back vs Travel Rewards at a Glance: Cash Back vs Travel Rewards: Which Is Better for Your Budget?
    Cash Back vs Travel Rewards at a Glance: Cash Back vs Travel Rewards: Which Is Better for Your Budget?

    Cash back has a relatively clear value, and many cards offer low or no annual fees. A flat-rate card can also reduce the need to track different spending categories. These features make cash back worth considering if you want rewards to fit an existing budget with little ongoing management. ([chase.com](https://www.chase.com/personal/credit-cards/education/basics/cash-back-vs-travel-credit-cards?utm_source=openai))

    For your comparison, give flexibility a practical purpose. You might assign redeemed cash to groceries, an emergency fund, or a future vacation. If the program permits bank deposits, consider directing those deposits toward a named savings goal. This keeps rewards connected to your priorities instead of treating them as permission for extra purchases.

    Where cash back needs closer inspection

    A cash back card’s headline rate may apply only to selected categories or a limited amount of spending. Money’s best credit cards comparison illustrates why category caps, annual fees, and the rate on other purchases all matter. Its accessible page contains dated offers, so use those structures as examples and confirm current terms with the issuer. ([money.com](https://money.com/best-credit-cards-overall/?amp=true))

    Before choosing, write down the eligible categories, any activation requirements, spending caps, and redemption conditions. Then estimate your return across your entire budget. A strong grocery rate should not determine the decision if most of your eligible spending happens elsewhere.

    Travel Rewards: Advantages and Limitations

    Why travel rewards can be worthwhile

    Travel cards can offer benefits such as lounge access, checked-bag allowances, travel credits, or certain travel protections. Availability depends on the particular card. These benefits can support a travel card’s value when they match trips and services you would otherwise pay for. ([chase.com](https://www.chase.com/personal/credit-cards/education/basics/cash-back-vs-travel-credit-cards?utm_source=openai))

    Redemption flexibility also varies. For example, Capital One’s explanation of earning and redeeming miles describes travel bookings, eligible travel purchase redemptions, and transfers to participating loyalty programs. Those are different routes to using rewards, so compare the option you expect to use rather than assuming every redemption has identical value. ([capitalone.com](https://www.capitalone.com/learn-grow/money-management/ways-to-redeem-venture-miles/))

    Why advertised value may not become personal savings

    The Consumer Financial Protection Bureau has documented complaints about rewards devaluation, limited redemption opportunities, and confusing conditions. Its report on credit card rewards frustrations is a useful reminder that earning points and successfully using them are separate steps. ([consumerfinance.gov](https://www.consumerfinance.gov/archive/newsroom/cfpb-report-highlights-consumer-frustrations-with-credit-card-rewards-programs/?utm_source=openai))

    Use a conservative personal valuation. If you would normally book an inexpensive hotel, do not automatically count a luxury hotel redemption at its full advertised room price. Ask how much spending the redemption actually replaces. Also assign little or no value to benefits you would not buy or use.

    Before transferring points or booking, check availability, transfer conditions, taxes, cancellation rules, and the full cash alternative. Treat these as a booking checklist, especially when your dates or destination are fixed.

    How to Compare Rewards Using Your Own Numbers

    Calculate annual net value

    Use this comparison formula:

    Estimated annual net value = rewards you expect to redeem + benefits you would otherwise purchase − annual fee − additional costs.

    Additional costs should include any interest, transaction fees, booking charges, and extra spending caused by pursuing rewards. For a repeatable comparison, calculate ongoing value separately from any first-year welcome bonus.

    Here is a hypothetical example, not a current card offer. Assume $20,000 in annual eligible spending and no interest charges:

    • Cash back option: A hypothetical 2% return with no annual fee produces $400.
    • Travel option: A hypothetical two points per dollar produces 40,000 points. At an assumed realized value of one cent per point, that equals $400. After a hypothetical $100 annual fee, net value is $300.
    • Higher-value travel scenario: If those same points actually replace $600 of planned travel spending, net value becomes $500 after the fee.

    The travel option wins only in the higher-value scenario under these assumptions. This example intentionally excludes benefits and bonuses to isolate the effect of redemption value. Add your own usable benefits and costs before making a decision.

    Estimate the value of a specific redemption

    For a simple booking comparison, use:

    Approximate cents per point = (comparable cash price − cash charges required for the award) ÷ points required × 100.

    Suppose a hypothetical flight costs $350, or 25,000 points plus $50. The calculation is ($350 − $50) ÷ 25,000 × 100, giving 1.2 cents per point. This is a simplified estimate; differences in cancellation terms, rewards earned on a paid booking, and other benefits can affect the comparison.

    Use the price of a flight you would reasonably book. If a suitable alternative costs less, calculate against that alternative as well. The aim is to estimate savings you can use.

    Seven Practical Steps Before Choosing a Card

    1. Start with repayment capacity. If you expect to carry debt, compare borrowing costs before rewards. The CFPB explains that avoiding purchase interest generally requires an applicable grace period and payment in full by the due date. Losing that grace period can also expose new purchases to interest. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/what-is-a-grace-period-for-a-credit-card-en-47/?intcmp=NoOff_consumerfinance_blog_blog-post__text-content_ext&utm_source=openai))
    2. Review actual spending. Use recent statements or budgeting calculators and tools to estimate groceries, dining, transportation, travel, and other eligible purchases. Exclude spending you would add solely to earn rewards.
    3. Choose a realistic redemption goal. Write down either a cash amount you want to save or a trip you expect to take. For travel, identify likely dates, destinations, and acceptable alternatives.
    4. Compare complete terms. Record the annual fee, purchase APR, category rules, redemption options, and relevant transaction fees. Confirm the offer directly with the issuer before applying.
    5. Calculate ongoing and first-year value separately. Include a welcome bonus only if its spending requirement fits purchases already in your budget. Repeat the calculation without the bonus.
    6. Test a disappointing year. Assume you travel less, miss a benefit, or redeem points for less than expected. Decide whether the card still makes sense under that scenario.
    7. Review the result annually. Compare rewards actually redeemed with costs actually paid. Use that record when deciding whether to keep the card, ask about another product, or change your spending approach.

    How to Use Best Credit Card Lists Responsibly

    Published rankings can help build a shortlist, but their category winners answer different questions. In its January 7, 2026 Best-Of Awards announcement, NerdWallet named Wells Fargo Active Cash its best all-purpose cash back card and Chase Sapphire Preferred its best all-purpose travel rewards card. Those are dated editorial awards, not guarantees of suitability or approval. ([investors.nerdwallet.com](https://investors.nerdwallet.com/news-releases/news-release-details/nerdwallet-announces-its-2026-best-awards-winners?utm_source=aiseotracker.com))

    For additional research, consult Yahoo Finance’s best credit card article. That specific article could not be retrieved for this review, so no individual recommendation here relies on its contents. Yahoo Finance’s accessible credit card hub states that its ratings use rubrics considering benefits, fees, issuer information, and cardholder agreements. ([finance.yahoo.com](https://finance.yahoo.com/personal-finance/credit-cards/?utm_source=openai))

    This article’s methodology compares normal spending, realistic redemptions, usable benefits, and total costs. It does not rank every available card, predict approval, or assign one universal value to travel points. Money and NerdWallet provide category context; issuer explanations and CFPB guidance support the discussion of reward mechanics and risks.

    Fit Rewards Into Your Wider Financial Plan

    Keep a rewards comparison alongside your other financial decisions. When reviewing high yield savings accounts, checking account fees, or other banking products, compare those products on their own merits. Avoid accepting an unsuitable account merely to support a card strategy.

    If debt repayment is your priority, evaluate personal loans and debt consolidation options using total repayment cost, fees, and affordability. Apply the same discipline to mortgage rate comparisons and car or home insurance: compare complete costs and relevant terms before focusing on small rewards differences. Give retirement accounts and IRAs their own planning process.

    Credit score improvement also deserves separate attention. The CFPB identifies payment history, balances relative to available credit, and recent credit activity among relevant factors. It recommends paying on time, keeping balances low, and applying only for credit you need. Collecting rewards does not replace those habits. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/credit-reports-and-scores/understand-your-credit-score/?utm_source=openai))

    Questions and Answers

    Which is better for someone who rarely travels?

    Start your comparison with cash back. Then consider a travel card only if you can identify a realistic redemption or usable benefit that produces greater net value. Do not assume an occasional trip automatically justifies an annual fee.

    Can I use both types of cards?

    Consider a two-card approach only after calculating the benefit of each card separately. Set a minimum dollar improvement that would make the additional account worth managing. Keep the arrangement simple enough to follow consistently.

    Do I need to carry a balance to earn a good credit score?

    No. The CFPB explicitly states that carrying a credit card balance is unnecessary for a good score. Paying on time and managing the amount of available credit you use are more relevant considerations. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/how-do-i-get-and-keep-a-good-credit-score-en-318/?utm_source=openai))

    Are travel points guaranteed to retain their value?

    No. Rewards programs can change, and the CFPB has documented consumer complaints involving devaluations and redemption restrictions. Base your decision on a usable plan and review program terms before redeeming. ([consumerfinance.gov](https://www.consumerfinance.gov/archive/newsroom/cfpb-report-highlights-consumer-frustrations-with-credit-card-rewards-programs/?utm_source=openai))

    Informational disclaimer: This article provides general education for U.S. consumers, not personalized financial advice. Card offers, fees, eligibility, and rewards terms can change. Verify current issuer disclosures and choose only spending and payments your budget can support.

  • How to Review a Loan Amortization Schedule: A Practical Guide for Comparing Borrowing Costs

    How to Review a Loan Amortization Schedule: A Practical Guide for Comparing Borrowing Costs

    Knowing how to review a loan amortization schedule can make personal finance comparisons more accurate. A schedule shows how each payment is divided between principal and interest, how the balance changes over time, and how much the loan is expected to cost if you follow the original repayment plan.

    This information is useful when comparing personal loans, debt-consolidation loans, auto loans, and mortgages. A loan with a lower monthly payment is not necessarily cheaper overall, and a lower advertised interest rate may not produce the lowest total cost after fees, loan length, or optional features are considered.

    What Is a Loan Amortization Schedule?

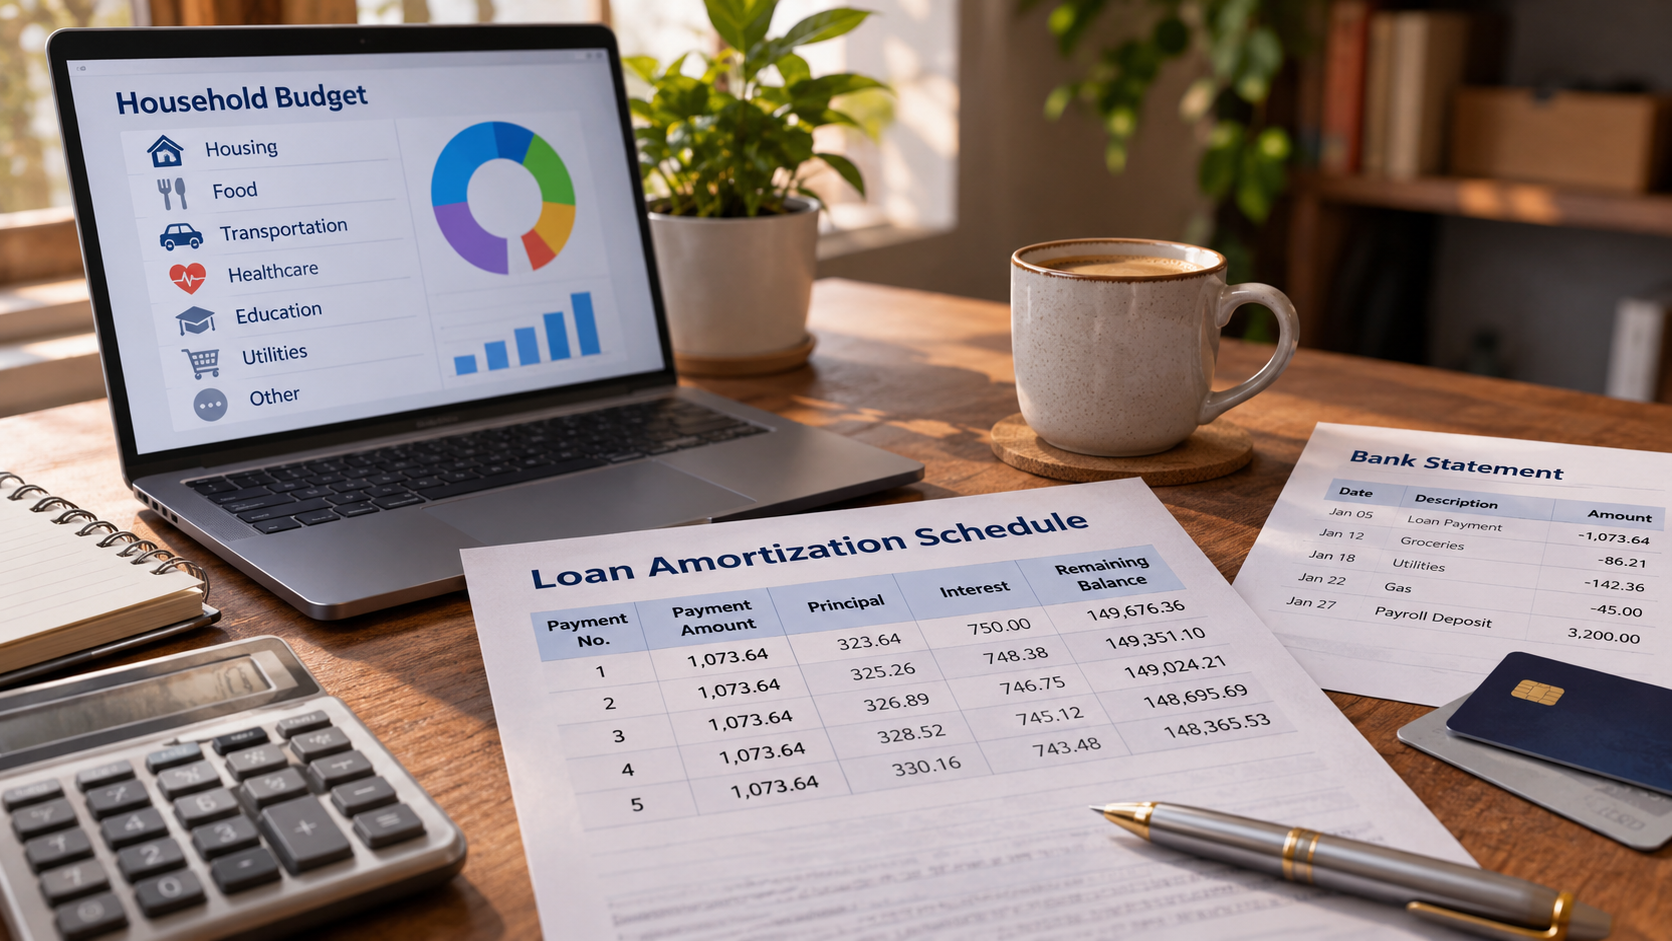
    A loan amortization schedule is a table that projects the payment activity of an installment loan. Typical columns include the payment number, scheduled payment, principal paid, interest paid, fees or extra charges where applicable, remaining balance, and sometimes the loan’s annual percentage rate or effective cost.

    For a fully amortizing fixed-rate loan, the scheduled payment is usually the same each period, but the allocation changes. Early payments generally contain more interest because interest is calculated using the larger opening balance. As the balance declines, the interest portion typically falls and the principal portion rises. By the final scheduled payment, the balance should reach zero or a small rounding adjustment.

    Amortization schedules are different from statements for revolving credit, such as most credit cards. Credit cards usually have variable balances, changing interest charges, and minimum-payment formulas rather than a fixed payoff table. They are also different from an interest-only loan, balloon loan, or adjustable-rate mortgage, where the balance may not decline in the same way throughout the term.

    Why Review the Schedule Before Accepting a Loan?

    What Is a Loan Amortization Schedule?: How to Review a Loan Amortization Schedule: A Practical Guide for Comparing Borro
    What Is a Loan Amortization Schedule?: How to Review a Loan Amortization Schedule: A Practical Guide for Comparing Borro

    The schedule translates loan marketing into a repayment timeline. It can help you answer practical questions:

    • How much will be paid in total if every scheduled payment is made?
    • How quickly does the balance decline?
    • How much interest is paid during the first year compared with later years?
    • What happens if an extra payment is applied to principal?
    • Will a longer term make the payment easier but increase the total cost?
    • Does the schedule match the lender’s offer and your understanding of the loan?

    Reviewing the schedule also creates a common basis for comparing loans. For example, you can compare two personal loans using the same amount borrowed and a similar payoff date instead of focusing only on the monthly payment.

    How to Review a Loan Amortization Schedule Step by Step

    1. Confirm the basic loan assumptions

    Why Review the Schedule Before Accepting a Loan?: How to Review a Loan Amortization Schedule: A Practical Guide for Comp
    Why Review the Schedule Before Accepting a Loan?: How to Review a Loan Amortization Schedule: A Practical Guide for Comp

    Start by checking the amount financed, interest rate, annual percentage rate, term, payment frequency, first payment date, and maturity date. Confirm whether the schedule assumes monthly, biweekly, or another payment frequency. A payment frequency can affect both timing and total interest.

    Check whether the amount shown is the amount you receive or the amount financed after fees. An origination fee may be deducted from the money sent to you while interest is still calculated on the full amount financed. For a mortgage or auto loan, the financed amount may also include points, taxes, insurance, warranties, or other products.

    2. Find the scheduled payment

    Locate the regular payment amount and determine whether it includes anything beyond principal and interest. Mortgage payments often include escrow for property taxes and homeowners insurance, while an auto loan payment normally does not include car insurance. A lender’s total payment quote may therefore differ from the payment shown in the amortization table.

    Ask whether the payment is fixed for the entire term. A fixed-rate loan generally has a stable principal-and-interest payment, while an adjustable-rate mortgage or variable-rate loan may be based on assumptions that change later. If the loan has a balloon payment, deferred interest, or an interest-only period, the schedule may not represent a simple fully amortizing loan.

    3. Read the interest and principal columns together

    For each row, compare the interest amount with the principal amount. The interest amount is usually based on the outstanding balance and the applicable periodic rate. The principal amount is the portion that reduces the balance. The scheduled payment should generally equal the principal and interest components, plus any listed charges.

    A high interest share at the start of a long loan is not automatically an error. It reflects the fact that interest is charged while the balance is largest. However, an unexpectedly high amount may indicate that you are looking at a different rate, term, payment frequency, or financed amount than you intended.

    4. Track the remaining balance

    Review the balance after several milestones, such as the first payment, the end of the first year, the halfway point, and the final scheduled payment. This shows how quickly the debt is declining. On a long mortgage, the balance can decline slowly at first even when payments are made on time.

    Compare the projected balance with your goal. If you plan to sell a home, refinance, trade in a vehicle, or consolidate debt later, the remaining balance helps estimate how much equity or payoff funding may be available. The actual payoff amount can differ from the schedule because of daily interest, fees, payment timing, or other contract terms.

    5. Calculate the scheduled total cost

    Multiply the scheduled payment by the number of payments, then add relevant upfront and ongoing charges. Subtract the amount actually received if you are measuring the cost of obtaining usable funds. This gives you a clearer comparison than the payment alone.

    Do not confuse the interest total shown in a schedule with the loan’s complete cost. The schedule may exclude origination charges, application fees, late fees, prepaid interest, mortgage points, insurance, taxes, or optional products. The annual percentage rate is designed to reflect certain interest and credit costs, but its treatment depends on the product and the assumptions used.

    6. Check the final row and rounding

    The last row should normally show a zero balance, subject to rounding. If the final payment is much larger or smaller than the regular payment, investigate whether the loan has a balloon payment, deferred charges, an irregular first payment, or a schedule error.

    Small differences can result from rounding each payment to cents. A lender’s payoff quote is the authoritative figure for closing an account, not a home-made spreadsheet estimate.

    7. Test an extra-payment scenario

    If you may pay more than required, ask how additional money is applied. A payment can be directed to accrued interest, fees, or principal. To reduce interest, extra funds generally need to be applied to principal after required amounts are satisfied, but your contract and lender’s procedures control.

    Use a calculator or spreadsheet to model an extra monthly amount, an annual lump sum, or a one-time payment. Compare the new payoff date and interest total with the original schedule. Also check for a prepayment penalty, minimum extra-payment amount, or requirement to request a principal-only application.

    Key Formulas and a Simple Example

    For a standard fixed-rate loan, periodic interest can be approximated as:

    Periodic interest = opening balance × periodic interest rate

    The principal portion is generally:

    Principal paid = scheduled principal-and-interest payment − periodic interest

    Suppose a borrower has a fixed-rate installment loan with a regular payment of $400. In one month, $120 is allocated to interest and $280 to principal. The balance therefore falls by $280, assuming there are no additional fees or adjustments. In a later month, the payment might still be $400, but the interest portion could be lower and the principal portion higher because the balance has declined.

    This example explains the direction of the changes but does not estimate the cost of any particular loan. Use the lender’s disclosed terms or a reputable calculator for a real comparison.

    How to Compare Two Amortization Schedules

    When comparing loans, hold as many assumptions constant as possible. Compare the same amount borrowed, similar repayment terms, and the same payment frequency. Then examine:

    • APR: This can provide a broader cost comparison than the interest rate alone, subject to the disclosures and assumptions for the product.
    • Total scheduled payments: This shows the amount paid under the original schedule, before considering possible changes.
    • Fees: Include origination fees, points, broker charges, closing costs, and required add-on products where relevant.
    • Balance reduction: A loan with a lower payment may leave a higher balance at a particular date.
    • Flexibility: Review prepayment rules, rate changes, payment holidays, and refinancing conditions.
    • Risk: Consider whether a variable rate, balloon payment, secured collateral, or late-payment consequences fit your finances.

    A longer term often lowers the required monthly payment but may increase total interest because the balance remains outstanding for more periods. A shorter term commonly has a higher required payment but may reduce total interest. Neither option is universally best; the appropriate choice depends on cash flow, emergency savings, income stability, and other obligations.

    Pros and Cons of Using an Amortization Schedule

    Advantages

    • It makes the principal and interest allocation visible.
    • It helps compare total repayment costs instead of monthly payments alone.
    • It supports planning for refinancing, selling, or paying off a debt.
    • It can reveal whether an extra-payment strategy might shorten the term.
    • It provides a way to check whether a lender’s explanation matches the contract.

    Limitations

    • A schedule is a projection and may not include every fee or future adjustment.
    • Variable rates can make later rows uncertain.
    • Actual payoff figures may include accrued daily interest and transaction charges.
    • Escrow, taxes, insurance, and maintenance are often outside the principal-and-interest schedule.
    • Prepayment modeling is unreliable if the lender applies extra money differently than expected.
    • Rounding and payment-date differences can produce small discrepancies.

    Connections to Other Personal Finance Comparisons

    Loan analysis works best as part of a broader financial review. If you are considering debt consolidation, compare the new loan’s total cost with the existing debts and avoid treating a lower payment as proof of savings. A consolidation loan can extend repayment and may put secured assets at risk if it is backed by collateral.

    Reviewing your checking account fees and maintaining an adequate emergency reserve can help prevent missed loan payments. High-yield savings accounts may offer a place for short-term reserves, but compare the account’s rate, access rules, fees, and variable-rate terms rather than assuming the highest advertised yield will remain available.

    Credit cards and rewards should be evaluated separately from installment loans. Rewards do not offset interest if a balance is carried at a high rate. Credit score improvement may make refinancing more affordable, but applying for credit solely to chase a small rate change can have costs and should be assessed carefully.

    For mortgages, compare rates, APR, points, closing costs, escrow assumptions, and the amortization schedule. For car ownership, evaluate the loan alongside car insurance, maintenance, and depreciation. Similar comparison principles apply to home insurance, retirement accounts and IRAs, and budgeting calculators: consider total cost, restrictions, risk, and how the product fits the full plan.

    Reliable Sources and Comparison Methodology

    This guide uses a general comparison methodology: identify the amount financed, rate structure, term, payment frequency, fees, total scheduled payments, projected balance, and risks; then compare products using consistent assumptions. Calculations should be checked against the written loan estimate, promissory note, account agreement, or closing disclosure.

    The Consumer Financial Protection Bureau’s Ask CFPB provides consumer guidance on mortgages, credit, loans, and repayment issues. The Federal Trade Commission’s Credit, Loans, and Debt resources discuss borrowing and debt-related consumer concerns. These sources are useful starting points, but your loan documents and lender payoff statement control the terms of your specific account.

    Concise Q&A

    Does an amortization schedule show the exact payoff amount?

    Not always. It usually shows projected scheduled payments. Request a current payoff quote to account for accrued interest, fees, payment timing, and lender-specific adjustments.

    Why does the interest portion fall over time?

    Interest is generally calculated from the outstanding principal balance. As principal is paid down, the interest calculated for later periods usually declines.

    Is a lower monthly payment always better?

    No. A lower payment may result from a longer term, a higher total interest cost, a variable rate, or a balloon balance. Compare total cost and remaining balance as well as affordability.

    Should extra payments be made automatically?

    Only after checking your emergency savings, higher-cost debt, contract terms, and lender procedures. Confirm that extra money is applied to principal and that no prepayment penalty applies.

    Final Checklist

    • Confirm the amount financed, rate, term, and payment frequency.
    • Separate principal and interest from taxes, insurance, and other charges.
    • Check the opening balance, milestone balances, and final balance.
    • Compare total scheduled payments and all known fees.
    • Review rate changes, balloon payments, late fees, and prepayment rules.
    • Request clarification when the schedule does not match the contract.
    • Use a current payoff quote before refinancing or paying off the loan.

    Informational disclaimer: This article is for general educational purposes and is not financial, legal, tax, or lending advice. Loan terms vary by lender and borrower. Before signing, changing, or paying off a loan, review the official documents and consider consulting a qualified financial professional.

  • How Overdraft Protection Fees Are Calculated: A Practical Guide

    How Overdraft Protection Fees Are Calculated: A Practical Guide

    Understanding how overdraft protection fees are calculated starts with identifying which service your checking account uses. A transfer from savings, an advance from a credit line, and a bank paying a transaction into a negative balance can produce different charges. The Consumer Financial Protection Bureau (CFPB) distinguishes linked-account protection from standard overdraft coverage because their costs and operating rules differ. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/bank-accounts/know-your-overdraft-options/?utm_source=openai))

    This guide explains the main calculation methods for U.S. consumer accounts, provides hypothetical examples, and offers a framework for comparing banking products. Every dollar amount in the worked examples is illustrative, not a quoted bank price.

    What Is an Overdraft Protection Fee?

    An overdraft protection fee is a charge associated with moving or advancing money from an eligible linked account to cover a checking-account shortfall. Depending on the arrangement, the backup source can be savings, another checking account, a credit card, or a line of credit. Some transfers carry no transfer fee, while credit-based protection can involve interest or other borrowing charges. ([usbank.com](https://www.usbank.com/customer-service/knowledge-base/KB0171700.html?utm_source=openai))

    Terminology varies, so read the service description rather than relying on its name. Three categories matter:

    • Linked-deposit protection: Money moves from an eligible deposit account you own.
    • Linked-credit protection: Borrowed money covers the shortfall.
    • Standard overdraft coverage: The bank pays an eligible transaction despite insufficient funds, leaving the checking account overdrawn.

    U.S. Bank explicitly distinguishes linked-account protection from overdraft coverage. That distinction helps you identify the correct fee schedule before calculating costs. ([usbank.com](https://www.usbank.com/customer-service/knowledge-base/KB0069879.html?utm_source=openai))

    A nonsufficient funds, or NSF, fee is different: it may apply when a payment is returned unpaid rather than covered. Whether your institution charges it depends on its policy, and the payee may impose a separate returned-payment charge. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/what-can-i-do-if-my-bank-charged-me-a-fee-for-overdrawing-my-account-en-1037/?utm_source=openai))

    How Overdraft Protection Fees Are Calculated

    What Is an Overdraft Protection Fee?: How Overdraft Protection Fees Are Calculated: A Practical Guide
    What Is an Overdraft Protection Fee?: How Overdraft Protection Fees Are Calculated: A Practical Guide

    Use this worksheet structure: total service cost = applicable transfer or advance fees + borrowing interest + other applicable charges − refunds or waivers. Enter only charges that actually apply to the service used. Keep the amount transferred or borrowed separate from the cost of providing it.

    1. Linked-account transfer fees

    Start with the transfer fee, then determine what triggers it. Read whether the agreement charges per transfer, per day of use, or under another defined rule. Do not assume every purchase creates a separate transfer. For example, U.S. Bank describes transfers that can cover a shortfall using specified increments, rather than simply matching each purchase amount. ([usbank.com](https://www.usbank.com/bank-accounts/checking-accounts/checking-customer-resources/overdraft-protection.html))

    For a hypothetical plan charging $5 per billable transfer, three billable transfers would cost 3 × $5 = $15. If another hypothetical plan charges $5 once per day of use, those transfers occurring on one day would cost $5. This example shows why the billing unit matters as much as the advertised fee.

    A transfer fee is not inevitable. Bank of America states that Balance Connect has no transfer fee, although linked credit accounts can generate interest and other charges under their agreements. A zero transfer fee therefore does not necessarily mean zero borrowing cost. ([bankofamerica.com](https://www.bankofamerica.com/deposits/resources/deposit-agreements.go?utm_source=openai))

    2. Interest on an overdraft credit line

    How Overdraft Protection Fees Are Calculated: How Overdraft Protection Fees Are Calculated: A Practical Guide
    How Overdraft Protection Fees Are Calculated: How Overdraft Protection Fees Are Calculated: A Practical Guide

    Credit-based protection requires an interest calculation as well as a fee calculation. U.S. Bank’s Reserve Line disclosures, for example, state that interest begins on the date of an advance. Use your own agreement’s daily periodic rate, balance method, and repayment rules rather than substituting another lender’s terms. ([usbank.com](https://www.usbank.com/content/dam/usbank/documents/pdf/loans-and-lines/ReserveLineDisclosures.pdf?utm_source=openai))

    For a simplified example with a constant balance, no compounding, and an assumed 365-day basis:

    Estimated interest = borrowed balance × APR ÷ 365 × days outstanding.

    Suppose a hypothetical credit line advances $200 at 18% APR, and the balance remains unchanged for 10 days. Estimated interest is $200 × 0.18 ÷ 365 × 10 = $0.99, rounded to cents. With an assumed $5 advance fee, the service cost would be approximately $5.99. The $200 principal must also be repaid.

    If balances change, calculate each day’s interest using the applicable balance and add the results. Actual statement charges can differ from this simplified illustration because of the agreement’s calculation method, rounding, payment timing, and fees included in the balance.

    3. Standard overdraft fees

    Standard overdraft coverage can charge by the paid transaction instead of by a backup transfer. The FDIC explains that overdraft charges vary by institution and that some institutions also impose charges when an account remains overdrawn. These are separate cost categories to check. ([fdic.gov](https://www.fdic.gov/consumer-resource-center/2021-12/overdraft-and-account-fees?utm_source=openai))

    For a hypothetical account charging $25 per eligible paid overdraft, with a two-fee daily cap, three otherwise chargeable transactions on the same day would produce min(3, 2) × $25 = $50 in transaction-based overdraft fees. This assumes all three meet the account’s charging conditions and no waiver applies.

    The cap in that example limits those transaction fees only. In a real comparison, confirm which charges a cap covers and whether the account has balance thresholds or other exceptions. Regulation E requires covered opt-in notices to disclose applicable fees and daily fee limits, including when there is no limit. ([consumerfinance.gov](https://www.consumerfinance.gov/rules-policy/regulations/1005/17/))

    Why the Same Purchase Can Produce Different Costs

    Available balance versus ledger balance

    Your ledger balance generally reflects posted transactions. Your available balance also accounts for factors such as debit-card authorization holds and deposits that are not yet available. The Office of the Comptroller of the Currency (OCC) explains that these differences matter when institutions assess overdrafts. ([occ.gov](https://www.occ.gov/news-issuances/bulletins/2023/bulletin-2023-12.html?utm_source=openai))

    For illustration, a $120 ledger balance with a $50 authorization hold leaves $70 available, assuming no other adjustments. A new $90 payment creates a $20 available-balance shortfall. Whether that leads to a transfer, a decline, or a paid overdraft depends on the account’s service settings and terms.

    Posting times, thresholds, and grace periods

    Transactions do not necessarily update your balance immediately or in the order you expect. The CFPB recommends understanding when deposits become available and tracking payments that have not yet posted. A deposit visible in your transaction history may not yet be available to cover spending. ([consumerfinance.gov](https://www.consumerfinance.gov/consumer-tools/bank-accounts/know-your-overdraft-options/?utm_source=openai))

    Some accounts also have fee exceptions or opportunities to restore the balance. U.S. Bank’s overdraft coverage information, for example, describes exceptions tied to transaction size and the negative balance at the end of the business day. Read the specific account disclosure for qualifying amounts and deadlines. ([usbank.com](https://www.usbank.com/customer-service/knowledge-base/KB0259366.html?utm_source=openai))

    Insufficient backup funds

    Protection has limits. If a linked credit line lacks sufficient available credit, overdraft fees may still occur. U.S. Bank discloses this limitation for its Reserve Line. When comparing plans, examine what happens after the backup source is exhausted, not just what happens when protection succeeds. ([usbank.com](https://www.usbank.com/loans-credit-lines/personal-loans-and-lines-of-credit/reserve-line-of-credit.html?utm_source=openai))

    Practical Steps to Check Your Charges

    1. Identify the transaction and service. Record whether the payment was covered by a deposit transfer, a credit advance, or standard overdraft coverage.
    2. Find the relevant agreement. Gather the checking fee schedule, linked-account terms, and any credit agreement. Use the versions applicable when the charge occurred.
    3. Build a timeline. List payments, holds, available deposits, transfers, and repayment dates. Distinguish authorization from final posting.
    4. Count billable events. Apply the agreement’s transfer, transaction, or daily charging rule. Do not substitute the number of purchases for the number of chargeable events.
    5. Calculate borrowing costs. Use the actual amount advanced, applicable rate, and days outstanding. Include only fees supported by the agreement.
    6. Apply exceptions. Check fee caps, qualifying balance thresholds, account benefits, grace periods, and posted refunds.
    7. Request an explanation. If your calculation differs from the statement, ask the institution to identify the transaction, balance, timing, and contract provision behind each charge.

    These steps provide an audit worksheet, not a determination that a disputed charge is valid. The CFPB says consumers who believe a debit overdraft fee was charged without authorization can submit a complaint. Preserve statements and the bank’s explanation when pursuing a dispute. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/what-can-i-do-if-my-bank-charged-me-a-fee-for-overdrawing-my-account-en-1037/?utm_source=openai))

    How to Compare Overdraft Protection Options

    Use the same hypothetical shortfall and repayment date for each account. Then repeat the calculation under a second scenario involving several payments. This comparison method separates differences in pricing from differences in how frequently you use the service.

    Option What to calculate What to verify
    Linked savings or checking Billable transfers multiplied by the applicable fee Eligible accounts, available funds, transfer rules
    Linked credit Advance fees plus interest and other applicable charges Rate, advance amount, repayment terms, available credit
    Standard coverage Eligible paid-item fees after limits and waivers Covered payments, daily caps, balance exceptions

    For each option, add the checking account’s monthly maintenance costs to a separate annual comparison. Ask whether meeting a waiver requires a balance or deposit pattern you can realistically maintain. Avoid selecting an account solely because one overdraft-related fee is lower.

    If comparing high yield savings accounts as potential backup sources, ask whether each account can actually participate in automatic protection. Likewise, if considering a credit card, compare its overdraft-advance terms separately from purchase rewards. U.S. Bank notes that credit products used for protection may have annual fees, cash-advance fees, and interest charges. ([usbank.com](https://www.usbank.com/customer-service/knowledge-base/KB0171700.html?utm_source=openai))

    Neutral Pros, Cons, and Limitations

    Potential advantages: A funded linked account can help complete payments and avoid a negative checking balance. A plan without transfer fees may address an occasional timing mismatch without a transfer charge. Bank of America’s Balance Connect description illustrates these features, subject to account eligibility and available backup funds. ([promotions.bankofamerica.com](https://promotions.bankofamerica.com/deposits/balanceconnect))

    Potential disadvantages: Savings protection moves money away from its original purpose, while credit protection creates a repayment obligation. Credit-related fees and interest can make repeated use costly. Standard coverage can also involve additional charges for an extended negative balance, depending on the institution. ([usbank.com](https://www.usbank.com/customer-service/knowledge-base/KB0069879.html?utm_source=openai))

    Limitations: Protection does not guarantee that every payment will be approved. Regulation E expressly permits an institution to decline ATM or one-time debit-card overdrafts even after a consumer opts in. Treat coverage as a conditional service when planning essential payments. ([consumerfinance.gov](https://www.consumerfinance.gov/rules-policy/regulations/1005/17/?utm_source=openai))

    For your budget, test whether the problem is occasional payment timing or a recurring gap between income and spending. Consider a bill calendar, low-balance alerts, and a modest checking buffer. If evaluating personal loans or debt consolidation, calculate their full repayment costs separately rather than assuming a larger borrowing commitment solves a small timing problem.

    Concise Questions and Answers

    Are overdraft protection fees a percentage of the shortfall?

    Not necessarily. A plan may charge a transfer fee, while credit protection can add interest based on borrowing. Check the fee structure and credit terms; there is no single calculation that applies to every product. ([usbank.com](https://www.usbank.com/bank-accounts/checking-accounts/checking-customer-resources/overdraft-protection.html))

    Does opting out prevent every overdraft fee?

    No. The federal opt-in requirement concerns fees for standard overdraft service on ATM and one-time debit-card transactions. Checks and recurring electronic payments are treated differently, so opting out is not a blanket protection against every overdraft charge. ([consumerfinance.gov](https://www.consumerfinance.gov/ask-cfpb/what-can-i-do-if-my-bank-charged-me-a-fee-for-overdrawing-my-account-en-1037/?utm_source=openai))

    Is the money transferred from savings itself a fee?

    No. Separate the amount moved from the charge for moving it. For example, if $80 moves between your accounts and a hypothetical $4 transfer fee applies, the service cost is $4. Your savings balance has also decreased by the transferred funds.

    Can an account charge for staying negative?

    Some institutions assess sustained or extended overdraft charges after an account remains negative for a specified period. Check whether your account has such a charge and how its timing is measured. ([consumerfinance.gov](https://www.consumerfinance.gov/data-research/research-reports/data-spotlight-consumer-experiences-with-overdraft-programs/full-report/?utm_source=openai))

    Sources and Comparison Methodology

    This article uses consumer guidance and regulatory materials from the Consumer Financial Protection Bureau, Federal Deposit Insurance Corporation, and Office of the Comptroller of the Currency, alongside official Bank of America and U.S. Bank product disclosures cited above. The comparison framework separates transaction fees, transfer fees, interest, and principal, then applies identical hypothetical scenarios. It does not rank institutions or claim that example prices are market averages.

    This article provides general financial information for U.S. consumers, not personalized financial or legal advice. Verify current account terms and obtain an explanation of disputed charges from your institution before making decisions.

  • Certificate of Deposit Ladder Basics for Beginners: How to Build One

    A certificate of deposit ladder can help savers earn interest on money they do not need all at once while keeping some funds scheduled to become available regularly. It is a way to divide savings among certificates of deposit (CDs) with different maturity dates—not a special account or a guarantee of the best return. Understanding the terms, access rules, and insurance coverage matters before opening one.

    This guide explains certificate of deposit ladder basics for beginners, including how to build a simple ladder, what to compare between banks and credit unions, and when another savings option may fit better. Rates and account terms change, so compare current disclosures before you deposit.

    What is a CD ladder?

    A CD is a deposit account that typically pays a stated interest rate for a set term. In exchange for agreeing to leave the money deposited until maturity, you may earn a different rate than on a bank’s ordinary savings account. Terms can range from short periods to several years. The rate, compounding method, minimum deposit, and early-withdrawal rules depend on the institution and specific CD.

    A CD ladder divides a sum of money among CDs with staggered maturity dates. For example, rather than placing all of your savings in one three-year CD, you could divide it among one-year, two-year, and three-year CDs. When the first CD matures, you can use the money or reinvest it in a new CD. The later CDs then mature in sequence.

    The ladder’s main purpose is to spread out access dates and reduce the need to commit every dollar to one term. It does not eliminate risk: rates may change, and money in an individual CD may be difficult or costly to access before maturity.

    How a CD ladder works

    Imagine you have money set aside for savings goals that are more than a few months away. You divide it into several portions and choose CDs with different terms. Each CD has its own maturity date, and its interest and principal are handled according to the account’s terms. At maturity, you can generally withdraw the funds or choose a new CD.

    Some banks and credit unions automatically renew a CD if you do not act within the notice period after maturity. The renewal may be for a similar term but at the institution’s then-current rate. Read the maturity notice and renewal terms so you know how long you have to make a decision.

    A ladder can be built with equal amounts in each CD, but equal portions are not required. You might keep more in shorter-term CDs if you expect to need cash sooner, for example. The right structure depends on your spending plans, comfort with limited access, and the rates and terms available when you open the accounts.

    Practical steps to build a beginner CD ladder

    1. Keep emergency money accessible

    Before choosing CD terms, separate emergency savings and money needed for near-term bills. A high-yield savings account may offer variable interest while allowing easier withdrawals, subject to the account’s terms. It can be a better home for money you may need unexpectedly than a CD with an early-withdrawal penalty. Do not assume a ladder replaces an emergency fund.

    2. Set a goal and a time horizon

    List when you may need the money: a planned home repair, tuition payment, vehicle purchase, or another goal. Match maturity dates to those needs where possible. Avoid putting money into a term that extends beyond when you expect to use it unless you can tolerate waiting or accept the possible penalty for early withdrawal.

    3. Compare account terms, not just the advertised rate

    Check the annual percentage yield (APY), term, minimum deposit, interest payment schedule, compounding, early-withdrawal penalty, and renewal process. Confirm whether the rate is fixed for the full term and whether the CD is callable, meaning the issuer may be able to end it early under specified conditions. Callable CDs can behave differently from ordinary fixed-term CDs.

    Compare offers from banks and federally insured credit unions using their official disclosures. The APY helps account for compounding, but it does not tell you whether the account suits your access needs. If comparing a CD with a savings account, remember that savings rates can change while a fixed-rate CD generally keeps its stated rate for its term.

    4. Choose the number of rungs and deposit amounts

    A rung is one CD in the ladder. A simple approach might use three or four different terms, but there is no required number. Decide how frequently you want a CD to mature and how much money you can leave committed. A ladder with more rungs can create more frequent decision points, but it may also mean managing more accounts and maturity dates.

    For an illustrative example, a saver could divide $12,000 into three $4,000 deposits, placing one in a one-year CD, one in a two-year CD, and one in a three-year CD. These amounts and terms are only an example, not a recommendation or a rate forecast. After the first year, the one-year CD matures; the saver could withdraw it or put it into a new three-year CD. If the saver repeats that choice when each shorter CD matures, the ladder may eventually have CDs maturing at regular intervals.

    5. Check deposit insurance and ownership details

    Verify that the bank is insured by the Federal Deposit Insurance Corporation (FDIC), or that the credit union has coverage through the National Credit Union Administration (NCUA). Federal deposit insurance applies subject to rules and limits, including how accounts are categorized by ownership. The standard limit is generally $250,000 per depositor, per insured institution, per ownership category. The total across accounts at one institution may matter, not just the balance in one CD. Check the FDIC’s Electronic Deposit Insurance Estimator or the NCUA’s Share Insurance Estimator if your balances approach coverage limits.

    Brokered CDs and CDs held through investment accounts have additional terms to review. Confirm who issued the CD, how it is held, how insurance coverage applies, and what it may cost or take to sell before maturity. A brokered CD may not offer the same early-withdrawal process as a CD opened directly with a bank.

    6. Track maturity dates and make a reinvestment plan

    Record each CD’s issuer, term, APY, maturity date, penalty, and renewal deadline. Set reminders well before maturity. At each decision point, compare the current rate and terms with your needs instead of automatically renewing. You may decide to spend the funds, move them to accessible savings, or buy a new CD with a different term.

    Pros and cons of CD ladders

    Potential benefits

    • Scheduled access: Staggered maturity dates can make portions of savings available at intervals without closing every CD at once.
    • Rate variety: You avoid choosing one term for the entire balance. If rates change, only the CDs being opened or renewed are affected immediately.
    • Predictable terms: A fixed-rate CD generally states its rate and maturity date in advance, which can help with planning.
    • Deposit protection: Eligible deposits at FDIC-insured banks or NCUA-insured credit unions are protected within applicable limits and rules.

    Potential drawbacks

    • Limited access: Taking money out early may trigger a penalty, and some products may not permit early withdrawal in the same way as a standard bank CD.
    • Reinvestment risk: When a CD matures, available rates may be lower than the rate you previously earned.
    • Opportunity cost: If rates rise, money in a fixed-rate CD may earn less than newly available accounts until maturity.
    • Ongoing administration: Multiple accounts mean tracking different terms, notices, and renewal dates.
    • Inflation and taxes: Interest may not keep pace with rising prices, and interest in a taxable account is generally subject to tax rules.

    CD ladder versus a high-yield savings account

    A high-yield savings account may suit money that needs to remain readily accessible. Its rate is usually variable, so the bank can change it. A CD may offer a fixed rate for a selected term, but access can be restricted or penalized before maturity. Some savers use both: accessible savings for emergencies and CDs for money with a clearer timeline. Compare fees, withdrawal terms, insurance, and current APY rather than assuming one option always pays more.

    CD ladder versus paying down debt or investing

    Saving in CDs is not automatically the best use of every dollar. If you carry high-interest debt, compare the cost of that debt with the after-tax return you expect from savings. Paying down a balance can reduce interest costs, but consider whether you need liquid cash and whether a loan has prepayment terms. For longer-term goals, retirement accounts and diversified investments have different risks, tax rules, and time horizons; they are not interchangeable with insured bank deposits.

    Budgeting tools can help estimate when you will need funds and how much to keep liquid. A mortgage rate comparison or insurance comparison may also identify other household costs to review, but those decisions are separate from choosing a CD term. Consider your overall financial plan rather than evaluating a deposit rate in isolation.

    Common mistakes to avoid

    • Locking up emergency cash: Keep money for urgent expenses in an account designed for access.
    • Ignoring the penalty: Read the exact early-withdrawal rule. A penalty can reduce interest and, depending on the terms, may affect principal.
    • Forgetting automatic renewal: Missing a notice window can leave funds in a new term you did not intend to choose.
    • Comparing rates without terms: A higher advertised APY may come with a longer term, a higher minimum, or different access conditions.
    • Overlooking total deposits: Add up eligible deposits at the same institution and check how ownership categories affect insurance coverage.
    • Assuming a ladder always beats savings: Outcomes depend on future rates, taxes, access needs, and the specific products selected.

    Q&A: CD ladder basics for beginners

    How much money do I need to start a CD ladder?

    There is no universal minimum for a ladder. Each institution sets its own CD minimum, and the total needed depends on how many rungs you want. You can start with fewer CDs and add rungs as you save, provided the minimums and terms work for you.

    Are CD ladder returns guaranteed?

    A fixed-rate CD generally specifies its rate for the term, subject to the account agreement and issuer terms. A ladder’s overall future return is not guaranteed because future renewal rates, taxes, and your decisions at maturity can change the result.

    Can I withdraw from a CD before it matures?

    It depends on the product. A traditional bank CD commonly charges an early-withdrawal penalty. Brokered CDs may need to be sold in a secondary market, where the sale price can be higher or lower than the amount invested. Read the specific disclosure before opening an account.

    Should I renew every CD for the longest term?

    Not necessarily. Longer terms may offer different rates, but they also commit funds for longer. Compare current offers and your expected cash needs at each maturity rather than following a fixed rule.

    Sources and comparison approach

    This guide uses product definitions and consumer guidance from the FDIC and the NCUA, including their deposit-insurance information. For a specific decision, compare the current account agreement and rate disclosures from each institution, and use the FDIC and NCUA insurance estimators to review coverage. Product rates and rules can change.

    Informational disclaimer: This article is general educational information, not individualized financial, tax, or legal advice. Consider your cash needs, debt, tax situation, and applicable account terms before making a decision.

  • How to Compare Secured Credit Card Deposit Terms Before You Apply

    A secured credit card can make credit available while the issuer holds a cash deposit as collateral. That deposit is real money you may need for bills or emergencies, so compare more than the minimum amount advertised. Check how the deposit sets your credit limit, when the issuer takes it, what happens if you close the account, and whether other fees make the card costly.

    This guide explains how to compare secured credit card deposit terms, what to confirm in writing, and how to weigh the trade-offs. Card terms vary by issuer and can change, so rely on the offer and agreement for the specific account you are considering.

    What are secured credit card deposit terms?

    Secured credit card deposit terms are the conditions governing the cash collateral you provide to open or maintain a secured card. They cover matters such as the deposit amount, payment method, how the issuer determines your credit limit, where and how long the funds are held, and the circumstances and process for returning them.

    The deposit is not ordinarily a prepaid balance that pays for purchases. You still use the card and make payments under its billing terms. The deposit gives the issuer security if you fail to pay what you owe. Depending on the card agreement, the credit limit may equal the deposit or be set at a different amount. Do not assume the deposit and limit are always identical.

    Why compare deposit terms carefully?

    A deposit can tie up money for as long as the account remains open, including the time needed to process a return after closure or a qualifying account change. Two cards with similar-looking deposits may differ in their minimums, permitted maximums, refund procedures, fees, and rules for increasing a limit. A low opening deposit is not automatically the least expensive choice if the card also has costly fees or other terms that do not suit your needs.

    Deposit terms are only one part of a credit card comparison. Review the annual fee, interest rate, penalty terms, grace period, transaction fees, payment rules, and credit bureau reporting as well. If your goal is to build or rebuild credit, confirm that the issuer reports account activity to the credit bureaus and understand that payments made on time do not guarantee a particular score or score increase.

    Deposit details to compare

    Minimum and maximum deposit

    Find the minimum deposit required to open the account and any stated maximum. The amount you can afford to set aside may differ from the amount needed to qualify for the credit limit you want. Check whether you choose the deposit amount, the issuer assigns it, or approval rules determine the amount. Also confirm whether the stated amount is required at application, after conditional approval, or by a later funding deadline.

    Ask whether an initial deposit is the only way to establish the account or whether the issuer can request additional collateral under specified circumstances. Read the agreement for language about increases, missed payments, or changes to the credit line. Do not rely on a general product description if the account’s formal documents describe a different process.

    How the deposit relates to the credit limit

    Look for the exact rule that connects the deposit to the credit limit. Some products describe a direct relationship; others may set a limit below the deposit or use separate eligibility criteria. Verify the limit you will actually receive rather than estimating it from the amount you plan to deposit.

    A larger deposit may provide more available credit if the issuer’s terms link the two, but it also means more of your cash is committed. It does not make borrowing free. Purchases can accrue interest if you carry a balance, and fees may apply under the agreement. Consider whether you can pay the bill in full and on time, not simply whether you can fund a larger deposit.

    Funding method and timing

    Check which payment methods the issuer accepts and when the deposit must clear. A deposit may be collected during application, after approval, or before the card is issued; the process differs by product. If the issuer uses an authorization hold before collecting the funds, find out when that hold is released and whether a separate transfer follows. Confirm whether a failed or delayed payment affects approval or account opening.

    Use a payment account you control, and allow for processing time. Do not send money through an unexpected link or to a person claiming to represent the issuer. manage to the issuer’s official website yourself or use contact information on verified account documents if you need to confirm a payment request.

    Where the money is held and whether it earns interest

    Read the deposit agreement or ask the issuer how it holds the collateral, whether interest is paid, and whether the funds are kept separate from ordinary payments. Do not assume the deposit is in an interest-bearing account or has the same protections as money in a savings account. The legal and practical treatment depends on the issuer’s arrangement and applicable terms.

    Even if interest is available, compare its terms with the cost of having your cash unavailable. A high-yield savings account may offer access and interest under its own rules, while a secured-card deposit serves as collateral and can be restricted. These products are not interchangeable: compare access, account conditions, and purpose rather than looking only at a quoted rate.

    Refund rules and account closure

    Find out when and how the deposit is returned. The agreement may condition a refund on closing the account, paying the balance, or meeting other requirements. The issuer may first apply the deposit to unpaid amounts, such as an outstanding balance or applicable charges. Confirm whether a refund is sent by electronic transfer, check, or another method, and whether processing time begins only after the account is fully settled.

    Ask whether the issuer may review the account for an upgrade to an unsecured card, and what happens to the deposit if an upgrade is offered. Do not assume that a review is automatic, that an upgrade is guaranteed, or that the deposit is returned while the secured account remains open. Verify the process and any eligibility conditions in the current terms.

    Fees that are separate from the deposit

    A deposit is collateral, not necessarily a fee, but the card may charge fees separately. Review the pricing disclosure for an annual fee and charges for late payments, returned payments, cash advances, foreign transactions, or other services. Also compare the annual percentage rate (APR) and the terms governing interest. A card with a lower deposit can still cost more over time if its fees or borrowing costs are higher.

    Do not treat an advertised deposit amount as the total cost of owning the card. Compare the full pricing disclosure and cardholder agreement, including whether any fee is charged before the deposit is refunded or may be deducted from funds under the contract.

    Practical steps for comparing cards

    1. Set a safe deposit budget. Decide what amount you can leave unavailable without jeopardizing rent, bills, emergency savings, or debt payments. Avoid borrowing money just to fund a deposit unless you have carefully considered the additional cost and repayment risk.
    2. Collect current documents. For each card, save the offer, pricing disclosure, cardholder agreement, and any separate deposit terms. Record when you checked them because terms can change. If a detail is missing, ask the issuer and keep its written response.
    3. Compare the same fields. Note the required minimum and maximum, the deposit-to-limit rule, funding deadline and method, any additional-deposit conditions, interest treatment, refund conditions, and expected refund method. Then compare annual fee, APR, other charges, payment rules, and credit bureau reporting.
    4. Trace the money through a full account lifecycle. Consider what happens at application, opening, ordinary use, a missed payment, an upgrade review, and closure. Identify when the issuer can apply collateral to amounts owed and what steps you must take to request any remaining deposit back.
    5. Check affordability and alternatives. Consider whether a secured card fits your budget and credit goals. Compare it with other cards or financial products only after checking eligibility, fees, access to funds, and credit reporting. A savings account, personal loan, or debit account serves a different purpose and should not be treated as a substitute without considering those differences.
    6. Verify before paying. Confirm that you are on the issuer’s genuine website and that the payment instructions match the offer. If the deposit amount, refund process, or recipient differs from what you expected, pause and contact the issuer using independently verified contact details.

    A simple comparison worksheet

    For each card, write down: required deposit range; deposit amount selected or assigned; expected credit limit; accepted funding methods; deadline to fund; whether the issuer describes an authorization hold; how collateral is held and whether it earns interest; conditions for adding collateral; conditions for a refund or upgrade; how unpaid amounts are handled; refund method and processing steps; annual fee and other charges; APR; and credit bureau reporting.

    Use the same questions for every product. If a term is unclear, mark it as unconfirmed rather than filling the gap with an assumption. A comparison spreadsheet can help, but it does not replace the binding agreement. If a representative explains a term verbally, ask where it appears in the written documents.

    Pros and cons of secured card deposits

    Potential advantages

    • The collateral may make a card available to some applicants who have limited or damaged credit histories, subject to the issuer’s approval standards.
    • A deposit-linked credit limit can make the starting limit easier to understand, if the issuer clearly states the relationship.
    • Responsible use may help establish a payment history if the issuer reports the account to the relevant credit bureaus and the account is managed as agreed.
    • Reviewing deposit and refund conditions can make it easier to plan how the account fits into a broader budget.

    Potential disadvantages

    • The deposit ties up cash that could otherwise cover everyday expenses, emergencies, or savings goals.
    • Refunds may take time and can depend on account closure, repayment, or other agreement conditions.
    • Collateral does not prevent interest or other fees from accumulating under the card’s terms.
    • A secured card does not guarantee approval, an upgrade, or improved credit. Missed payments or high balances can create financial and credit consequences.

    Limitations and common misunderstandings

    Deposit terms alone cannot tell you whether a card is right for you. Your eligibility, credit limit, costs, and access to a refund depend on the specific issuer and agreement. A card’s application page may summarize important features but omit details in the formal documents. If the written terms conflict with a marketing description or a representative’s explanation, ask the issuer to clarify before applying.

    A deposit is not a guarantee that you can spend that amount without consequences. Purchases still create a balance that must be paid according to the card’s billing terms. Nor does providing collateral ensure that the issuer will report to every credit bureau or that your credit score will improve. Credit scores are affected by multiple factors, and scoring models can differ.

    Compare secured cards on total cost and use, not on a single headline feature. People managing debt may also want to compare repayment options, including personal loans or debt-consolidation products, while carefully checking fees, rates, and risks. Other comparison topics—such as rewards cards, checking account fees, mortgage rates, car or home insurance, retirement accounts, and budgeting tools—have different terms and should be evaluated using criteria suited to those products.

    Sources and comparison method

    This guide uses a document-first comparison method rather than ranking specific cards. Review the Consumer Financial Protection Bureau’s secured credit card information and its Credit Card Agreement Database for background and agreement examples. Then rely on the current issuer’s own pricing disclosure, cardholder agreement, and any separate deposit agreement for the product you are considering. These sources serve different purposes: general consumer information can explain common features, while the issuer’s current contract governs its account terms. Confirm details directly with the issuer when documents are unclear.

    Q&A

    Is a secured card deposit the same as a payment toward my balance?

    Usually, no. The deposit generally serves as collateral, while purchases are billed separately. Check the agreement for the issuer’s exact rules and any circumstances in which collateral can be applied to amounts owed.

    Will I get my deposit back automatically?

    Not necessarily. The process may depend on closing the account, paying outstanding amounts, or meeting other conditions. Check how to request a refund, how it is sent, and when processing begins.

    Does a bigger deposit guarantee a higher credit limit?

    No. The issuer’s policy determines the credit limit, and it may differ from the deposit. Confirm the limit and its relationship to collateral before funding the account.

    Can a secured card improve my credit score?

    It may help build payment history if the issuer reports the account and you manage it responsibly, but no particular score result is guaranteed. Confirm reporting practices and make payments on time.

    Bottom line

    To compare secured credit card deposit terms, follow the money from funding through possible refund. Confirm the deposit range, credit-limit formula, payment timing, collateral treatment, refund conditions, and separate card costs in current written documents. Choose only a deposit you can afford to leave unavailable, and compare the whole account rather than relying on a low minimum alone.

    Informational disclaimer: This article is general educational information, not individualized financial, legal, or credit advice. Terms and eligibility vary. Review the current agreement and consider consulting a qualified adviser if you need guidance for your circumstances.

  • How to Compare Secured Credit Card Deposit Terms

    A secured credit card can help someone build or rebuild credit, but its deposit terms affect how much money is tied up, when it may be returned, and what happens if the account falls behind. Comparing cards means looking beyond the advertised minimum deposit: check how the deposit relates to the credit limit, whether you can add to it, and the conditions for getting it back.

    This guide explains how to compare secured credit card deposit terms using issuer disclosures, what to ask before applying, and how to weigh the trade-offs. Terms differ by card and can change, so verify the current agreement and pricing disclosure before you submit an application.

    What is a secured credit card deposit?

    A secured credit card is a credit card backed by a security deposit that the card issuer holds as collateral. You use the card to borrow up to its credit limit and must make payments under the account agreement. The deposit is not a payment toward purchases, a credit limit by itself, or a substitute for making monthly payments. If you do not pay as agreed, the issuer may have rights to apply some or all of the deposit to amounts owed, subject to the agreement and applicable law.

    Many secured cards set the credit limit at or near the deposit amount, but the relationship is not universal. Some issuers offer a different limit or allow a range of deposit amounts. The deposit is generally refundable when the account is closed and the balance and other obligations are settled, or when an issuer upgrades the account to an unsecured card. The timing and conditions depend on the issuer’s written terms.

    Why deposit terms matter

    The deposit can be a meaningful out-of-pocket commitment. Money held as collateral is not available for rent, bills, emergency savings, or paying down higher-cost debt. A card with a lower minimum deposit may be easier to open, but it may also have a lower credit limit. A larger deposit may increase the available limit at some issuers, but that does not automatically make the card a better choice.

    Deposit terms also shape your exit options. If you need the funds back by a certain date, a card that returns collateral only after closure may be less suitable than one with a clearly described graduation process. Do not assume that responsible use guarantees an upgrade or a particular refund date; look for specific written conditions.

    Terms to compare before applying

    1. Minimum and maximum deposit

    Record the minimum deposit required to open the account and any maximum the issuer permits. Check whether the deposit must be paid in one transaction, whether a particular payment method is required, and how long the issuer says it may take to process the application and deposit. A low advertised minimum does not tell you whether that amount will be approved for your account or whether other eligibility requirements apply.

    Compare the deposit with your available cash, not just with the credit limit you hope to receive. Do not use money needed for essential expenses. If the issuer requires a larger deposit than you can comfortably set aside, consider another card or a different way to build credit rather than stretching your budget.

    2. How the deposit determines the credit limit

    Read the issuer’s explanation of how it sets the initial limit. Is the limit equal to the deposit, a percentage of it, or determined through an application review? Can the issuer approve a limit below the amount you offered? Is there a separate maximum credit limit? These details matter because a deposit of a given size does not always produce the same spending capacity across cards.

    A higher limit can make it easier to keep a low balance relative to the limit if you use the card. However, the deposit is not a reason to spend more. Paying the statement balance on time, and avoiding charges you cannot repay, is more important than trying to use a particular share of the limit.

    3. Whether and how you can add to the deposit

    Some issuers may let cardholders add collateral or request a higher limit; others may not. Check whether additional deposits are accepted, whether an account review is required, and whether an added deposit changes the credit limit automatically. Find out if there is a cap and whether the added amount is subject to the same refund rules as the original deposit.

    Do not send extra money based on an assumption that it will raise your limit. Confirm the process directly through the issuer’s official website or customer service and keep a record of any confirmation.

    4. Refund conditions and timing

    Look for the exact events that release the deposit. Does the issuer return it after you close the account and pay the full balance? Can it return collateral when the account is upgraded? Does the agreement say how refunds are issued, such as by check or credit to a linked account? Is there a stated processing period after the account is eligible?

    Also check what happens if there is a pending transaction, unpaid fee, disputed charge, or remaining balance. A refund may be delayed while an amount is unresolved, and the issuer may be entitled to apply collateral to eligible obligations. The agreement, not a general description of secured cards, controls the details.

    5. Graduation and account reviews

    Some issuers review secured accounts for a possible upgrade to an unsecured card. Compare whether reviews are automatic or must be requested, when they may occur, and what factors the issuer says it considers. Ask whether an upgrade keeps the same account number and history, whether the card’s fees or rewards change, and when collateral is returned.

    Graduation is not guaranteed unless the issuer’s terms explicitly promise it and state the conditions. On-time payments and responsible use can support a healthy credit history, but an issuer may also consider information in your application or credit file. Avoid choosing a card solely on a vague suggestion that it will graduate quickly.

    6. Costs beyond the deposit

    The deposit is not the only cost to compare. Review the annual fee, interest rate, late-payment fee, and any other charges in the issuer’s pricing disclosure. A deposit does not prevent interest from accruing on an unpaid balance. If you pay the statement balance in full by the due date, you may avoid purchase interest when the account provides a grace period and you meet its conditions; verify those conditions in the agreement.

    Compare rewards only after considering fees and the cost of borrowing. A card advertised with cash back may be less valuable to you than a lower-cost card if the annual fee outweighs the rewards you realistically expect to earn.

    Practical steps for comparing cards

    1. Set a safe deposit budget. Decide how much cash you can leave unavailable without disrupting bills or emergency savings. Treat the deposit as tied-up collateral, not as spendable money.
    2. Collect current documents. For each candidate, find the issuer’s application details, pricing disclosure, and cardholder or account agreement. Save the versions you reviewed and note the date, since terms can change.
    3. Make a side-by-side comparison. Record the minimum and maximum deposit, deposit-to-limit formula, options for adding collateral, refund conditions, and any stated refund processing time. Add fees, interest, and credit-reporting information to the same list.
    4. Check how the card reports. Confirm whether the issuer reports account activity to the major credit bureaus and whether it reports to all three. Reporting practices can vary. A secured card does not guarantee a higher credit score; payment history, balances, the rest of your credit file, and scoring methods all matter.
    5. Ask precise questions. If a document is unclear, ask the issuer: What exact event releases my deposit? Can collateral be used for a balance or fees? What is the process and expected timing after closure or upgrade? Request answers in writing when possible.
    6. Review the full budget impact. Compare the deposit with other priorities. If you are carrying expensive debt, a personal loan or debt-consolidation option may be worth researching, but compare total repayment costs and eligibility rather than assuming a new loan will save money. Keep the secured card decision separate from any borrowing decision.
    7. Choose based on terms you can verify. Apply only when you understand the deposit, fees, and refund rules. Once approved, use the card for manageable purchases, pay on time, and monitor statements for errors or unexpected charges.

    Neutral pros and cons of deposit terms

    Potential advantages

    • A deposit may make a credit card available to applicants who have limited or damaged credit histories, though approval is not guaranteed.
    • A clearly defined deposit-to-limit arrangement can make the initial credit limit easier to understand.
    • If the issuer reports the account to credit bureaus, consistent, on-time payments may contribute to a positive credit history over time.
    • Written refund and upgrade rules make it easier to plan when collateral may become available again.

    Potential disadvantages

    • The deposit ties up cash that could be needed for everyday expenses or emergencies.
    • Refunds may depend on paying the balance and satisfying account conditions, so the money may not be available immediately when you want it.
    • Fees and interest can make a card costly despite the collateral, and a deposit does not erase missed-payment consequences.
    • Graduation may be discretionary or unavailable, and a secured card may not suit someone who needs access to the deposit soon.

    Limitations and common misunderstandings

    A deposit is collateral, not a savings balance you can freely withdraw. Do not assume it earns interest or is protected in the same way as money in a deposit account; ask the issuer how it is held and what protections apply. Do not assume the card’s limit will match the deposit, that every issuer reports to every credit bureau, or that a particular payment pattern guarantees a score increase.

    Credit scoring systems differ, and lenders may use different scores and criteria. A secured card can be one tool for building credit, but it cannot remove accurate negative information from a credit report or guarantee approval for future borrowing. If you are comparing banking products more broadly, keep the purpose of each product clear: a high-yield savings account is for holding savings, while a checking account is designed for transactions and may have its own fees. Neither is equivalent to collateral held for a credit card.

    For any candidate card, rely on the current issuer agreement and pricing disclosure rather than an old review, an advertisement, or a comparison table that may not reflect current terms. Consumer Financial Protection Bureau (CFPB) consumer guidance can help explain secured cards and credit-card costs. A practical comparison method is to use that guidance for general context, then verify every deposit, fee, limit, and refund detail in the issuer’s own documents. The issuer’s written terms govern your account.

    Concise Q&A

    Is a secured card deposit refundable?

    Usually, the deposit is refundable when the account meets the issuer’s release conditions, such as being closed with the balance paid or being upgraded. Check the agreement for exceptions, processing time, and how a refund is delivered.

    Does a larger deposit always mean a higher credit limit?

    No. Issuers set limits differently. Confirm the deposit-to-limit formula and any maximum before applying.

    Can the issuer keep the deposit if I miss payments?

    The deposit serves as collateral, and the agreement may allow the issuer to apply it to amounts owed. You remain responsible for the account under its terms, so read the default and payment sections carefully.

    Will a secured card improve my credit score?

    It may help build a payment history if the issuer reports the account and you manage it responsibly, but no score change is guaranteed. Check reporting practices and monitor your credit reports.

    Bottom line

    To compare secured credit card deposit terms, focus on the amount required, how it sets the credit limit, whether more collateral can be added, and precisely when and how the deposit is returned. Then compare fees, interest, reporting practices, and upgrade rules. The most suitable card is not necessarily the one with the largest limit or most prominent rewards; it is the one whose documented terms fit your budget and whose deposit you can afford to leave tied up.

    Informational only, not individualized financial advice. Review current card documents and consider your full financial situation before applying.