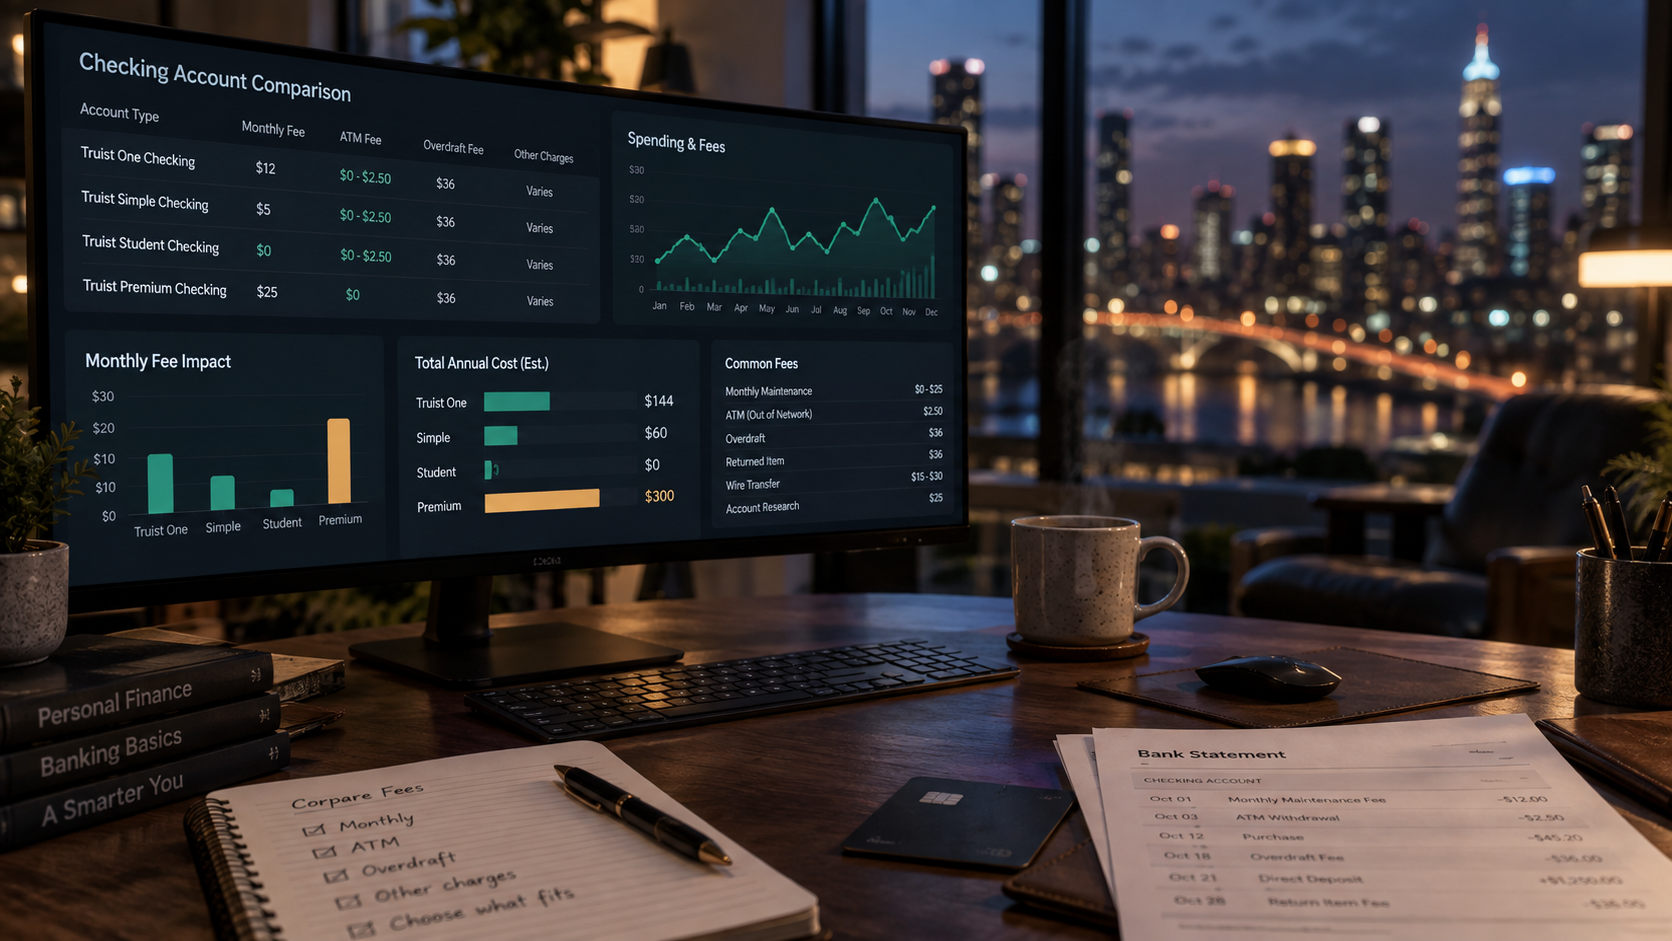
Truist checking account fees depend on the account type, how you use the account, and whether you qualify for a fee waiver. For many customers, the main charge to examine is the monthly maintenance fee. Other possible costs include overdraft fees, out-of-network ATM fees, wire transfer charges, cashier’s check fees, and fees related to special account services.
This guide explains what are Truist checking account fees, how the most common charges work, and how to compare a Truist account with other banking products. Fee amounts and waiver rules can change, so confirm the current terms in the applicable Truist fee schedule and account agreement before opening an account.
What Are Truist Checking Account Fees?
Truist checking account fees are charges that may apply when you maintain or use a Truist checking account. They generally fall into four groups:
- Account maintenance fees: recurring charges for keeping an account open.
- Transaction and access fees: charges for certain ATM withdrawals, wire transfers, cashier’s checks, or other services.
- Overdraft and returned-item fees: charges that may apply when a transaction exceeds the available balance or is returned unpaid.
- Optional service fees: charges for products or services that are not required for ordinary checking use.
The relevant fee is not always the listed price. A monthly fee may be waived if you meet the account’s eligibility requirements, while an account advertised as having no monthly fee may still charge for out-of-network ATM use, expedited services, or certain transactions.
Common Truist Checking Account Charges
Monthly maintenance fee
Truist One Checking has a standard monthly maintenance fee listed by Truist as $12. Truist describes several ways customers may qualify to have this fee waived, including meeting a qualifying direct-deposit requirement, maintaining the required balance, or qualifying through an age-based condition. The exact requirements and definitions apply according to the account agreement and current fee schedule.
That distinction matters. A direct deposit may need to meet Truist’s definition of a qualifying deposit, and the bank may evaluate eligibility during a specified statement cycle. Transfers between your own accounts may not receive the same treatment as payroll, government, or other qualifying deposits. Before relying on a waiver, read the disclosure for the account you plan to open.
Truist also offers other checking products, including Truist Confidence Account. This account is designed for customers who want a lower-risk account structure and does not include traditional overdraft capability. It has its own monthly fee and waiver rules, so its pricing should not be assumed to match Truist One Checking.
Overdraft and returned-item fees
Truist’s published personal deposit account fee schedule lists a $36 overdraft fee for an item paid into overdraft, subject to the terms and limits in the schedule. A returned-item fee may also apply when a transaction is returned unpaid. The bank’s policies can vary by account and transaction type, and an overdraft protection service may change how a transaction is handled.
Do not evaluate overdraft exposure by looking only at the stated fee. Consider when transactions post, whether pending transactions affect available funds, whether recurring payments can overdraw the account, and whether the account has an overdraft grace period or other limit. Some transactions may be declined rather than paid, which can create separate problems such as a late payment or merchant fee.
ATM fees
Using a Truist ATM is generally different from using a non-Truist ATM. A non-Truist ATM operator may charge its own fee, and Truist may charge an additional out-of-network ATM fee depending on the account and transaction. The ATM should display the operator’s surcharge before you confirm the withdrawal.
ATM access is an important comparison point if you regularly withdraw cash. A bank with a smaller branch and ATM network may be less convenient even when its monthly fee is lower. Check the account’s current ATM fee policy, the size of the network in places you visit, and whether reimbursement is available.
Wire transfers and other banking services
Truist may charge fees for domestic or international outgoing wire transfers, incoming wires, cashier’s checks, official checks, stop-payment requests, and other special services. These charges are usually separate from the monthly maintenance fee. The price may also differ between online, branch, and other service channels.
For occasional services, ask for the current price before submitting the request. For recurring use, such as sending wires for a business, supporting family overseas, or managing a real estate transaction, compare the full service fee with alternatives such as an online bank or a regulated payment provider. Exchange-rate markups and intermediary-bank charges can affect the total cost of an international transfer even when the visible bank fee looks modest.
Truist Checking Account Fee Comparison
| Fee category | What to review | Why it matters |
|---|---|---|
| Monthly maintenance | Listed fee, waiver conditions, and evaluation period | A recurring fee can outweigh a higher interest rate elsewhere. |
| Overdraft | Paid-item fee, returned-item fee, grace period, and transaction controls | Occasional mistakes can become expensive if the account routinely runs near zero. |
| ATM access | Network size, out-of-network fees, and reimbursement policy | Frequent cash withdrawals can make ATM charges more important than the monthly fee. |
| Special services | Wire transfers, official checks, stop payments, and expedited services | These costs matter when you use banking services beyond ordinary card and bill transactions. |
| Account restrictions | Minimum opening deposit, eligibility, transaction limits, and balance rules | A lower-cost account may have features or limits that do not fit your routine. |
How to Avoid or Reduce Truist Checking Fees
1. Identify the account and its exact disclosure
Start with the account name, not a general search for Truist fees. Truist One Checking, Truist Confidence Account, and other deposit products can have different fees and features. Download or review the current fee schedule and the account’s Truth in Savings disclosure. Save a copy for your records because terms can be updated later.
2. Test whether the monthly-fee waiver is realistic
Write down the waiver conditions and compare them with your actual finances. If the requirement involves direct deposit, confirm that your employer or benefits payer sends a deposit that qualifies. If it involves a balance, determine whether maintaining that balance would reduce your emergency savings or cause you to carry a costly credit-card balance.
A waiver is useful only when it occurs consistently. Do not keep unnecessary cash in a checking account solely to avoid a fee if the money could serve a more important purpose, such as paying high-interest debt or building an emergency fund.
3. Use balance alerts and transaction controls
Set low-balance and large-transaction alerts through online or mobile banking. Review pending and posted transactions regularly, especially around rent, mortgage payments, subscriptions, and automatic transfers. Keep a small buffer only if doing so fits your budget. A buffer is not a substitute for checking the account because authorization and posting times can differ.
4. Plan ATM use
Use Truist’s ATM locator before traveling or withdrawing cash. When a non-Truist ATM is unavoidable, read the fee disclosure on the screen and consider whether a larger, planned withdrawal is less costly than multiple small withdrawals. Avoid choosing an ATM based only on convenience if the combined operator and bank fees are material to your budget.
5. Ask before ordering special services
Before requesting a wire transfer, cashier’s check, stop payment, or expedited delivery, ask the bank to state the applicable fee and any third-party charge. For international transfers, ask how the exchange rate is determined and whether an intermediary bank could deduct a charge from the amount received.
Pros and Cons of a Truist Checking Account
Potential advantages
- Branch and ATM access: Customers who value in-person service may prefer a regional bank with branches and ATMs in their area.
- Fee-waiver options: Customers who already receive qualifying direct deposits or can meet the balance requirement may avoid the standard monthly maintenance fee.
- Account choices: Truist offers more than one checking structure, including an account designed to limit traditional overdraft risk.
- Integrated banking: Customers using Truist savings, credit cards, mortgages, or other services may find one-bank account access convenient.
Potential disadvantages
- Monthly fee risk: The standard fee can be meaningful for customers who do not meet the waiver conditions.
- Complexity: The lowest-cost option depends on account-specific rules, qualifying deposits, statement cycles, and service usage.
- Possible overdraft costs: A customer who regularly misjudges available funds can incur charges or have payments declined.
- Different digital-bank pricing: Some online checking accounts may offer lower monthly fees or broader ATM reimbursement, although they may provide fewer branches or cash services.
How Truist Compares With Other Checking Accounts
A fair comparison should use your expected annual cost rather than the advertised monthly fee alone. Add the monthly maintenance fee you are likely to pay, expected ATM charges, wire or service fees, and any overdraft-related cost based on your own behavior. Then compare that total with accounts from online banks, credit unions, and other full-service banks.
Also compare the features that have value even when they do not appear as a line-item fee:
- Access to branches and cash deposits
- ATM network and reimbursement policy
- Mobile deposit, bill pay, and transfer speed
- Overdraft settings and account safeguards
- Customer support availability
- Interest paid on checking balances, if any
- Connection to savings, credit cards, loans, or mortgage products
For a broader personal finance comparison, keep checking money separate from savings goals. A checking account is usually designed for payments and liquidity, while a high-yield savings account may be more appropriate for cash that does not need to cover immediate transactions. A rewards credit card may offer benefits, but interest charges can exceed those rewards when balances are carried. Similarly, an advertised loan or mortgage rate should be compared with the annual percentage rate, fees, repayment terms, and your credit profile.
Limitations of Fee Comparisons
Published fee tables do not predict the cost for every customer. Your total may depend on account eligibility, location, service channel, transaction type, balance history, deposit timing, and policy changes. A bank may also change its fee schedule after you open an account, subject to applicable notice requirements.
There is also a difference between a bank fee and a fee charged by another party. An ATM owner, payment network, intermediary bank, merchant, or biller may impose a separate charge. When comparing accounts, identify who receives each fee and whether it can be avoided.
Sources and Comparison Methodology
This article uses the Truist Personal Deposit Accounts Fee Schedule, Truist checking-account disclosures, and Truist product information as the primary sources for account-specific pricing and waiver conditions. It also follows consumer account-comparison principles described by the Consumer Financial Protection Bureau, including reviewing overdraft practices, account disclosures, and the total cost of banking services. Because pricing and eligibility rules can change, the current Truist documents control over any summary in this article.
To compare products, list the fees you are likely to incur over a typical year, check the waiver conditions, and verify the network and features that affect your daily use. Use the same assumptions for every bank or credit union in the comparison. Do not compare a waived fee at one institution with an unavoidable fee at another without checking whether you can realistically qualify for the waiver.
Q&A
Does Truist One Checking always charge a monthly fee?
No. Truist One Checking has a listed monthly maintenance fee, but qualifying customers may have it waived under the account’s current rules. Confirm the direct-deposit, balance, age, or other eligibility conditions before assuming the waiver applies.
What is the listed Truist One Checking monthly fee?
Truist lists a $12 monthly maintenance fee for Truist One Checking. The applicable account disclosure and fee schedule should be checked for current pricing and waiver requirements.
Can Truist charge an overdraft fee?
Truist’s published fee schedule lists a $36 fee for an item paid into overdraft, subject to account terms and applicable limits. Transactions may instead be declined or returned, and those outcomes can have different consequences.
Is the Truist Confidence Account the same as a regular checking account?
No. The Confidence Account uses a different structure and is intended to help limit overdraft risk. It has its own monthly fee, waiver rules, and transaction features, so compare its disclosure separately.
How can I find the exact fee for my account?
Check your account agreement, current Truist Personal Deposit Accounts Fee Schedule, online banking disclosures, or a Truist representative. Ask which fee applies before ordering a special service or making a transaction through a non-Truist provider.
Informational disclaimer: This article is for general educational purposes and is not banking, tax, legal, credit, or investment advice. Bank fees and account terms can change. Verify the current Truist disclosures and consider your own budget and financial circumstances before opening or changing an account.
Leave a Reply