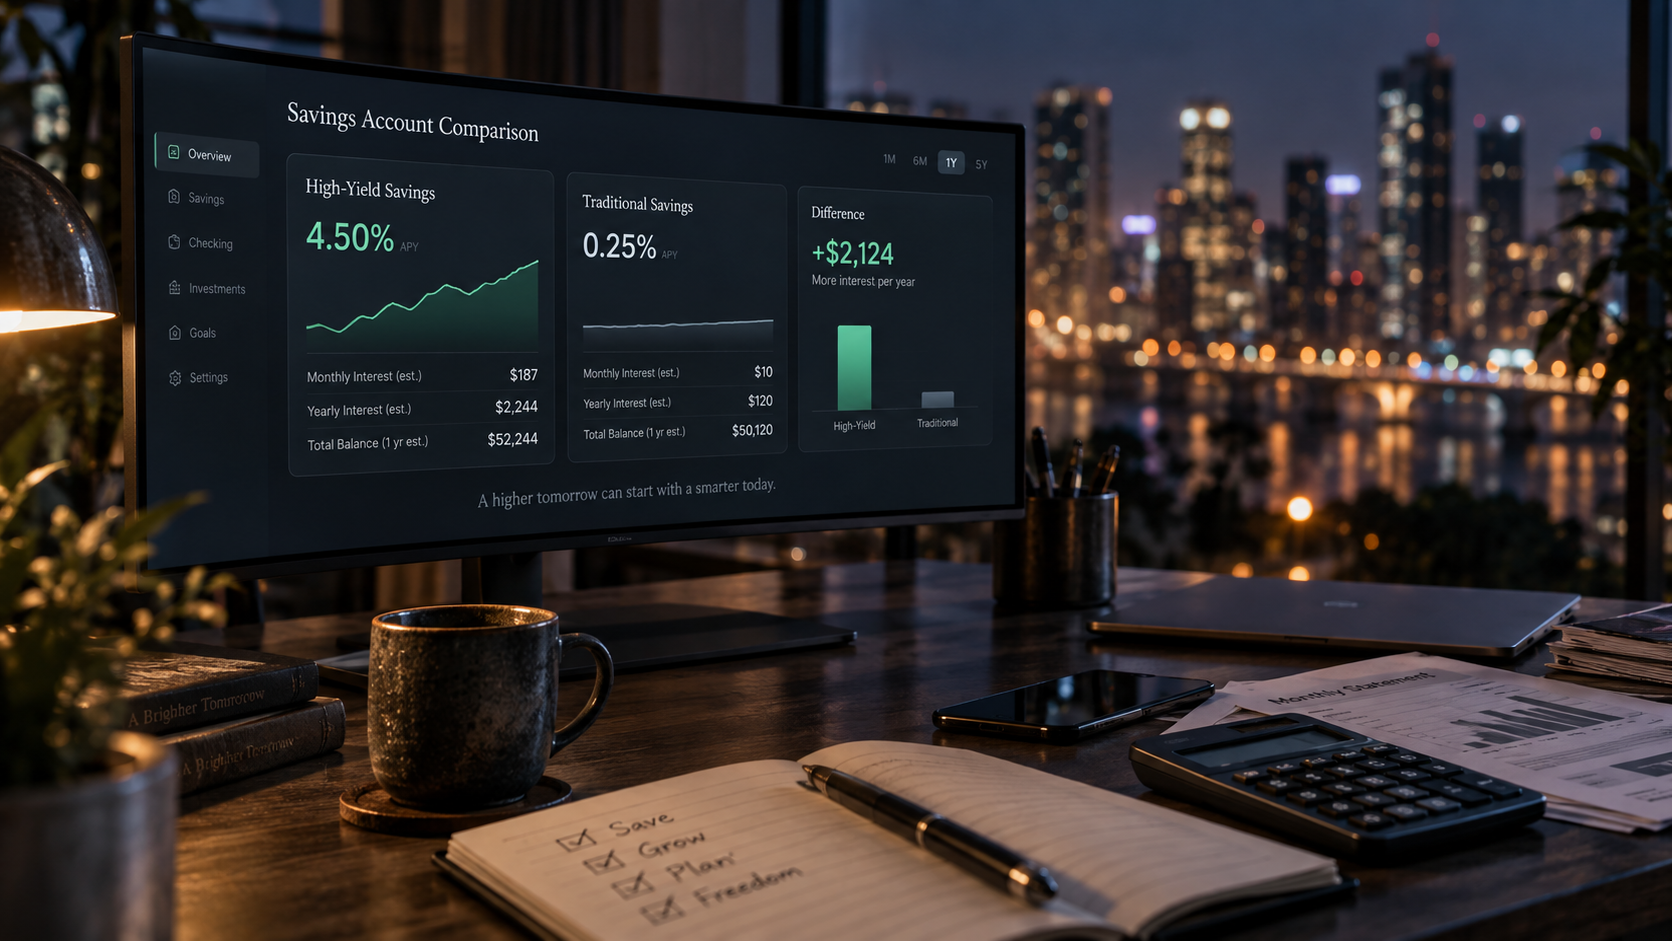
Many people search for “why high yield savings account” when they want their cash to earn more interest without taking stock-market risk. A high-yield savings account, often called a HYSA, is a deposit account that generally offers a higher annual percentage yield (APY) than a standard savings account. It can be useful for an emergency fund, a planned purchase, or cash that you may need within the next few years.
However, a higher advertised yield does not automatically make an account the best choice. The APY can change, withdrawals may be limited or discouraged, and some accounts require online banking or electronic transfers. This guide explains how these accounts work, how to compare them with other banking products, and what limitations to consider before opening one.
What Is a High-Yield Savings Account?
A high-yield savings account is a savings account designed to pay a comparatively competitive interest rate on deposited money. The account usually earns interest through a variable APY, meaning the bank or credit union can change the rate as market conditions and its own pricing decisions change.
Unlike an investment account, a savings account is not intended to rise and fall with stock or bond prices. When held at an eligible institution, deposits may be protected by federal deposit insurance within applicable limits. The Federal Deposit Insurance Corporation (FDIC) generally insures eligible deposits at FDIC-member banks up to the standard maximum amount per depositor, per insured bank, for each ownership category. The National Credit Union Administration (NCUA) provides similar coverage for eligible deposits at federally insured credit unions.
Deposit insurance protects against the failure of a covered institution; it does not guarantee a particular interest rate or protect against inflation. Before depositing money, verify the institution’s insurance status and review how the account is titled.
Why Use a High-Yield Savings Account?
1. It can improve the return on accessible cash
The main reason to consider a HYSA is the possibility of earning more interest while keeping the money relatively accessible. A traditional savings account may offer a lower APY, while a high-yield account may be priced more competitively. The difference matters most when you maintain a meaningful balance for a long period, although the actual benefit depends on the rate, balance, and time.
Interest is usually calculated from the account balance and credited according to the institution’s terms. To compare offers fairly, use APY rather than only the stated interest rate. APY reflects the effect of compounding under the account’s stated assumptions. Ask whether the advertised APY applies to every balance, only to new customers, or only while certain conditions are met.
2. It can separate savings from everyday spending
Keeping emergency savings in a separate account can reduce the temptation to spend it on routine purchases. A separate HYSA may create a practical boundary between money for rent, groceries, and bills and money reserved for unexpected expenses or future goals.
This separation is not a guarantee of good budgeting, but it can work alongside automatic transfers, a written spending plan, and budgeting calculators or other budgeting tools. You might use labeled savings goals for car repairs, annual insurance premiums, travel, or a future home down payment, if the bank supports that feature.
3. It may provide a balance between access and return
Cash has different jobs. Money needed today may belong in a checking account. Money needed soon but not immediately may fit a savings account. Money that will not be needed for a longer period may be considered for a certificate of deposit, retirement account, or diversified investment, depending on your objectives and risk tolerance.
A HYSA can occupy the middle ground: it may offer more interest than basic checking while allowing transfers and withdrawals more easily than many time-locked products. Access is not always instant, though. ACH transfers can take time, and banks may apply limits, holds, or verification procedures.
High-Yield Savings Accounts Compared With Other Products
HYSA versus checking account
A checking account is usually built for frequent transactions, direct deposits, debit-card purchases, bill payments, and ATM access. A high-yield savings account is generally better suited to storing money rather than spending it every day. Some online savings accounts do not include checks, debit cards, or convenient cash deposits.
One useful arrangement is to keep operating money in checking and transfer excess cash to savings. Compare checking account fees carefully, including monthly maintenance fees, overdraft-related charges, out-of-network ATM fees, wire fees, and minimum-balance requirements. A high APY may not compensate for fees if the account is difficult to use or repeatedly incurs charges.
HYSA versus money market account
Money market deposit accounts are bank or credit union deposit products, not the same as money market mutual funds. Depending on the institution, a money market deposit account may offer check-writing or debit-card access, but it may also have different balance requirements and rates. Compare the APY, access methods, fees, and insurance status rather than relying only on the product name.
HYSA versus certificate of deposit
A certificate of deposit (CD) generally pays a stated rate for a selected term. In exchange for committing the money until maturity, you may receive more predictable earnings than with a variable-rate savings account. Early withdrawal can result in a penalty, and the money may be less flexible.
A HYSA may be more appropriate for an emergency fund or an uncertain time horizon. A CD may be worth comparing when you know you will not need the money during the term and want to evaluate rate certainty. A CD ladder can spread maturity dates, but it requires additional planning and may not provide immediate access to all funds.
HYSA versus investments and retirement accounts
Stocks, bonds, mutual funds, and exchange-traded funds can have higher long-term growth potential than a savings account, but they can also lose value. A HYSA is generally designed for capital preservation and liquidity, not long-term growth above inflation.
Retirement accounts and IRAs may offer tax advantages, but they also have eligibility rules, contribution limits, investment choices, and withdrawal considerations. Emergency cash usually should not be placed in an account where accessing it could create taxes, penalties, or a forced sale of investments. The appropriate choice depends on the purpose and time horizon of the money.
How to Compare High-Yield Savings Accounts
A reliable comparison should look beyond the headline APY. Use the following process:
- Confirm the institution and insurance. Check whether the bank is FDIC-insured or the credit union is federally insured by the NCUA. If a financial technology company provides the interface, identify the actual deposit-holding institution and understand how pass-through insurance is described.
- Record the APY and rate conditions. Note whether the APY is variable, introductory, tiered by balance, or conditional on direct deposit or another requirement. Save the date of your comparison because rates can change.
- Review fees. Look for monthly maintenance fees, excessive withdrawal fees, returned-payment fees, wire charges, paper statement fees, and charges for expedited services. Also check whether the institution requires a minimum opening deposit or minimum balance.
- Test access before opening. Determine how to move money in and out, how long ACH transfers typically take under the account agreement, whether external accounts can be linked, and whether cash or checks can be deposited. Review daily transfer limits and any temporary holds.
- Examine the legal documents. Read the account agreement, fee schedule, privacy notice, and funds-availability policy. Marketing pages summarize products, but these documents control the relationship.
- Estimate the practical benefit. Compare expected interest using the balance you can realistically maintain, not an idealized balance. Subtract recurring fees and account for the possibility that the APY may decrease.
- Consider customer support and security. Look for secure login controls, multifactor authentication, transaction alerts, a clear fraud-reporting process, and support hours that match your needs.
This methodology is based on comparing official account disclosures and fee schedules, with consumer-protection information from the FDIC and the Consumer Financial Protection Bureau (CFPB) used to clarify deposit insurance, account terms, and access considerations. The CFPB’s consumer banking resources and the FDIC’s deposit insurance materials are useful starting points for verifying general rules. For current rates and requirements, rely on the institution’s own disclosures rather than an older comparison article.
Practical Ways to Use a High-Yield Savings Account
Build an emergency reserve
Start by identifying essential expenses such as housing, utilities, food, transportation, insurance, and minimum debt payments. Choose a reserve target based on your income stability, household responsibilities, health needs, and access to other resources. Keep enough in a readily available account for immediate bills, then consider a HYSA for the remainder if transfer timing is acceptable.
Automate a specific goal
Set a recurring transfer after payday and name the goal clearly. For example, you could save for an insurance premium, a professional certification, a replacement vehicle, or a moving expense. Automating a manageable amount is often more sustainable than making irregular transfers when money happens to remain at the end of the month.
Coordinate savings with debt repayment
High-interest credit card debt often deserves attention because its interest cost may exceed what a savings account earns. Still, eliminating all cash reserves can leave you vulnerable to using a credit card again when an unexpected expense occurs. Consider keeping a basic emergency cushion while directing additional money toward expensive debt, then compare personal loans or debt-consolidation options carefully. A lower monthly payment is not necessarily a lower total cost if the repayment term becomes longer or fees are added.
Review the account periodically
Check the APY, fees, statements, beneficiaries, linked accounts, and security settings at reasonable intervals. If the rate falls, compare alternatives, but do not move funds solely because of a temporary promotional rate. Also review how the account fits with your broader finances, including credit score improvement goals, insurance deductibles, mortgage rate comparison decisions, and retirement contributions.
Pros and Cons
Potential advantages
- It may pay more interest than a basic savings account.
- It can keep emergency or goal-based money separate from daily spending.
- Eligible deposits may receive FDIC or NCUA insurance within applicable limits.
- It generally offers more flexibility than a CD with an early-withdrawal penalty.
- Online account tools may support automatic transfers and transaction alerts.
Potential disadvantages
- The APY is usually variable and may decrease without a matching increase in your balance.
- Some accounts have limited branch, ATM, cash-deposit, or check-writing access.
- Transfers may not be immediate, especially between unrelated institutions.
- Promotional or tiered rates may not apply to your full balance or may expire.
- Interest may not keep pace with inflation, reducing purchasing power over time.
- Deposit insurance does not protect investments, cryptocurrency, unauthorized account activity caused by poor security practices, or losses above applicable coverage limits.
Limitations and Common Mistakes
A HYSA is not automatically the highest-return destination for every dollar. It may be unsuitable for money needed for same-day purchases if transfers are slow, and it may be inefficient for long-term retirement growth if used instead of an appropriate investment strategy. The account also cannot replace a budget, adequate insurance, or a plan for high-interest debt.
Common mistakes include chasing a temporary APY without reading its conditions, overlooking monthly fees, storing more than the applicable insurance limit at one institution without understanding ownership categories, and assuming that a financial technology app is itself a bank. Another mistake is keeping emergency savings in a product whose withdrawal process has not been tested. Make a small test transfer and confirm how long it takes before relying on the account for an urgent bill.
Concise Q&A
Is a high-yield savings account safe?
It can be relatively low risk when the account is offered by an FDIC-insured bank or an NCUA-insured credit union and your deposits remain within applicable insurance limits. Verify coverage and read the account terms.
Can the APY change?
Yes. Most high-yield savings accounts have variable rates. The institution can change the APY according to its terms, so compare current disclosures rather than assuming today’s rate will last.
Should an emergency fund be in a HYSA?
It may be appropriate if the account is insured, has no problematic fees, and allows access quickly enough for your needs. Keep immediate spending money in an account you can access without delay.
Does a HYSA build credit?
Usually not. Savings accounts generally do not report routine balances or interest payments to the major credit bureaus. Credit score improvement typically involves paying reported debts on time, managing utilization, and checking credit reports for errors.
How much should be deposited?
There is no universal amount. Base the balance on the purpose of the money, your essential expenses, income reliability, and insurance limits. Avoid depositing money that you need for immediate bills or that would be difficult to access when required.
Bottom Line
The best answer to “why high yield savings account” is that it can offer a useful combination of interest, separation from spending, and access for short- and medium-term cash. Its value depends on the complete account package: APY, fees, insurance, transfer speed, conditions, customer support, and security controls.
Compare official disclosures from several institutions, calculate the likely benefit using your real balance, and match the account to the job your money must perform. Do not choose a savings account as a substitute for a personalized investment, tax, legal, or debt-management plan.
Informational disclaimer: This article provides general educational information, not personalized financial advice. Rates, fees, insurance rules, tax treatment, and account terms can change. Confirm current details with the relevant bank, credit union, FDIC, NCUA, CFPB, or a qualified professional before making a financial decision.
Leave a Reply