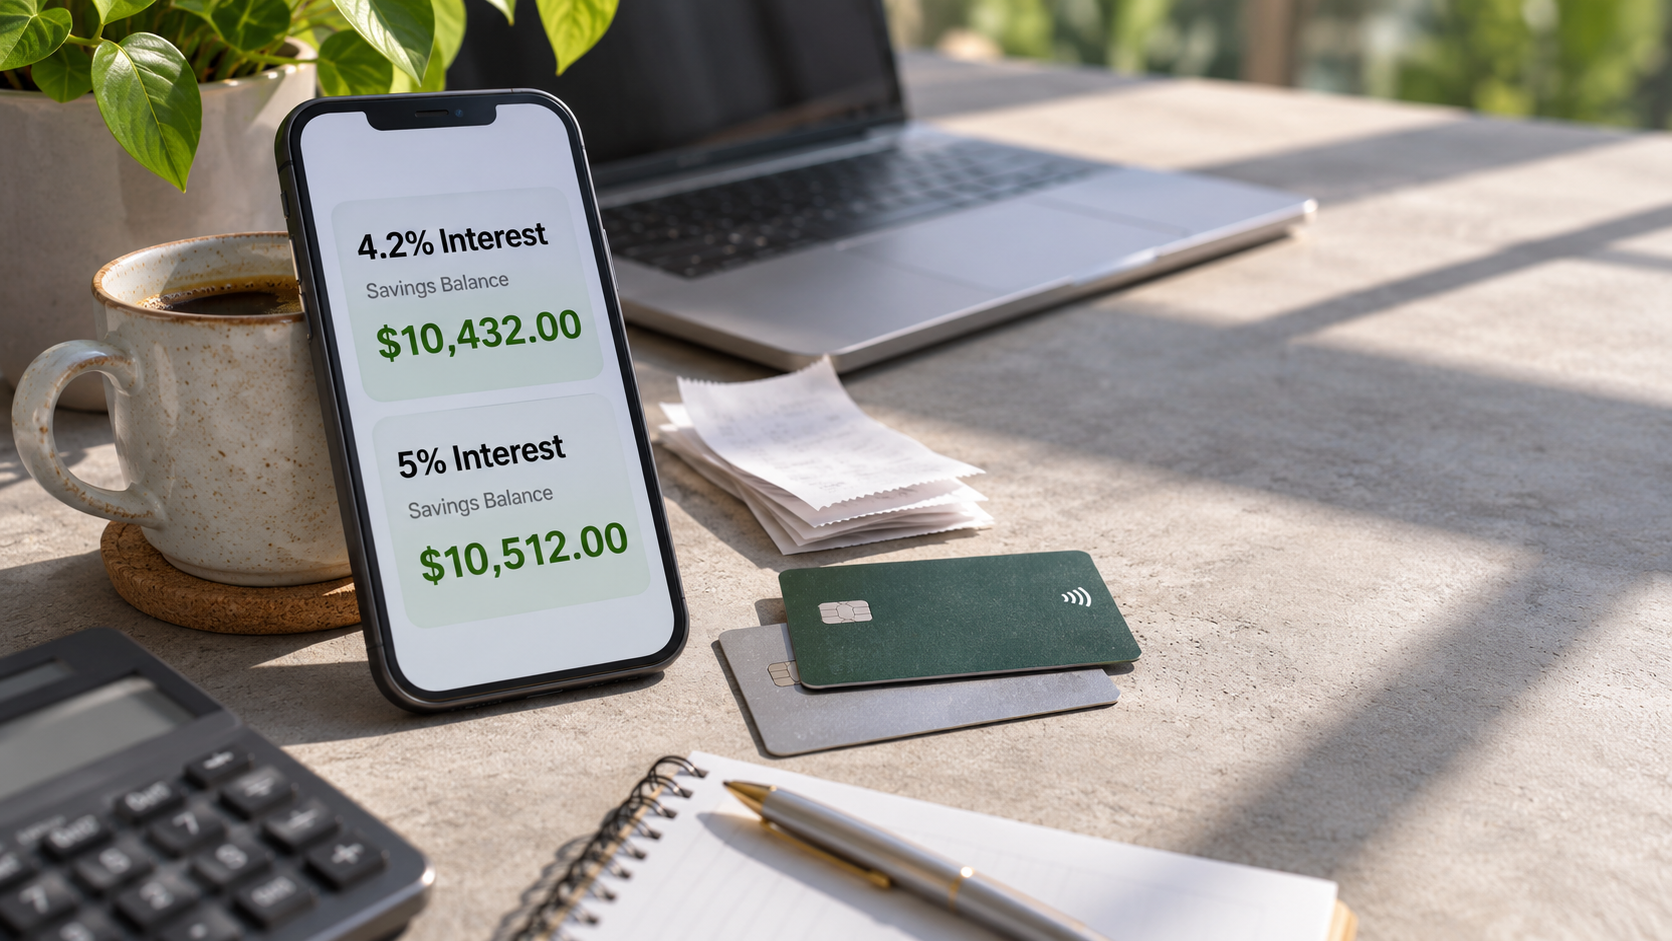
Comparing a 4.2% rate with a 5% rate can look like a small decision. On a savings balance, though, the difference grows with the amount saved, the time it stays in the account, and how interest is calculated. The practical question is not just which percentage is higher: it is how much extra interest the higher rate may earn, and whether the account’s conditions fit your needs.
This guide estimates the difference using transparent assumptions, explains how to compare savings accounts, and notes why advertised rates may not match what you ultimately earn. The figures are examples, not rate quotes or a forecast.
What Does “4.2% Versus 5%” Mean?
A savings account’s annual percentage yield (APY) expresses the interest an account would earn over one year, including the effect of compounding, assuming the rate and balance remain unchanged. A 5% APY is 0.8 percentage points higher than a 4.2% APY. It is not simply “0.8% more” in every sense: the dollar difference depends on your balance and holding period.
APY is useful for comparing deposit accounts because it accounts for compounding. The stated interest rate, sometimes called the nominal rate, may not include that compounding effect. When comparing accounts, use APY against APY and check the institution’s terms for how often interest compounds and when it is credited.
How Much More Could You Earn?
The table below estimates interest on a single deposit that stays in the account for one year, with no additional deposits or withdrawals. It assumes the APY stays constant for the entire year and the balance qualifies for that APY. The figures use the APY relationship directly: ending balance equals starting balance multiplied by one plus APY. They are rounded to the nearest cent.
| Starting balance | At 4.2% APY | At 5% APY | Difference |
|---|---|---|---|
| $1,000 | $42.00 | $50.00 | $8.00 |
| $5,000 | $210.00 | $250.00 | $40.00 |
| $10,000 | $420.00 | $500.00 | $80.00 |
| $25,000 | $1,050.00 | $1,250.00 | $200.00 |
| $50,000 | $2,100.00 | $2,500.00 | $400.00 |
Under these assumptions, the extra interest is about $8 per year for every $1,000 kept in the account. That is a helpful shortcut for a one-year comparison. It does not mean you will receive that exact amount: variable rates can change, account rules can affect eligibility, and taxes can reduce the amount you keep.
What If You Add Money Regularly?
Regular contributions change the calculation because each deposit earns interest only after it enters the account. For example, money deposited near the end of the year has less time to earn than money deposited at the beginning. A calculator that models monthly deposits can give a closer estimate, but you will need to enter the deposit timing, compounding assumptions, and whether the rate is fixed or variable.
For a straightforward comparison, apply the same deposit schedule to both rates. Comparing one account with monthly contributions to another with a single starting balance would not isolate the effect of the APY.
Practical Steps to Compare the Accounts
- Confirm the APY and when it was checked. Savings rates can change. Record the displayed APY and the date you reviewed it. An advertised rate is not a promise that it will last for the full year.
- Check whether the rate applies to your balance. Some accounts use balance tiers, set a maximum balance for the top APY, or offer a promotional rate with eligibility requirements. Review the full terms, not just the headline.
- Look for fees and minimums. A monthly maintenance fee, minimum opening deposit, or minimum balance requirement can affect whether an account is practical. Ask whether a fee can be avoided and what happens if your balance falls below a threshold.
- Review access and transfer timing. Check how you can deposit and withdraw money, whether the provider offers convenient transfers, and whether any limits or processing times matter for your plans. Keep money you may need immediately accessible.
- Compare the estimated dollar outcome. Use your own balance and expected saving period. If you expect the rate to change, treat a one-year estimate as an illustration rather than a guarantee.
- Verify the institution and account terms. Confirm who holds the deposit, what protections apply, and which legal entity is responsible. A comparison article is a starting point, not a substitute for the account agreement.
Using Published Comparisons Responsibly
Several established personal-finance publishers maintain comparisons of savings accounts. Forbes Advisor’s best high-yield savings account awards is one place to review account options and the publisher’s stated evaluation. The Motley Fool’s savings-rate roundup dated November 7, 2026 presents rates in a time-specific format. Money’s high-yield savings account comparison provides another editorial comparison.
These are named editorial sources, not guarantees of the current rate or suitability of any account. Check each article’s publication or update date, the publisher’s methodology and disclosures, and the financial institution’s own current terms. A list can help you identify candidates, but the account agreement determines the actual conditions.
Pros and Cons of Chasing the Higher APY
Potential advantages
- A higher APY can earn more interest on the same eligible balance if the rate holds and the account conditions are met.
- Interest may help a reserve for planned expenses or emergencies grow without taking the investment risk associated with market-based assets.
- Comparing accounts can reveal fees, minimums, or access conditions that matter beyond the headline rate.
Potential disadvantages
- A higher APY may be temporary, variable, limited to a balance band, or conditional on specific account activity.
- Moving money can add administrative work and may temporarily disrupt access while transfers are processed.
- A fee or restrictive condition can outweigh some or all of the added interest, especially on a small balance.
- Interest is generally taxable income in the United States, subject to applicable tax rules. The after-tax amount may be lower than the table’s estimate.
How Savings Fits With Other Financial Comparisons
A savings account comparison is only one part of personal finance. If you carry credit-card debt, the interest charged on that debt may be much higher than the interest earned on savings. Paying down expensive debt can therefore be worth evaluating alongside building cash reserves, while keeping enough accessible money for near-term needs. The right balance depends on your obligations and circumstances.
For credit cards, compare annual fees, purchase APRs, rewards rules, and whether you can pay the statement balance in full. Rewards do not necessarily offset interest costs if you carry a balance. For checking accounts, review monthly fees, overdraft terms, ATM access, and minimum balance rules. For personal loans or debt consolidation, compare the total repayment cost and fees, not just the advertised payment.
The same comparison habits apply elsewhere: mortgage rates need to be evaluated with points, closing costs, and loan terms; auto and home insurance comparisons should account for coverage and deductibles; and retirement accounts and IRAs have different tax treatment and investment risks from bank deposits. Budgeting calculators can help model cash flow, while credit-score tools can help track progress. In every case, compare like with like and read the full terms.
Limitations to Keep in Mind
The table assumes one deposit, a constant APY, no fees, no withdrawals, and no taxes. Actual account interest may be calculated using daily balances and credited on a schedule set by the institution. If rates change during the year, your return will differ from the constant-rate example. A promotional APY may expire, and a balance that exceeds a stated limit may earn a different rate.
These examples also do not account for inflation, which affects what savings can buy over time. A savings account can be useful for cash reserves and near-term goals, but its role is different from long-term investing. Deposit insurance eligibility and limits depend on the institution, account ownership category, and applicable rules. Confirm coverage with the relevant official insurer and the institution rather than relying on a comparison page alone.
Concise Q&A
How much more does 5% earn than 4.2%?
If both are APYs and remain unchanged for one year, 5% earns about $8 more per $1,000 of starting balance. The difference scales with the balance under the same assumptions.
Is 5% always the better account?
Not automatically. Check whether the rate is variable or temporary, whether your balance qualifies, and whether fees or access restrictions reduce the benefit.
Does compounding make the difference larger?
APY already reflects the effect of compounding over a year. If you are given nominal interest rates instead, compounding frequency matters, so compare APYs where possible.
Can I use this estimate for monthly deposits?
Use a calculator that models the timing of each deposit. The table assumes the full starting balance is present for the entire year.
Bottom Line
At a constant one-year APY, the gap between 4.2% and 5% is approximately $8 per $1,000 saved. That can be meaningful on a larger balance, but the best choice depends on the rate’s durability, eligibility rules, fees, and access. Compare current account disclosures, use your own expected balance and timeline, and treat published rate roundups as a way to find options rather than as a guarantee.
Informational only; this article is not personalized financial, tax, or legal advice. Verify current rates, account terms, and applicable protections directly with the provider and qualified professionals when needed.
Leave a Reply