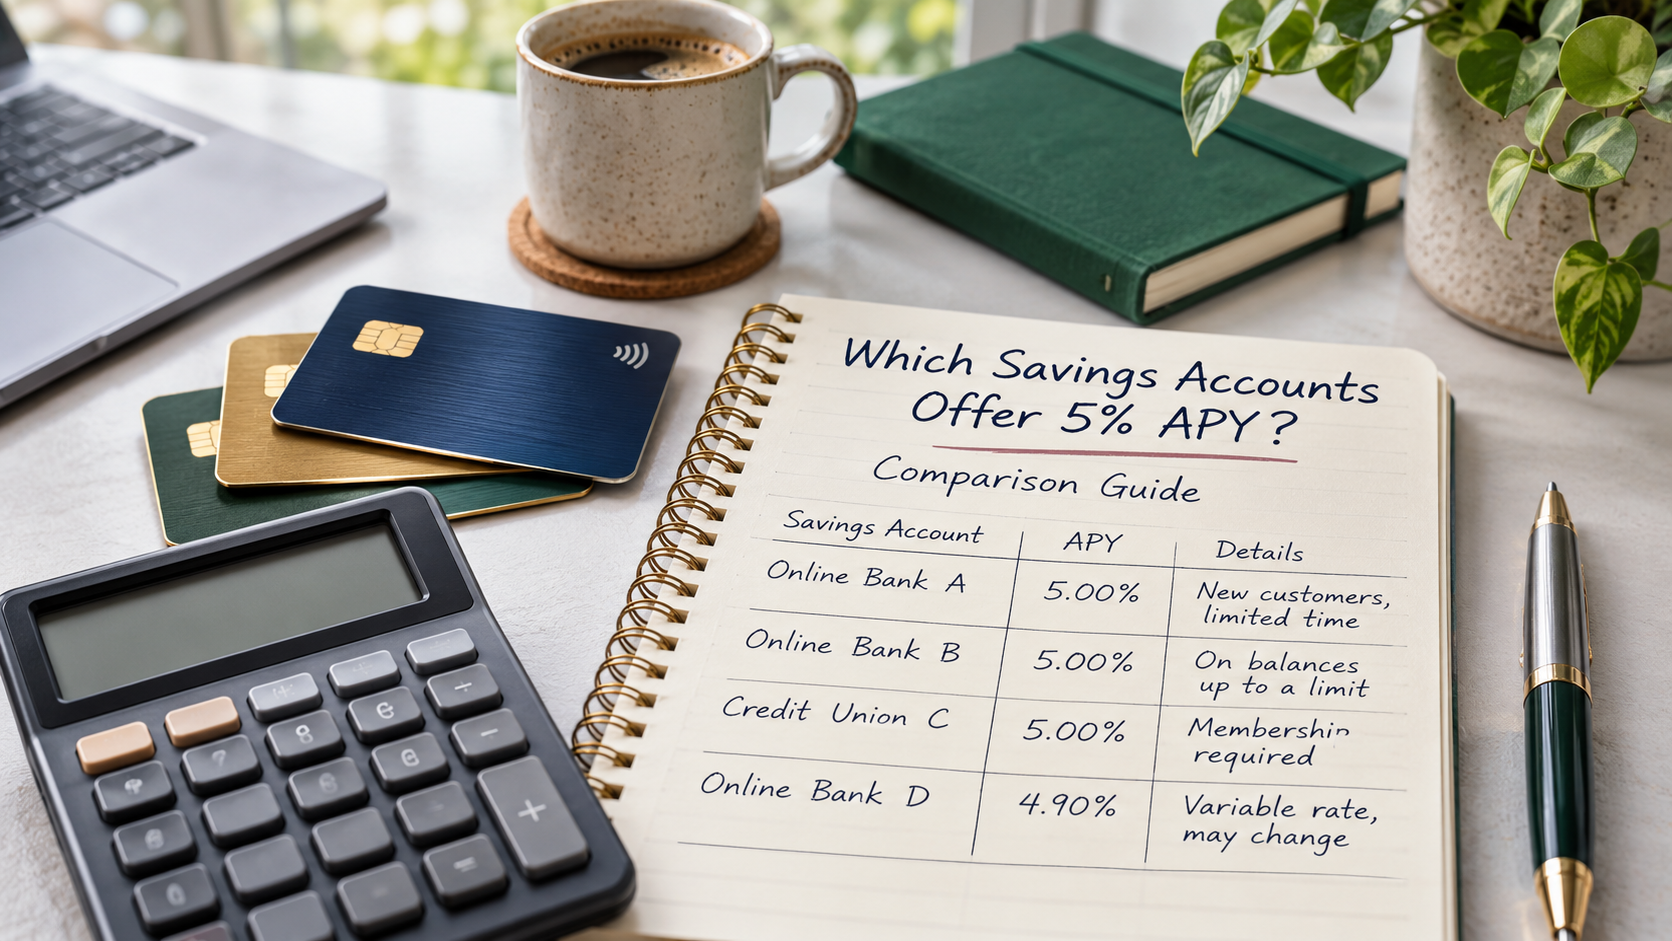
Finding a savings account that offers 5 percent APY can be appealing, but the headline rate is only one part of the comparison. High-yield savings account rates can change, some offers may be limited to new customers or a particular balance range, and a rate that is available today may not be available next month.
This guide explains how to evaluate accounts advertised near or at 5 percent APY, how to verify whether an offer is genuine, and how savings products fit alongside checking accounts, credit cards, debt repayment, insurance, and retirement planning. It does not identify a single account as permanently offering 5 percent because savings rates are generally variable and depend on the institution’s current terms.
What does 5 percent APY mean?
APY means annual percentage yield. It expresses the amount an account could earn over one year when interest is compounded, assuming the rate remains unchanged and the money stays in the account. A 5 percent APY is not the same as a 5 percent interest rate in every circumstance because compounding and account terms affect the final result.
For example, if $10,000 remained in an account for a full year at a constant 5 percent APY, the balance would be approximately $10,500 before taxes and assuming no fees, withdrawals, or changes to the rate. That illustration is not a promise of earnings. Variable-rate accounts can change their APY at the bank’s discretion, usually in response to broader interest-rate conditions.
APY also differs from a promotional annual percentage rate on a credit card. Credit card APR usually represents borrowing costs, while savings APY represents interest earned on deposits. Comparing them directly can lead to poor financial decisions.
Which savings accounts may offer 5 percent APY?
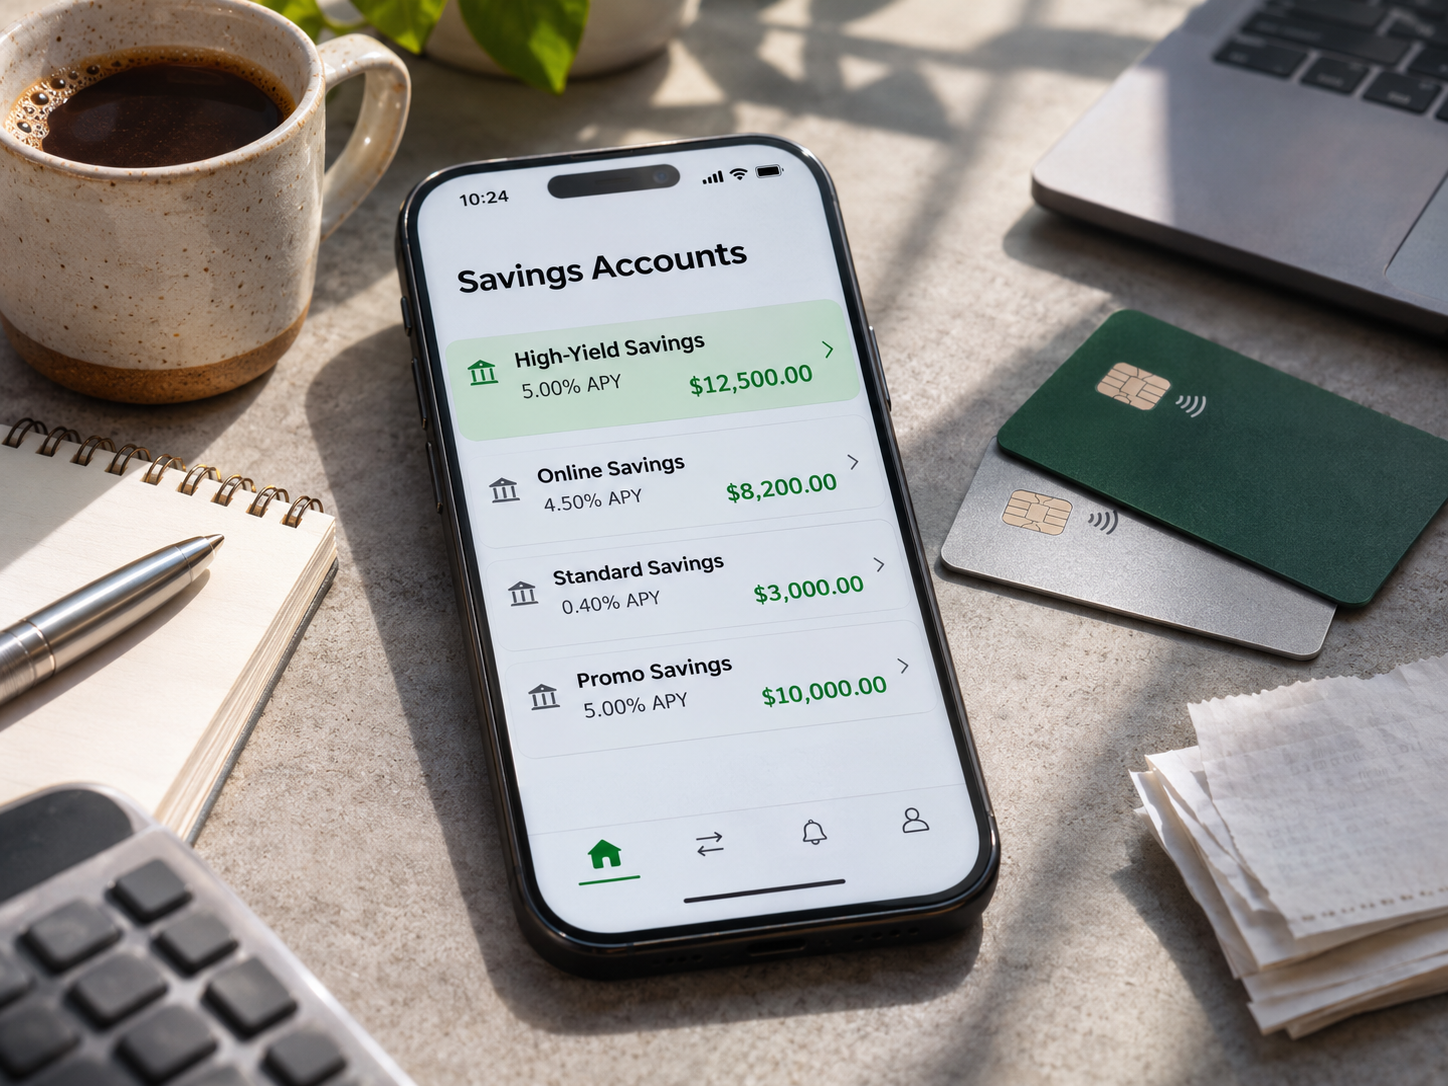
Accounts offering 5 percent APY, or rates close to it, generally fall into several categories. Availability changes frequently, so consumers should confirm the current disclosure, eligibility rules, and account agreement before opening an account.
1. Promotional high-yield savings accounts
Some banks and credit unions use a temporary promotional rate to attract new deposits. The offer may apply only to new customers, require a qualifying deposit, or expire after a stated period. A bonus may also be paid separately from the ongoing APY, which means the advertised first-year return may not continue.
Before relying on a promotional account, check the standard APY after the promotion ends, the length of the promotional period, minimum deposit requirements, and whether early withdrawal or account closure affects the bonus.
2. High-yield savings accounts with balance conditions
Some accounts advertise a high rate only on part of a balance or only when the balance stays below or above a specified threshold. Others may require recurring deposits, linked checking activity, electronic statements, or a minimum number of monthly transactions.
An account that offers 5 percent on the first $5,000 but a much lower rate above that amount may be less attractive than an account with a lower headline rate applied to the entire balance. The account’s tier schedule is therefore as important as its top APY.
3. Credit union savings products
Credit unions sometimes offer competitive deposit rates, but membership eligibility can apply. A credit union may also use the term dividend rate rather than interest rate. Compare the dividend APY, membership requirements, minimum balance, access methods, and deposit insurance coverage.
4. Money market deposit accounts
A money market deposit account can offer a competitive yield while providing certain checking-like features, such as limited check-writing or debit access. It is still important to distinguish a bank money market deposit account from a money market mutual fund. The former may be eligible for FDIC or NCUA insurance when held at an eligible institution; the latter is an investment product and is not a bank deposit.
5. Limited-time savings bonuses
Some institutions combine a relatively ordinary ongoing APY with a cash bonus. When comparing the total value, calculate the bonus separately and read the conditions. A bonus may require a large deposit, a long holding period, direct deposit, or a particular account relationship. A bonus should not be treated as a permanent 5 percent APY.
Where to research current high-yield savings rates
Rate tables are useful starting points, but they are not substitutes for the bank’s official terms. The following named sources provide comparison information and can help identify accounts worth investigating:
- Forbes Advisor’s Best High-Yield Savings Accounts reviews and compares selected savings products. Read the methodology, update date, and account-specific disclosures because rates and availability can change.
- Money’s Best High-Yield Savings Accounts provides another editorial comparison. Use it as a research source, then verify all terms directly with the institution.
- The Motley Fool’s savings-rate comparison page is another rate-tracking reference. Because the linked page is dated November 7, 2026, readers should confirm that date and review the institution’s current offer before acting.
These sources use editorial comparison methods that can differ. They may consider yield, fees, minimum deposits, access, customer service, and account features. A product appearing on a list is not a guarantee that it is the best choice for every saver.
How to compare accounts offering 5 percent APY
Step 1: Confirm the current APY
Look for the date on the comparison page and the bank’s own rate page. Search the account disclosure for language such as variable APY, introductory APY, or rates subject to change. If the rate is not shown clearly, contact the institution and ask whether the quoted rate applies to your balance and location.
Step 2: Check whether the rate applies to the full balance
Read the tiered-rate table. A 5 percent APY may be limited to a narrow balance range or may apply only after a qualifying action. Calculate the estimated interest on the amount you actually plan to deposit, rather than using the maximum advertised rate.
Step 3: Review fees and access rules
Check for monthly maintenance fees, excessive withdrawal fees, wire fees, expedited transfer fees, and minimum-balance charges. Also review how long transfers take, whether the account supports mobile check deposit, and whether customer service is available when you need it.
Federal rules and bank policies concerning savings-account withdrawals have changed over time, so do not assume every institution uses the same limit or fee policy. Read the current account agreement.
Step 4: Verify deposit insurance
For a bank, look for FDIC insurance. For a federally insured credit union, look for NCUA insurance. Coverage generally applies to eligible deposit accounts up to applicable legal limits and ownership categories, not to every product offered by a financial company. Confirm that the institution is insured and understand how accounts at the same bank are combined for coverage purposes.
Step 5: Compare the account with your existing bank
A separate high-yield savings account may earn more, but moving money can add administrative work. Consider whether you need instant access, branch service, ATM access, cash deposits, or a direct connection to your checking account. A slightly lower rate may be reasonable if it provides features that prevent missed bills or overdrafts.
Pros and cons of pursuing a 5 percent savings APY
Potential advantages
- Higher earnings: A higher APY can increase interest earned on emergency savings, a planned purchase, or short-term reserves.
- Lower investment risk: An insured deposit account is generally less exposed to market-price fluctuations than stocks or bond funds, although insurance conditions and limits apply.
- Simple access: High-yield savings accounts can be easier to understand and access than many investment products.
- Useful separation: A separate account can make it easier to organize money for taxes, home repairs, travel, or an emergency fund.
Potential disadvantages
- Variable rates: The APY can fall without the account balance changing, reducing future interest income.
- Restrictions: Promotional rates, balance tiers, transfer delays, and eligibility requirements may reduce the practical value of the offer.
- Taxable interest: Interest income is generally taxable, subject to applicable law and your personal circumstances.
- Limited growth potential: Cash accounts can be appropriate for short-term goals but may not provide the long-term growth potential associated with diversified investments.
- Operational inconvenience: An online-only account may not provide branches, cash deposits, or immediate access to funds.
When a high-yield savings account may not be the priority
Before moving money solely to earn a higher savings rate, address expensive debt. Paying down a credit card balance with a high interest rate may provide a more predictable financial benefit than earning interest on cash, although an emergency reserve should generally be considered before using all available savings to repay debt.
For borrowers considering personal loans or debt consolidation, compare the total cost, origination fees, repayment period, and variable or fixed rate. A lower monthly payment can still cost more overall if the repayment term is extended.
Likewise, compare checking account fees before opening a separate savings account. A savings account that pays more may not compensate for monthly fees, overdraft charges, or costly transfers in a linked checking account.
How savings fits into a broader personal finance comparison
A 5 percent APY comparison is one part of a wider financial plan. Use a budgeting calculator or spreadsheet to identify how much cash you need for fixed bills, irregular expenses, and emergencies. Keep money needed soon in an accessible account rather than choosing a product solely for its yield.
Credit card rewards should also be evaluated carefully. A rewards card may offer points or cash back, but interest charges can outweigh rewards when balances are carried. Paying the statement balance on time is usually more important than maximizing rewards.
For longer-term goals, compare retirement accounts and IRAs based on tax treatment, investment choices, contribution rules, and withdrawal restrictions. Cash in a savings account can support near-term stability, while retirement accounts are designed for longer time horizons.
Insurance comparisons matter as well. Reviewing car insurance and home insurance deductibles, exclusions, liability limits, and premiums may produce larger savings than switching bank accounts. Mortgage rate comparison should consider closing costs, points, loan term, and the total interest paid—not just the advertised rate.
Practical checklist before opening an account
- Write down the amount you plan to deposit and the date you may need the money.
- Confirm the current APY directly with the bank or credit union.
- Determine whether the APY is variable, promotional, tiered, or conditional.
- Check minimum deposits, minimum balances, monthly fees, and transfer policies.
- Verify FDIC or NCUA insurance and understand applicable coverage limits.
- Review the privacy policy, account agreement, and rate disclosure.
- Estimate interest using the rate that applies to your actual balance.
- Compare the account with debt repayment, checking needs, and other financial priorities.
- Set a reminder to review the rate after the promotional period or in several months.
Limitations of rate comparisons
Online comparison articles can become outdated because financial institutions change rates, eligibility standards, fees, and product availability. Editorial rankings may also use different criteria, and an account that is competitive for one balance may be less competitive for another. Search results and comparison tables should be treated as research aids, not personalized financial advice.
Questions and answers
Is a 5 percent APY savings account available to everyone?
Not necessarily. The offer may be limited by location, membership, balance, deposit size, promotional status, or customer eligibility. Confirm the terms with the institution.
Can a savings account keep paying 5 percent forever?
Usually, you should not assume that it will. Many high-yield savings accounts have variable rates, and promotional rates may expire. Review the ongoing APY and rate-change provisions.
Is a savings account safer than investing?
An eligible deposit account at an insured institution generally does not fluctuate in value like a market investment, within applicable insurance limits. It can still lose purchasing power to inflation, and insurance does not cover every financial product.
Should I move my entire emergency fund for a higher rate?
Only if the account provides suitable access, insurance, and terms. A small difference in yield may not justify transfer delays or loss of convenient banking features.
What should I do if the advertised APY is unavailable when I apply?
Ask the institution whether the offer ended, whether a condition was missed, or whether the rate is available only to a particular balance tier. Do not deposit money until you understand the applicable rate and account agreement.
Informational disclaimer: This article is for general education and is not individualized financial, tax, legal, or investment advice. Rates, fees, insurance rules, and tax treatment can change. Verify current terms with the financial institution and consider consulting a qualified professional about decisions affecting your money.
Leave a Reply