
When comparing personal loans, two terms often appear at different stages of the process: prequalification and formal application. They are related, but they are not interchangeable. Understanding the difference can help you compare borrowing costs, protect your credit profile, and avoid mistaking an estimated offer for a final approval.
This guide explains personal loan prequalification vs. formal application, including how credit checks work, what information lenders request, how offers may change, and when each step makes sense. It also covers debt-consolidation considerations, comparison methods, limitations, and common questions.
What Is Personal Loan Prequalification?
Personal loan prequalification is an initial screening process in which a lender estimates whether you may qualify for a loan and what terms might be available. You typically provide information such as your income, employment status, requested loan amount, housing payment, and the purpose of the loan. The lender may also ask for permission to review credit information.
Many lenders use a soft credit inquiry for prequalification. A soft inquiry generally does not affect your credit scores and is not visible to lenders in the same way as a hard inquiry. However, this is not universal. Some lenders may use a hard inquiry at an earlier stage, so read the lender’s disclosure before submitting information.
A prequalification result is usually an estimate, not a guarantee. The lender may have used information you entered rather than verified documents. Final terms can change after the lender confirms your income, identity, debts, employment, and credit history.
What Is a Formal Personal Loan Application?
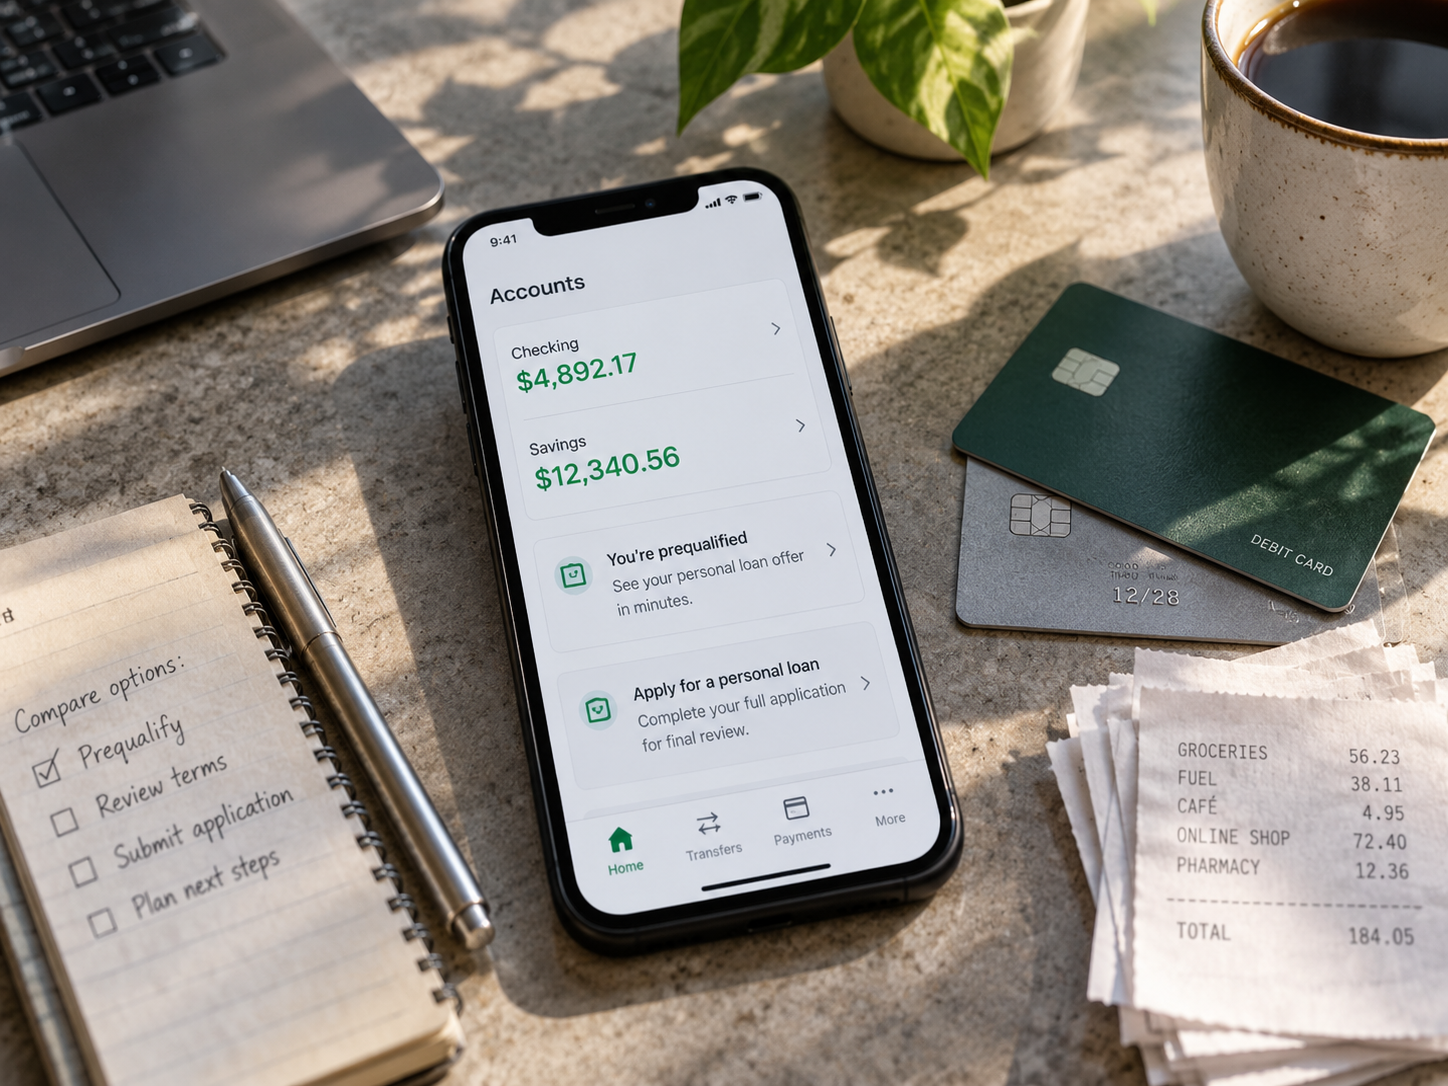
A formal personal loan application is the full request for credit that moves the process toward an approval decision and funding. It generally involves a more detailed review than prequalification. Depending on the lender and applicant, you may need to provide pay stubs, tax documents, bank statements, proof of address, identification, and permission to verify employment or other information.
A formal application commonly results in a hard credit inquiry. A hard inquiry is recorded on your credit report and can affect credit scoring models, although the impact is typically limited and may diminish over time. The lender then evaluates your complete application under its underwriting rules.
Formal approval may include conditions. For example, a lender might approve the loan only after receiving a specific document, confirming an account for debt payoff, or resolving an identity-verification issue. Even an approved application should be reviewed carefully before you accept the agreement.
Personal Loan Prequalification vs. Formal Application at a Glance
| Feature | Prequalification | Formal application |
|---|---|---|
| Primary purpose | Estimate eligibility and possible terms | Receive a final credit decision and proceed toward funding |
| Credit check | Often a soft inquiry, but lender practices vary | Usually a hard inquiry |
| Documentation | Usually limited self-reported information | More extensive verification is common |
| Terms | Estimated or conditional | More definitive, subject to the loan agreement and conditions |
| Commitment to borrow | None; you can normally stop comparing | Still not the same as accepting the loan, but the application advances underwriting |
How the Two Steps Work
1. Review your borrowing need
Before checking offers, decide why you need the money and how much is reasonably necessary. A personal loan may be used for a planned expense, an emergency, or debt consolidation. Borrowing more than needed increases the balance and may increase total interest, even if the monthly payment appears manageable.
For debt consolidation, list each debt, its balance, interest rate, minimum payment, and due date. Compare the proposed personal loan’s annual percentage rate, origination fee, repayment period, and total repayment with the existing debts. A lower monthly payment may result from a longer term rather than a lower overall cost.
2. Check your credit and budget
Review your credit reports for errors before seeking a loan. In the United States, consumers can use AnnualCreditReport.com, the federally authorized source for free credit reports. Credit-report information can affect lender decisions, but scoring models and lender requirements differ.
Use a budget or debt-payment calculator to test the proposed payment against your income and essential expenses. Include rent or mortgage payments, utilities, insurance, food, transportation, minimum debt payments, and savings. A loan payment that fits only when your budget is unusually favorable may be difficult to maintain.
3. Compare prequalification offers
Submit information only to lenders that clearly explain their credit-check policy and data practices. Compare offers using the same loan amount and repayment term where possible. Review the estimated APR range, monthly payment, origination fee, late-fee policy, prepayment policy, and whether the lender sends funds directly to creditors for consolidation.
Do not compare only the advertised interest rate. The APR can help account for certain interest and lender fees, but it may not include every potential cost. Read the lender’s disclosures and ask whether optional products, membership charges, insurance, or other fees are involved.
4. Choose whether to submit a formal application
After comparing estimates, select the lender whose verified terms, costs, and features best fit your circumstances. Before applying, confirm whether the lender will make a hard inquiry, what documents are needed, and whether the application expires.
Submit a formal application only when you are prepared for the lender to verify your information. Enter details accurately and consistently. Differences between your application and supporting documents can delay the decision or lead to different terms.
5. Review the final offer before accepting
Check the loan amount, APR, interest rate, payment amount, number of payments, origination fee, net proceeds, late fees, and total amount to be repaid. Confirm whether the rate is fixed and whether there is a prepayment penalty. If the loan is for consolidation, verify how and when creditors will be paid.
Never feel obligated to accept merely because you completed an application. Compare the final disclosure with the earlier estimate. If the terms are materially different, ask the lender why and decide whether the revised cost still fits your budget.
Advantages of Prequalification
- Lower initial credit impact: When a lender uses a soft inquiry, you can review potential offers without a hard inquiry.
- Efficient comparison: You can screen lenders before gathering extensive documentation.
- Better budgeting: Estimated payments can help you decide whether borrowing is realistic.
- Negotiation context: Multiple estimates may help you understand how credit, income, loan size, and term affect pricing.
Limitations of Prequalification
- It is not a promise: The lender may change or withdraw the offer after verification.
- Information may be incomplete: Self-reported income or debts may not match information found during underwriting.
- Rates are often personalized: A displayed range does not mean every applicant will qualify for the lowest rate.
- Inquiry policies differ: “No impact to your credit score” claims should be checked against the lender’s disclosures.
- Too many inquiries can create confusion: Even when prequalification uses soft inquiries, repeated applications and data sharing may make it harder to track which terms are current.
Advantages and Limitations of a Formal Application
Potential advantages
A formal application can produce a more reliable decision and a specific loan agreement. It may also reveal whether the lender can support the requested loan amount and repayment term after reviewing verified information. If you are ready to borrow, this is the step that generally allows funding to proceed.
Potential limitations
A formal application usually requires more time and documentation, and it commonly creates a hard inquiry. The final terms may be less favorable than the prequalified estimate. Approval is not guaranteed, and some lenders may decline the application if their underwriting review identifies insufficient income, high existing obligations, unverifiable information, or other risk factors.
How to Compare Lenders Responsibly
A useful comparison should evaluate the complete cost and the lender’s process, not just the lowest quoted rate. Record each lender’s name, date of estimate, loan amount, term, APR, monthly payment, estimated fees, funding time, credit-check type, and special conditions. This creates an audit trail when estimates change.
Use official lender disclosures and regulatory information as primary sources. The Consumer Financial Protection Bureau explains how personal installment loans, APRs, fees, and credit inquiries can work. The Federal Trade Commission provides consumer guidance on credit reports, scams, and identity protection. Credit bureaus such as Experian, Equifax, and TransUnion also explain the distinction between hard and soft inquiries, although their scoring information is educational rather than a guarantee of a lender’s decision.
Our comparison methodology is therefore based on five factors: total borrowing cost, transparency of fees, whether the credit inquiry is soft or hard, documentation and verification requirements, and practical repayment features. A lender should not rank highly merely because it displays a low starting rate that is unavailable to many applicants.
Credit Inquiries and Credit Score Considerations
A soft inquiry is generally associated with account reviews, promotional checks, or prequalification and does not normally affect your credit score. A hard inquiry usually occurs when you apply for credit and authorize a lender to review your report for an actual lending decision.
Credit-scoring treatment can vary by scoring model and by the type of credit. Some models may treat several inquiries for certain loan-shopping activities as a single rate-shopping event when they occur within a designated period. Do not assume this protection applies to every personal-loan application or every scoring model. Ask lenders how they check credit, and avoid submitting formal applications indiscriminately.
Improving credit before borrowing may help, but avoid tactics that promise an immediate score increase or require payment for disputing accurate information. Pay bills on time, reduce revolving balances when practical, check reports for errors, and apply for new credit selectively.
Related Financial Comparisons to Keep Separate
Personal loan decisions are one part of a broader personal-finance comparison. A high-yield savings account may be more appropriate for building an emergency reserve than borrowing for a predictable expense. When choosing a checking account, compare maintenance fees, overdraft policies, ATM access, and direct-deposit requirements. For credit cards and rewards, compare the annual fee, APR, rewards rules, and the cost of carrying a balance; rewards rarely offset interest charges.
Mortgage rate comparison and car insurance or home insurance comparison involve different underwriting standards, fees, and shopping periods. Retirement accounts and IRAs also have tax rules and investment risks that are not comparable to a personal loan. Treat each product as a separate decision rather than assuming one lender is best across every banking category.
Warning Signs to Watch For
- A company guarantees approval without reviewing your finances.
- You are asked to pay an upfront “processing,” “insurance,” or “release” fee before receiving a loan.
- The lender will not identify its legal business name, address, fees, or credit-check policy.
- You are pressured to provide banking credentials through an unverified link.
- The offer requires unusual payment methods, such as gift cards or cryptocurrency.
- The lender asks you to misstate income, employment, or debts.
Verify the lender independently through official regulatory resources and use a secure website. Be cautious about sharing sensitive information until you understand who is collecting it and why.
Concise Q&A
Does prequalification guarantee a personal loan?
No. It is an estimate based on preliminary information. Final approval and terms generally depend on identity, income, debts, credit history, and other verified details.
Does prequalification hurt your credit?
Often it does not when the lender uses a soft inquiry, but practices vary. Confirm the inquiry type before submitting the request.
Is a formal application the same as loan acceptance?
No. A formal application requests an underwriting decision. You should review and accept the final loan agreement only if its terms fit your needs.
Should I prequalify with several lenders?
Comparing several lenders can be useful, especially when prequalification uses soft inquiries. Limit formal applications and compare each lender’s inquiry policy, fees, and total repayment cost.
Can a personal loan help consolidate debt?
It can, but only if the new loan’s total cost and repayment structure improve your situation and you avoid rebuilding the consolidated balances. Compare APR, fees, term, and total payments rather than focusing only on the new monthly payment.
Bottom Line
Prequalification is a preliminary comparison tool; a formal application is the verified underwriting step that may lead to funding. Start with a realistic budget, review your credit reports, compare complete costs, confirm whether each inquiry is soft or hard, and treat every prequalified offer as conditional. Before accepting a loan, read the agreement and make sure the payment, fees, and repayment period are sustainable.
Informational disclaimer: This article is for general education and is not financial, legal, tax, or credit advice. Loan availability, fees, credit-check practices, and approval criteria vary by lender and location. Review current disclosures and consider advice from a qualified professional before borrowing.
Leave a Reply