Irregular expenses are one of the main reasons a monthly budget can look balanced while your bank balance still feels unpredictable. Annual insurance premiums, car repairs, medical bills, school costs, gifts, and home maintenance may not arrive every month, but they still belong in your financial plan. The right budget spreadsheet categories for irregular expenses help you turn occasional bills into manageable monthly amounts.
This guide explains how to design those categories, compare different spreadsheet methods, and connect your expense plan with other personal finance tools such as high-yield savings accounts, checking accounts, credit cards, insurance comparisons, and debt repayment calculators. It is educational information, not individualized financial, tax, legal, or investment advice. Review account terms and consider speaking with a qualified professional before making decisions that could materially affect your finances.
What are budget spreadsheet categories for irregular expenses?
Budget spreadsheet categories for irregular expenses are labels and tracking fields used to record costs that are unpredictable, seasonal, annual, or infrequent. Instead of treating a $1,200 insurance premium as a surprise in the month it is due, a spreadsheet can assign it to a category such as Auto Insurance and set aside a portion of the expected annual cost each month.
A useful category does more than describe the purchase. It should help answer four questions:
- What is the expense? For example, vehicle maintenance, dental care, or holiday gifts.
- When might it occur? Record a due month, likely season, or a range of possible dates.
- How much should be reserved? Use a known bill, a documented estimate, or a conservative planning amount.
- Where will the money come from? Link the category to checking, savings, a sinking fund, or another planned source.
These categories are sometimes called sinking funds, reserve categories, annual expenses, or nonmonthly expenses. The names differ, but the purpose is similar: make uneven cash flow visible before a bill arrives.
Why irregular expenses deserve separate categories
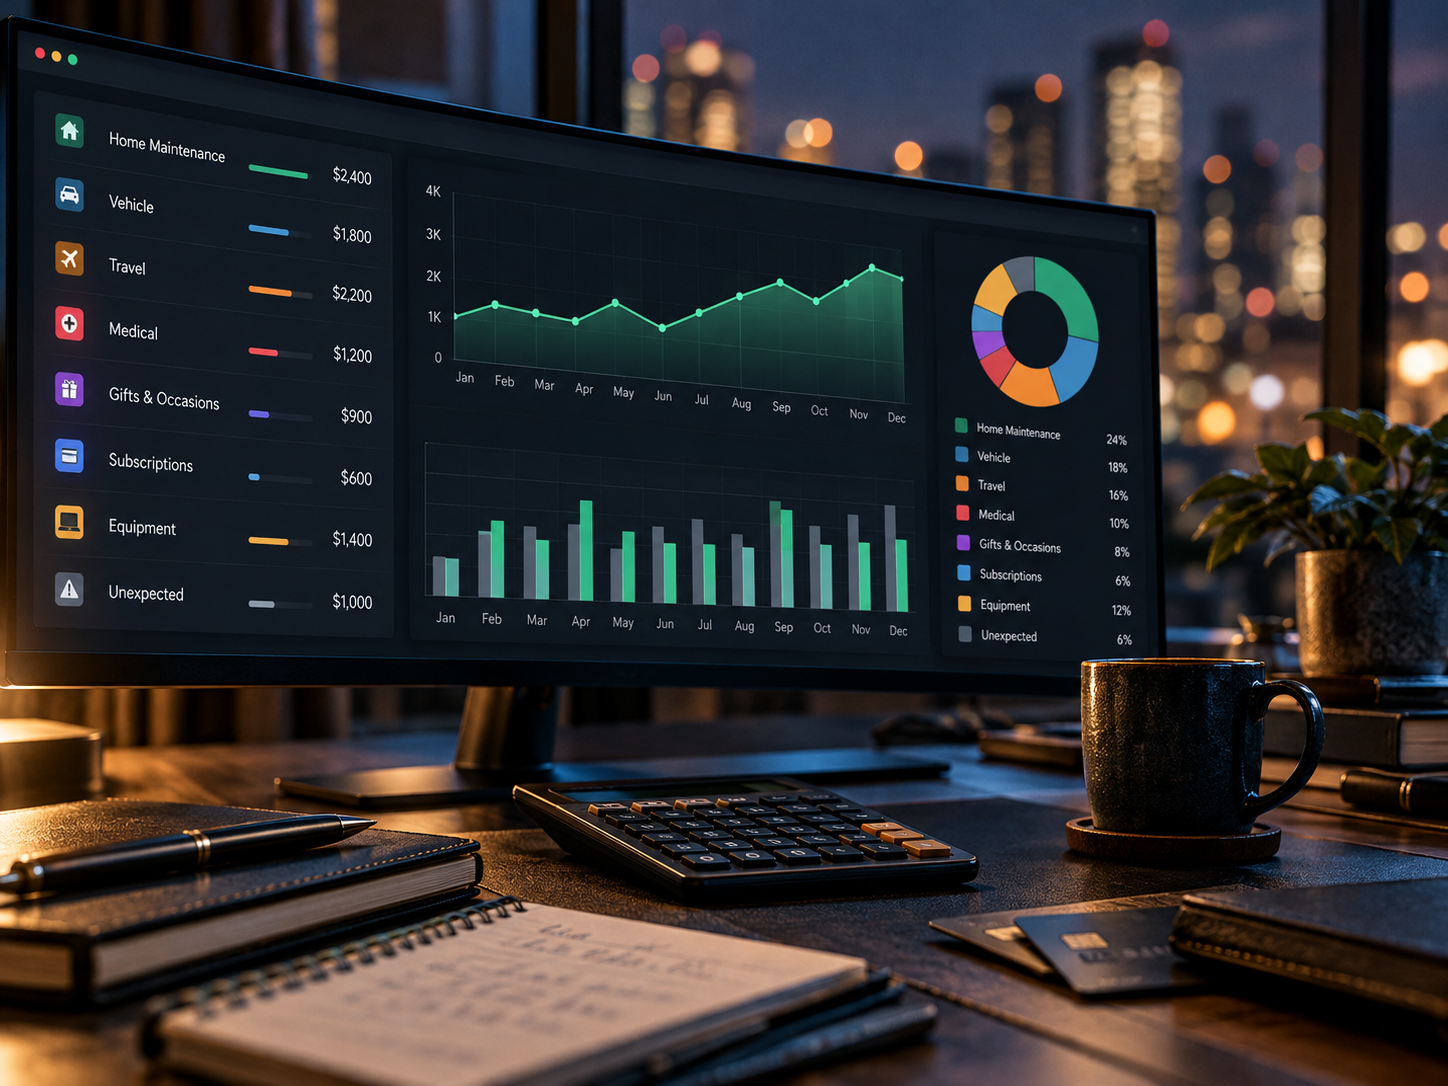
Combining all occasional spending into a single line called miscellaneous may make a spreadsheet look simple, but it limits its usefulness. A large repair, a yearly subscription, and a family celebration may require different timing and different levels of preparation.
Separate categories can help you:
- Distinguish unavoidable bills from optional spending.
- Identify expenses that could be reduced through comparison shopping.
- Prevent annual bills from distorting a single month’s budget.
- See whether a cash reserve is adequate for a likely repair or deductible.
- Compare planned spending with actual spending over time.
They also make product comparisons more meaningful. For example, a lower checking account fee may matter if your cash is frequently moved between accounts. A high-yield savings account may be useful for money reserved for future expenses, provided you understand its variable interest rate, access rules, and account protections. A rewards credit card may offer value only when the balance is paid as agreed; rewards should not be treated as a substitute for cash reserves.
A practical category structure
The best structure depends on your household, but a layered system usually works better than a long, unorganized list. Start with broad groups, then add subcategories only when the detail improves a decision.
1. Annual or semiannual bills
These expenses often have a known schedule and can be divided by the number of months until the next payment. Common examples include:
- Auto insurance
- Homeowners or renters insurance
- Property taxes, where not included in an escrow payment
- Professional memberships
- Software, cloud storage, or other subscriptions
- School tuition, fees, or activity costs
Use the actual renewal notice when available. If the amount may change, note that the monthly reserve is an estimate rather than a guarantee.
2. Maintenance and replacement reserves
Maintenance is irregular because the timing is uncertain, even when the need is predictable. Consider categories such as:
- Vehicle maintenance and tires
- Home repairs and appliances
- Computer or phone replacement
- Furniture replacement
- Pet care beyond routine visits
For items with different expected lifespans, separate categories may be more informative. A car repair fund and a laptop replacement fund have different urgency, costs, and planning horizons.
3. Health and personal care
Health-related costs can be difficult to forecast. Possible categories include deductibles, copayments, prescriptions, dental care, vision care, therapy, and medical travel. Do not assume that an insurance plan will cover every service or that an advertised premium represents your total cost. Compare premiums, deductibles, coinsurance, exclusions, provider networks, and out-of-pocket limits using the plan documents.
4. Family, gifts, and seasonal spending
Birthdays, holidays, weddings, charitable contributions, school events, and travel may be optional in a strict sense but still important to a household. A dedicated category makes it easier to set a limit without relying on a credit card when the date arrives.
5. Taxes and work-related costs
Self-employment taxes, tax preparation, licensing, uniforms, continuing education, and professional travel can be irregular. Tax treatment varies by situation, so a spreadsheet should not be used as proof that an expense is deductible. Consult current guidance from the Internal Revenue Service or a tax professional when tax treatment matters.
Core spreadsheet columns to include
A basic spreadsheet can track more than the budgeted amount. The following columns make the plan easier to review:
- Category: A specific label, such as Home Insurance or Dental Care.
- Expense type: Annual bill, maintenance, seasonal, discretionary, or emergency reserve.
- Expected due date: Use a month or a date range when the exact date is unknown.
- Estimated annual cost: Enter the known bill or a documented planning estimate.
- Monthly target: Divide the amount by the months available to save.
- Amount reserved: Record actual transfers or allocations.
- Amount spent: Record payments made from the category.
- Balance remaining: Show what is available for that purpose.
- Source or note: Identify a bill, renewal notice, policy document, receipt, or assumption.
A simple formula for a known annual expense is:
Monthly target = expected annual cost divided by months until the next payment
For example, if a bill is expected once a year, the monthly target is generally the annual amount divided by twelve when planning starts at the beginning of the cycle. If the payment is only a few months away, divide by the number of months remaining instead. This prevents an artificially low contribution from understating the short-term need.
How to build the categories step by step
Step 1: Review a full year of transactions
Download statements from your checking account, savings account, and credit cards. Search for large or unusual payments, even if they were coded as ordinary purchases. A calendar view can reveal seasonal patterns that a monthly budget misses.
Do not rely exclusively on automatic transaction categories. Bank and card classifications can be wrong, particularly for mixed retailers, medical providers, subscriptions, and peer-to-peer payments. Confirm important items against statements and receipts.
Step 2: Separate predictable irregular costs from true emergencies
An annual premium is irregular but predictable. A major natural disaster, sudden job loss, or serious uninsured event may be an emergency. Keep these concepts separate. A sinking fund for vehicle maintenance should not be counted as a complete emergency fund, because it may already be committed to the car.
Step 3: Estimate using evidence and ranges
Use renewal notices, prior invoices, current policy documents, service quotes, and recent spending history. When uncertainty is high, record a low and high estimate rather than presenting one number as certain. You can then choose a planning target that fits your cash flow.
Step 4: Choose the funding schedule
Most people use a monthly transfer, but a weekly or per-paycheck schedule may be easier to maintain. If income changes throughout the year, you can use a base contribution plus extra deposits during stronger months. Keep the schedule realistic; an amount that cannot be funded consistently will not solve the timing problem.
Step 5: Match each category to an account or envelope
You might keep several digital subcategories within one savings account, use separate savings accounts, or track everything in a spreadsheet while holding the cash in one account. The method matters less than clear records and sufficient liquidity.
When comparing savings accounts, verify the annual percentage yield, minimum balance rules, withdrawal or transfer conditions, fees, and deposit insurance information. The Federal Deposit Insurance Corporation, or FDIC, provides consumer information about deposit insurance for eligible deposits at member banks. Credit unions have a separate federal insurance system administered by the National Credit Union Administration for eligible accounts. Confirm the institution and account type rather than assuming every financial product has the same protection.
Step 6: Reconcile monthly
At month-end, compare the spreadsheet with bank and card statements. Record transfers, payments, refunds, and changes to expected bills. If a category repeatedly runs short, update the estimate or investigate whether the purchase belongs elsewhere.
Comparing different spreadsheet methods
Single irregular-expense category
Pros: Fast to set up and easy to maintain.
Cons: It hides which expenses are driving the total and makes timing difficult to manage.
This approach can work for a very small budget with few annual bills, but it becomes less useful as obligations grow.
Detailed sinking-fund categories
Pros: Provides visibility, supports specific savings targets, and makes shortfalls easier to diagnose.
Cons: Requires more maintenance and may create too many categories for a simple financial situation.
This is often the best fit when you have multiple annual bills, variable maintenance costs, or goals with different deadlines.
Cash-flow calendar
A cash-flow calendar places expected income and payments on a timeline.
Pros: Shows whether money will be available when a bill is due and can reveal timing problems even when monthly income exceeds expenses.
Cons: It may require more frequent updates when dates or income change.
A calendar can complement, rather than replace, category tracking.
App or automated budgeting tool
Pros: May import transactions, automate transfers, and provide notifications.
Cons: Features, privacy practices, subscription costs, and transaction classifications vary. An automated label can still be incorrect.
Before connecting financial accounts, review the provider’s data access terms and security practices. A spreadsheet stored locally may offer more control, while a cloud tool may offer greater convenience.
Connecting irregular-expense planning with financial comparisons
Category data can improve decisions across several personal finance products.
Credit cards and rewards
Compare annual fees, interest rates, rewards rules, redemption restrictions, foreign transaction fees, and introductory terms. A card may fit a planned expense only if the purchase is already funded and the balance can be paid according to the account terms. Do not increase spending to earn rewards.
High-yield savings accounts
For reserves needed within the near term, liquidity and account protections may matter more than chasing a small difference in yield. Compare the current yield, rate-change policy, transfer speed, minimums, fees, and insurance status. The Consumer Financial Protection Bureau offers consumer guidance on deposit accounts and common banking issues.
Checking account fees
Review monthly maintenance fees, overdraft practices, minimum balance requirements, out-of-network ATM charges, wire fees, and direct-deposit conditions. A no-fee account may still have other charges, so compare the complete fee schedule.
Personal loans and debt consolidation
Do not classify a new loan as a solution to an irregular expense without comparing total repayment cost, origination fees, term length, interest rate, and the risk of using secured collateral. Consolidation can simplify payments but may increase total interest or extend the repayment period.
Mortgage rates, insurance, and retirement accounts
Mortgage comparison should consider the annual percentage rate, lender fees, points, term, and estimated closing costs rather than the headline rate alone. For auto and home insurance, compare coverage limits, deductibles, exclusions, claims service, and premium—not price alone.
Retirement accounts and IRAs generally serve long-term goals and should not automatically be used as a substitute for a short-term irregular-expense reserve. Contribution rules, tax treatment, withdrawal restrictions, and investment risks vary. The IRS publishes current information about retirement plans and IRAs, which should be checked before relying on a tax assumption.
Limitations and common mistakes
- Estimates can be wrong: Repairs, premiums, and medical bills may exceed prior costs.
- Inflation and price changes matter: An old bill may not reflect the next renewal.
- Cash location can be confusing: A spreadsheet balance is not the same as money available if transfers are pending or funds are commingled.
- Double counting is possible: Do not count escrowed property taxes, employer benefits, or automatic bill payments both as savings goals and as separate expenses.
- Credit is not cash: A credit limit may cover a bill temporarily, but repayment still creates a future obligation.
- Automation needs review: Transfers can fail because of insufficient funds, account changes, or incorrect dates.
For larger or uncertain obligations, use a range, review the plan more frequently, and maintain a separate emergency reserve where possible. If your budget is consistently negative, category refinement alone will not solve the problem; you may need to reduce expenses, increase income, renegotiate obligations, or seek qualified debt counseling.
Concise Q&A
Should every irregular expense have its own category?
No. Create a separate category when the amount, timing, or importance would affect a decision. Combine small, similar items when detail would add work without improving control.
How much should I save for an expense with no fixed due date?
Use recent records, service guidance, policy documents, and a reasonable range. If the timing is uncertain, prioritize a reserve that reflects the potential consequence of waiting.
Is a sinking fund the same as an emergency fund?
No. A sinking fund is reserved for an expected purpose, while an emergency fund is generally intended for unexpected financial shocks. Keeping them separate improves clarity.
Can I use a credit card for an annual bill?
Yes, if the bill is already funded and the card terms are understood. Avoid carrying a balance solely to earn rewards, because interest and fees can outweigh the benefit.
How often should the spreadsheet be updated?
Reconcile it at least monthly and review annual assumptions when policies renew, prices change, or household circumstances shift.
Bottom line
A strong spreadsheet for irregular expenses is less about finding a perfect template and more about making timing, purpose, and funding visible. Start with a year of transaction history, create practical categories, estimate costs using documented evidence, divide goals across the time available, and reconcile the results regularly. Then use the information to compare savings, banking, credit, insurance, debt, and retirement products based on total cost, access, risk, and suitability—not on a single advertised feature.
Financial products and account terms change. Check current disclosures from providers and authoritative sources such as the Consumer Financial Protection Bureau, FDIC, and Internal Revenue Service before acting.
Leave a Reply