Author: Christine

  • When Are High-Yield Savings Accounts Taxed? A Practical Guide to Interest Income

    When Are High-Yield Savings Accounts Taxed? A Practical Guide to Interest Income

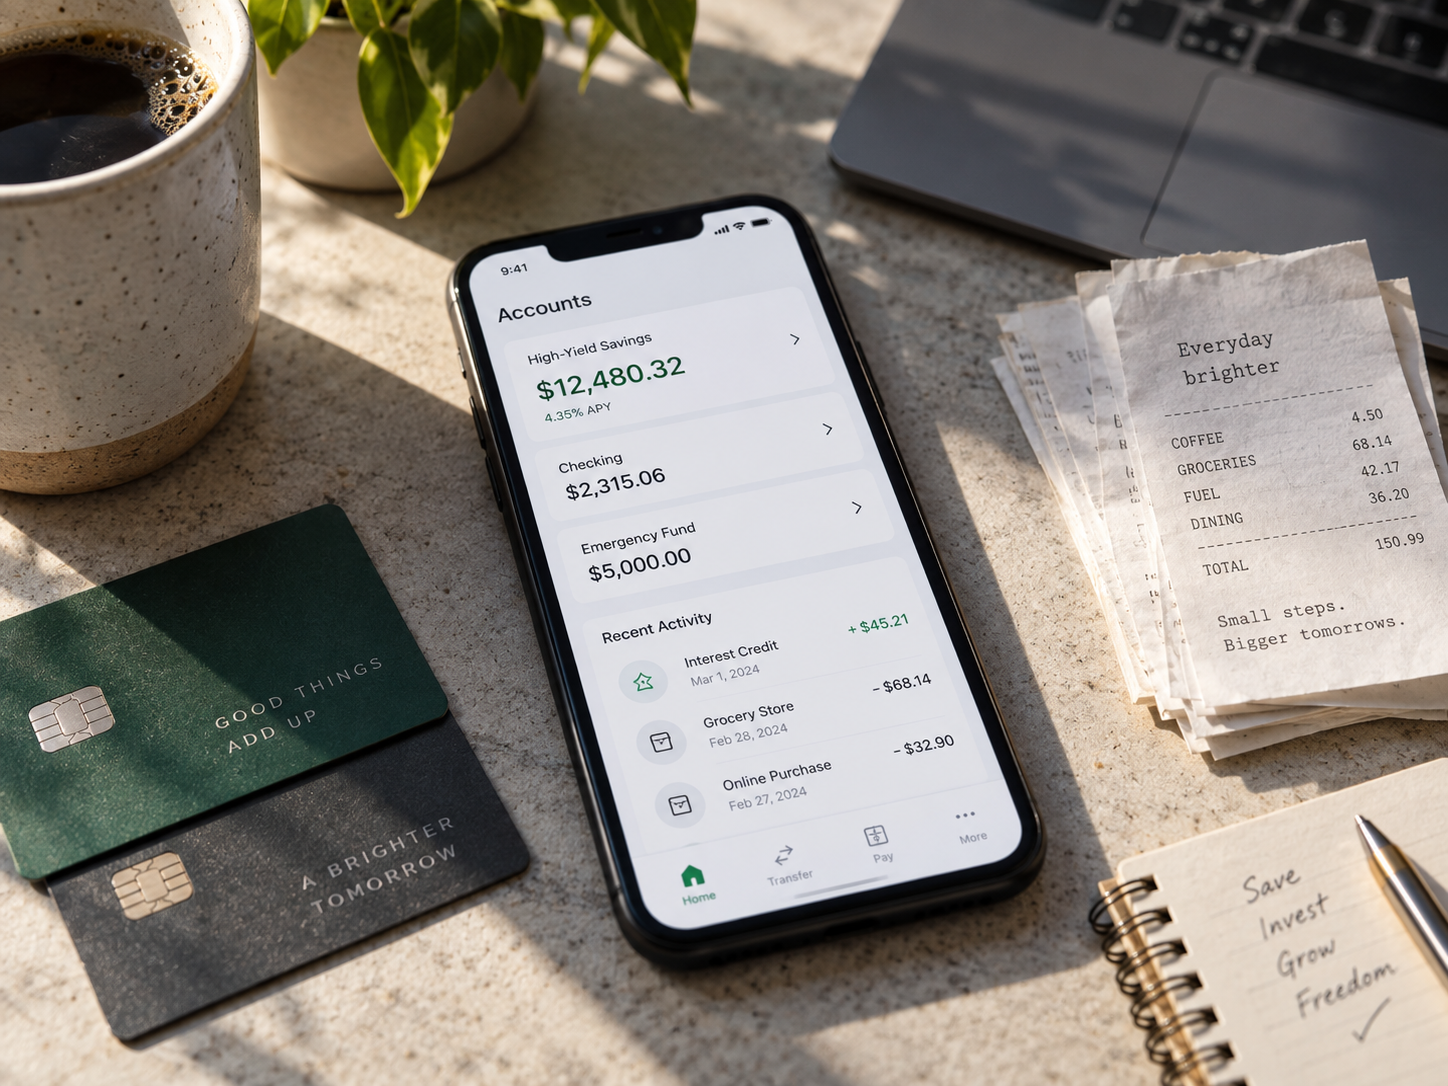
    High-yield savings accounts can earn more interest than many traditional savings accounts, but the interest is usually taxable income. Understanding when the tax applies helps you compare banking products accurately, estimate your after-tax return, and avoid surprises when you prepare your tax return.

    The short answer is that interest from a high-yield savings account is generally taxed in the year it is paid or made available to you, even if you leave the money in the account. You usually do not wait until you withdraw the interest. Your bank may report the interest on Form 1099-INT, but you are responsible for reporting taxable interest whether or not you receive that form.

    What Is a High-Yield Savings Account?

    A high-yield savings account is a deposit account that pays interest on money you keep at a bank or credit union. The account may be offered by an online bank, a traditional bank, or a credit union. Its interest rate is often variable, which means the institution can change it over time.

    The term “high-yield” describes the account’s relative interest rate, not a special tax treatment. For federal income tax purposes, interest from a high-yield savings account is generally treated like interest from other taxable bank deposit accounts.

    Interest may be calculated daily and credited monthly, quarterly, or on another schedule. The calculation method and crediting schedule can affect when the interest becomes available, but the account agreement and the bank’s tax reporting determine the details. Review both your periodic statements and year-end tax documents.

    When Are High-Yield Savings Accounts Taxed?
    What Is a High-Yield Savings Account?
    What Is a High-Yield Savings Account?

    Strictly speaking, the account balance itself is not taxed merely because it is held in a high-yield savings account. The taxable item is generally the interest income generated by the account. That interest is usually included in your taxable income for the tax year in which it is paid or made available to you.

    Interest is generally taxed when credited

    If a bank credits interest to your account during the year and you can use or withdraw it, the interest is generally taxable for that year. You do not normally postpone the tax by leaving the interest in the account, transferring it to another savings account, or allowing it to compound.

    For example, suppose a bank credits $80 of interest to your account in December. You leave the $80 in the account and do not withdraw it. The $80 will generally still be taxable interest for that tax year because it was credited and available to you.

    Interest is generally not taxed when you deposit principal

    Depositing your paycheck, an inheritance, money from another bank account, or other after-tax funds into a savings account does not usually create taxable interest income by itself. The tax issue generally begins with the new interest earned on the deposit, not with the return of money you already owned.

    Withdrawals usually do not create a second tax

    Withdrawing money that consists of your original deposits generally does not create a new tax event. Withdrawing accumulated interest also does not usually create a second tax if that interest was already reported for the year in which it was credited. The timing of the tax usually follows the interest income, not the later withdrawal.

    How the IRS Treats Savings Account Interest

    The Internal Revenue Service generally treats bank interest as taxable interest income unless a specific exclusion applies. The IRS explains the rules in Publication 550, Investment Income and Expenses. That publication covers interest, dividends, and other investment income, including reporting principles relevant to deposit interest.

    Many banks report interest on Form 1099-INT when the amount meets the applicable reporting threshold. The form normally shows taxable interest in Box 1. The reporting threshold does not determine whether interest is taxable. In other words, a small amount of interest may still need to be reported even if the bank does not send you a form.

    Use the information from your bank’s tax documents, but also compare it with your statements. If you changed banks during the year, you may receive forms from multiple institutions. A joint account can also require coordination between account owners so that the interest is reported by the person who is legally and beneficially entitled to it under applicable tax rules.

    Where to Report the Interest

    For many taxpayers, taxable savings account interest is reported on Form 1040 or Form 1040-SR through the interest income section. Tax software generally imports Form 1099-INT information or asks you to enter the amount manually.

    Schedule B, Interest and Ordinary Dividends, may be required in certain circumstances, such as when your taxable interest or ordinary dividends exceed the applicable filing threshold or when other Schedule B conditions apply. Tax forms and thresholds can change, so use the instructions for the tax year being filed.

    If your bank’s form contains an error, contact the institution and request a corrected form. Do not simply omit the interest because the document appears inaccurate. Keep statements, tax forms, and correspondence that help establish the correct amount.

    Are High-Yield Savings Accounts Taxed by the State?

    Federal tax is only part of the analysis. Most states that impose an individual income tax generally include taxable bank interest in state income, although state rules and deductions vary. Some states do not impose a broad individual income tax, while others may apply different treatment to particular types of income.

    Your state of residence, filing status, and the state rules for the tax year can affect the result. If you moved during the year, maintained accounts while living in more than one state, or have a complex ownership arrangement, review the relevant state instructions or consult a qualified tax professional.

    Special Situations to Watch

    Bank account bonuses

    A cash bonus for opening or funding a bank account is often taxable income, even when it is described as a reward. The bank may issue Form 1099-INT or another information return depending on how it classifies the payment. Read the offer terms and tax form carefully rather than assuming that a bonus is tax-free.

    Interest credited at year-end

    Year-end interest can create timing confusion. An amount credited in December may be taxable in that year even if the statement arrives in January or the bank’s tax form is not delivered until later. Conversely, interest credited in January is generally associated with the new tax year.

    Closed accounts

    Closing a high-yield savings account does not eliminate the need to report interest earned before closure. The bank may issue a tax form after the account is closed. Keep your final statement and watch for tax documents from former institutions.

    Trusts, businesses, and custodial accounts

    Accounts held by a trust, business, estate, or custodial arrangement may follow different reporting rules. The account holder shown on the records may not be the person who ultimately reports the income. These arrangements are worth reviewing with a tax professional, especially when the account is used for a child, a deceased person’s estate, or a business.

    Tax-advantaged accounts

    A regular high-yield savings account should not be confused with a retirement account or another tax-advantaged account. Interest inside an IRA, for example, is subject to the rules governing that IRA rather than the ordinary reporting pattern for a taxable bank account. Moving cash into an account with a different tax structure can have contribution, withdrawal, and eligibility consequences.

    How to Estimate the After-Tax Return

    Comparing only the advertised interest rate can give an incomplete picture. A simple estimate of after-tax interest is:

    Estimated after-tax interest = interest earned × (1 − marginal tax rate)

    For example, if an account earns $500 and your combined marginal federal and state rate is estimated at 25%, the rough after-tax amount would be $375. This is an estimate, not a tax calculation. Your effective tax rate, deductions, credits, filing status, and state rules may produce a different result.

    When comparing accounts, consider the annual percentage yield, minimum balance, monthly maintenance fee, withdrawal restrictions, transfer speed, deposit insurance, and rate history or variability. A slightly lower rate with no fee may produce a better result than a higher rate attached to a fee or a balance requirement.

    Banking product comparisons should also separate taxable yield from account safety. Deposits at an FDIC-insured bank are generally covered within applicable ownership and coverage limits. Eligible deposits at a federally insured credit union may instead be covered by the National Credit Union Administration. Confirm the institution’s insurance status and understand the limits rather than assuming every cash platform has deposit insurance.

    Practical Steps Before Filing Your Taxes

    1. List every institution. Include current accounts, accounts closed during the year, online banks, credit unions, and accounts opened late in the year.
    2. Collect Form 1099-INT documents. Check your bank’s online tax-document center and mail. Some institutions provide a combined form for several accounts.
    3. Compare forms with statements. Look for interest credited near the end of the year and verify that totals are not duplicated.
    4. Report taxable interest. Enter the amount in your tax software or on the appropriate federal tax form, even when the amount is below the bank’s form-reporting threshold.
    5. Review state treatment. Follow the instructions for every state return you must file.
    6. Check bonuses and promotional payments. Do not overlook account-opening bonuses or other payments listed separately from regular interest.
    7. Keep records. Retain statements and tax forms according to your normal record-retention practice in case you need to reconcile a correction or amended return.

    Pros and Cons of High-Yield Savings Accounts

    Potential advantages

    • They can provide a competitive place for emergency funds, short-term goals, and cash that should remain accessible.
    • They generally have less price volatility than investments such as stocks or bond funds.
    • Interest may compound automatically when credited to the account.
    • Online account management can make it easy to compare rates and move money.

    Potential disadvantages

    • Interest is generally taxable in a regular account, reducing the return after taxes.
    • The rate can fall, so today’s yield is not a guaranteed long-term return.
    • Transfers may take time, which can matter during an emergency.
    • Some accounts have balance requirements, limited transaction features, or fees.
    • Inflation can reduce the purchasing power of the balance even when the nominal account value rises.

    Limitations of This Comparison

    The tax treatment described here is a general guide for ordinary personal accounts held in the United States. It does not calculate your individual tax liability or determine how a particular trust, business, estate, retirement account, foreign account, community-property arrangement, or state return should be handled.

    Rates, fees, insurance coverage, account terms, and tax rules can change. A rate comparison is also only a snapshot because banks can change variable yields. For a complete personal finance comparison, evaluate the account’s current disclosures, deposit insurance, access features, and after-tax return alongside your savings goal.

    Q&A

    Do I pay tax on interest I leave in the account?

    Usually, yes. If the bank credits the interest and makes it available to you, leaving it in the account generally does not defer the tax.

    Is a high-yield savings account itself taxable?

    Usually, the principal balance is not taxed merely because it is in the account. The interest earned is generally the taxable item.

    What if I earned only a few dollars?

    Small amounts can still be taxable even when the bank does not issue Form 1099-INT. Use the applicable tax instructions and keep your statements.

    Are bank bonuses taxable?

    Often, yes. The reporting document and tax treatment depend on the payment, so review the bank’s form and offer terms.

    Does withdrawing the interest trigger tax?

    Generally, no second tax is created by the withdrawal if the interest was already taxable when credited. The key event is usually when the interest became available.

    Which source explains the federal rules?

    IRS Publication 550, Investment Income and Expenses, is a useful primary source. The IRS Form 1099-INT information page explains the information return used for many interest payments. Always use the instructions for the specific tax year.

    Informational disclaimer: This article is for general educational purposes and is not tax, legal, investment, or financial advice. Tax treatment depends on individual facts and can change. Confirm current federal and state rules with the IRS, your state tax agency, or a qualified tax professional before filing or making a financial decision.
  • Why a High-Yield Savings Account May Fit Your Financial Plan

    Why a High-Yield Savings Account May Fit Your Financial Plan

    Many people search for “why high yield savings account” when they want their cash to earn more interest without taking stock-market risk. A high-yield savings account, often called a HYSA, is a deposit account that generally offers a higher annual percentage yield (APY) than a standard savings account. It can be useful for an emergency fund, a planned purchase, or cash that you may need within the next few years.

    However, a higher advertised yield does not automatically make an account the best choice. The APY can change, withdrawals may be limited or discouraged, and some accounts require online banking or electronic transfers. This guide explains how these accounts work, how to compare them with other banking products, and what limitations to consider before opening one.

    What Is a High-Yield Savings Account?

    A high-yield savings account is a savings account designed to pay a comparatively competitive interest rate on deposited money. The account usually earns interest through a variable APY, meaning the bank or credit union can change the rate as market conditions and its own pricing decisions change.

    Unlike an investment account, a savings account is not intended to rise and fall with stock or bond prices. When held at an eligible institution, deposits may be protected by federal deposit insurance within applicable limits. The Federal Deposit Insurance Corporation (FDIC) generally insures eligible deposits at FDIC-member banks up to the standard maximum amount per depositor, per insured bank, for each ownership category. The National Credit Union Administration (NCUA) provides similar coverage for eligible deposits at federally insured credit unions.

    Deposit insurance protects against the failure of a covered institution; it does not guarantee a particular interest rate or protect against inflation. Before depositing money, verify the institution’s insurance status and review how the account is titled.

    Why Use a High-Yield Savings Account?

    What Is a High-Yield Savings Account?
    What Is a High-Yield Savings Account?

    1. It can improve the return on accessible cash

    The main reason to consider a HYSA is the possibility of earning more interest while keeping the money relatively accessible. A traditional savings account may offer a lower APY, while a high-yield account may be priced more competitively. The difference matters most when you maintain a meaningful balance for a long period, although the actual benefit depends on the rate, balance, and time.

    Interest is usually calculated from the account balance and credited according to the institution’s terms. To compare offers fairly, use APY rather than only the stated interest rate. APY reflects the effect of compounding under the account’s stated assumptions. Ask whether the advertised APY applies to every balance, only to new customers, or only while certain conditions are met.

    2. It can separate savings from everyday spending

    Keeping emergency savings in a separate account can reduce the temptation to spend it on routine purchases. A separate HYSA may create a practical boundary between money for rent, groceries, and bills and money reserved for unexpected expenses or future goals.

    This separation is not a guarantee of good budgeting, but it can work alongside automatic transfers, a written spending plan, and budgeting calculators or other budgeting tools. You might use labeled savings goals for car repairs, annual insurance premiums, travel, or a future home down payment, if the bank supports that feature.

    3. It may provide a balance between access and return

    Cash has different jobs. Money needed today may belong in a checking account. Money needed soon but not immediately may fit a savings account. Money that will not be needed for a longer period may be considered for a certificate of deposit, retirement account, or diversified investment, depending on your objectives and risk tolerance.

    A HYSA can occupy the middle ground: it may offer more interest than basic checking while allowing transfers and withdrawals more easily than many time-locked products. Access is not always instant, though. ACH transfers can take time, and banks may apply limits, holds, or verification procedures.

    High-Yield Savings Accounts Compared With Other Products

    HYSA versus checking account

    A checking account is usually built for frequent transactions, direct deposits, debit-card purchases, bill payments, and ATM access. A high-yield savings account is generally better suited to storing money rather than spending it every day. Some online savings accounts do not include checks, debit cards, or convenient cash deposits.

    One useful arrangement is to keep operating money in checking and transfer excess cash to savings. Compare checking account fees carefully, including monthly maintenance fees, overdraft-related charges, out-of-network ATM fees, wire fees, and minimum-balance requirements. A high APY may not compensate for fees if the account is difficult to use or repeatedly incurs charges.

    HYSA versus money market account

    Money market deposit accounts are bank or credit union deposit products, not the same as money market mutual funds. Depending on the institution, a money market deposit account may offer check-writing or debit-card access, but it may also have different balance requirements and rates. Compare the APY, access methods, fees, and insurance status rather than relying only on the product name.

    HYSA versus certificate of deposit

    A certificate of deposit (CD) generally pays a stated rate for a selected term. In exchange for committing the money until maturity, you may receive more predictable earnings than with a variable-rate savings account. Early withdrawal can result in a penalty, and the money may be less flexible.

    A HYSA may be more appropriate for an emergency fund or an uncertain time horizon. A CD may be worth comparing when you know you will not need the money during the term and want to evaluate rate certainty. A CD ladder can spread maturity dates, but it requires additional planning and may not provide immediate access to all funds.

    HYSA versus investments and retirement accounts

    Stocks, bonds, mutual funds, and exchange-traded funds can have higher long-term growth potential than a savings account, but they can also lose value. A HYSA is generally designed for capital preservation and liquidity, not long-term growth above inflation.

    Retirement accounts and IRAs may offer tax advantages, but they also have eligibility rules, contribution limits, investment choices, and withdrawal considerations. Emergency cash usually should not be placed in an account where accessing it could create taxes, penalties, or a forced sale of investments. The appropriate choice depends on the purpose and time horizon of the money.

    How to Compare High-Yield Savings Accounts

    A reliable comparison should look beyond the headline APY. Use the following process:

    1. Confirm the institution and insurance. Check whether the bank is FDIC-insured or the credit union is federally insured by the NCUA. If a financial technology company provides the interface, identify the actual deposit-holding institution and understand how pass-through insurance is described.
    2. Record the APY and rate conditions. Note whether the APY is variable, introductory, tiered by balance, or conditional on direct deposit or another requirement. Save the date of your comparison because rates can change.
    3. Review fees. Look for monthly maintenance fees, excessive withdrawal fees, returned-payment fees, wire charges, paper statement fees, and charges for expedited services. Also check whether the institution requires a minimum opening deposit or minimum balance.
    4. Test access before opening. Determine how to move money in and out, how long ACH transfers typically take under the account agreement, whether external accounts can be linked, and whether cash or checks can be deposited. Review daily transfer limits and any temporary holds.
    5. Examine the legal documents. Read the account agreement, fee schedule, privacy notice, and funds-availability policy. Marketing pages summarize products, but these documents control the relationship.
    6. Estimate the practical benefit. Compare expected interest using the balance you can realistically maintain, not an idealized balance. Subtract recurring fees and account for the possibility that the APY may decrease.
    7. Consider customer support and security. Look for secure login controls, multifactor authentication, transaction alerts, a clear fraud-reporting process, and support hours that match your needs.

    This methodology is based on comparing official account disclosures and fee schedules, with consumer-protection information from the FDIC and the Consumer Financial Protection Bureau (CFPB) used to clarify deposit insurance, account terms, and access considerations. The CFPB’s consumer banking resources and the FDIC’s deposit insurance materials are useful starting points for verifying general rules. For current rates and requirements, rely on the institution’s own disclosures rather than an older comparison article.

    Practical Ways to Use a High-Yield Savings Account

    Build an emergency reserve

    Start by identifying essential expenses such as housing, utilities, food, transportation, insurance, and minimum debt payments. Choose a reserve target based on your income stability, household responsibilities, health needs, and access to other resources. Keep enough in a readily available account for immediate bills, then consider a HYSA for the remainder if transfer timing is acceptable.

    Automate a specific goal

    Set a recurring transfer after payday and name the goal clearly. For example, you could save for an insurance premium, a professional certification, a replacement vehicle, or a moving expense. Automating a manageable amount is often more sustainable than making irregular transfers when money happens to remain at the end of the month.

    Coordinate savings with debt repayment

    High-interest credit card debt often deserves attention because its interest cost may exceed what a savings account earns. Still, eliminating all cash reserves can leave you vulnerable to using a credit card again when an unexpected expense occurs. Consider keeping a basic emergency cushion while directing additional money toward expensive debt, then compare personal loans or debt-consolidation options carefully. A lower monthly payment is not necessarily a lower total cost if the repayment term becomes longer or fees are added.

    Review the account periodically

    Check the APY, fees, statements, beneficiaries, linked accounts, and security settings at reasonable intervals. If the rate falls, compare alternatives, but do not move funds solely because of a temporary promotional rate. Also review how the account fits with your broader finances, including credit score improvement goals, insurance deductibles, mortgage rate comparison decisions, and retirement contributions.

    Pros and Cons

    Potential advantages

    • It may pay more interest than a basic savings account.
    • It can keep emergency or goal-based money separate from daily spending.
    • Eligible deposits may receive FDIC or NCUA insurance within applicable limits.
    • It generally offers more flexibility than a CD with an early-withdrawal penalty.
    • Online account tools may support automatic transfers and transaction alerts.

    Potential disadvantages

    • The APY is usually variable and may decrease without a matching increase in your balance.
    • Some accounts have limited branch, ATM, cash-deposit, or check-writing access.
    • Transfers may not be immediate, especially between unrelated institutions.
    • Promotional or tiered rates may not apply to your full balance or may expire.
    • Interest may not keep pace with inflation, reducing purchasing power over time.
    • Deposit insurance does not protect investments, cryptocurrency, unauthorized account activity caused by poor security practices, or losses above applicable coverage limits.

    Limitations and Common Mistakes

    A HYSA is not automatically the highest-return destination for every dollar. It may be unsuitable for money needed for same-day purchases if transfers are slow, and it may be inefficient for long-term retirement growth if used instead of an appropriate investment strategy. The account also cannot replace a budget, adequate insurance, or a plan for high-interest debt.

    Common mistakes include chasing a temporary APY without reading its conditions, overlooking monthly fees, storing more than the applicable insurance limit at one institution without understanding ownership categories, and assuming that a financial technology app is itself a bank. Another mistake is keeping emergency savings in a product whose withdrawal process has not been tested. Make a small test transfer and confirm how long it takes before relying on the account for an urgent bill.

    Concise Q&A

    Is a high-yield savings account safe?

    It can be relatively low risk when the account is offered by an FDIC-insured bank or an NCUA-insured credit union and your deposits remain within applicable insurance limits. Verify coverage and read the account terms.

    Can the APY change?

    Yes. Most high-yield savings accounts have variable rates. The institution can change the APY according to its terms, so compare current disclosures rather than assuming today’s rate will last.

    Should an emergency fund be in a HYSA?

    It may be appropriate if the account is insured, has no problematic fees, and allows access quickly enough for your needs. Keep immediate spending money in an account you can access without delay.

    Does a HYSA build credit?

    Usually not. Savings accounts generally do not report routine balances or interest payments to the major credit bureaus. Credit score improvement typically involves paying reported debts on time, managing utilization, and checking credit reports for errors.

    How much should be deposited?

    There is no universal amount. Base the balance on the purpose of the money, your essential expenses, income reliability, and insurance limits. Avoid depositing money that you need for immediate bills or that would be difficult to access when required.

    Bottom Line

    The best answer to “why high yield savings account” is that it can offer a useful combination of interest, separation from spending, and access for short- and medium-term cash. Its value depends on the complete account package: APY, fees, insurance, transfer speed, conditions, customer support, and security controls.

    Compare official disclosures from several institutions, calculate the likely benefit using your real balance, and match the account to the job your money must perform. Do not choose a savings account as a substitute for a personalized investment, tax, legal, or debt-management plan.

    Informational disclaimer: This article provides general educational information, not personalized financial advice. Rates, fees, insurance rules, tax treatment, and account terms can change. Confirm current details with the relevant bank, credit union, FDIC, NCUA, CFPB, or a qualified professional before making a financial decision.

  • Best Credit Cards Rewards 2025: A Practical Comparison Guide

    Choosing among the best credit cards rewards 2025 offers is less about finding one universally superior card and more about matching a card’s rewards structure, fees, redemption options, and acceptance to your spending habits. A card with a large headline bonus may be poor value if you carry a balance, pay an annual fee for unused benefits, or spend more to meet a bonus requirement.

    This guide explains how rewards credit cards work, compares common card types and notable examples, and provides a practical process for evaluating offers. It does not recommend a single card for every reader. Card terms, annual fees, interest rates, eligibility requirements, and rewards programs can change, so confirm current details directly with the issuer before applying.

    What Are Rewards Credit Cards?

    Rewards credit cards return value when you make eligible purchases. The reward may be cash back, points, or airline and hotel miles. In most cases, rewards are earned as a percentage or number of points per dollar spent, subject to the card agreement and program rules.

    There are three broad categories:

    • Cash-back cards: These typically provide a statement credit, direct deposit, or other cash-equivalent redemption. They are often straightforward for people who want predictable value.
    • Flexible-points cards: These earn points that may be redeemed through an issuer portal, transferred to participating travel programs, or exchanged for statement credits. Value can depend on the redemption method.
    • Airline and hotel cards: These offer rewards and benefits tied to a particular travel company. They may suit frequent customers but can be less flexible for occasional travelers.

    Rewards are only one part of the comparison. The annual percentage rate, or APR, matters if you do not pay the full statement balance. In general, interest charges can outweigh the value of rewards quickly. A rewards card should usually be treated as a payment tool rather than a reason to borrow more.

    How to Compare the Best Credit Cards Rewards 2025 Offers

    1. Calculate the value of the regular rewards

    Start with your normal spending rather than an idealized budget. Separate purchases into categories such as groceries, dining, fuel, travel, recurring bills, and general spending. Then examine whether the card offers a flat rate or bonus categories.

    A simple estimate is:

    Estimated annual rewards = eligible annual spending × reward rate

    For example, a card paying a flat cash-back rate may be easier to evaluate than a category card. A category card can produce more value only when you regularly spend in its higher-earning categories and stay within any limits. Do not increase spending merely to earn points.

    2. Review the annual fee and other costs

    Subtract the annual fee from your realistic rewards estimate. Also review foreign transaction fees, balance-transfer fees, cash-advance fees, late-payment consequences, and any fee for adding authorized users. A card with a premium annual fee may include travel credits, lounge access, insurance, or purchase protections, but those benefits count only if they are useful to you and reasonably easy to use.

    Some cards waive the annual fee for the first year, while others do not. Compare the recurring cost after any introductory period rather than focusing only on the first year.

    3. Assess the welcome offer carefully

    Welcome offers can be valuable, but they often require a specified amount of spending within a limited period. Read the exact terms, including eligible purchases, excluded transactions, bonus-posting timing, and what happens if an account is closed or payment is returned. A bonus should be a benefit of planned spending, not a justification for buying items you do not need.

    Also consider whether applying for multiple cards could affect your credit profile, complicate payment management, or make it harder to qualify for another financial product.

    4. Compare redemption rules

    One point or mile does not have a universal cash value. A program may offer different values for statement credits, gift cards, travel bookings, or transfers to partners. Check expiration policies, blackout restrictions, transfer minimums, cancellation rules, and whether rewards can be forfeited after an account closes.

    Flexible points can be useful for travelers who are willing to compare redemption options. Cash back may be more suitable for someone who wants a simple and transparent benefit.

    5. Consider acceptance and customer-service needs

    Before applying, make sure the payment network and card work where you shop. If you travel internationally, check foreign transaction policies and access to support while abroad. Review whether the issuer provides purchase alerts, virtual card numbers, dispute assistance, and tools to lock a lost card.

    Representative Card Types and Examples

    The following examples illustrate how to compare card structures. They are not endorsements, and current terms should be verified on official issuer pages. Offers and benefits may change during 2025.

    Card type Examples to research Potential strengths Possible limitations
    Flat-rate cash back Wells Fargo Active Cash; Citi Double Cash Simple rewards on broad spending; minimal category tracking May not maximize spending in specialized categories; terms and redemption rules vary
    Flexible travel points Chase Sapphire Preferred; Capital One Venture X Potentially broader travel redemption and transfer options Annual fees, changing transfer values, and travel-related restrictions may reduce value
    Category-focused rewards American Express Blue Cash Preferred; similar issuer category cards Can reward concentrated spending in eligible categories Bonus-category caps, merchant coding issues, annual fees, or redemption limits may apply
    Airline or hotel co-branded United Explorer; Marriott Bonvoy Boundless May include company-specific benefits such as checked-bag or hotel-related features Less flexibility if your travel plans change; loyalty-program rules can change

    Issuer names and product names are included so readers can locate official terms. The comparison does not assume that any listed card has the best current offer, lowest APR, or highest rewards value.

    Pros and Cons of Rewards Cards

    Potential advantages

    • Value on planned spending: Regular purchases may earn cash back or points without requiring a separate loyalty account for every transaction.
    • Introductory incentives: A welcome offer may provide extra value when the spending requirement fits an existing budget.
    • Useful protections: Some cards may include extended warranty coverage, purchase protection, rental-car coverage, travel interruption benefits, or fraud monitoring. Coverage has exclusions and conditions.
    • Credit-building opportunity: Consistent, on-time payments and low utilization may support a healthy credit history over time.

    Potential disadvantages

    • Interest can exceed rewards: Carrying a balance can make the card expensive, particularly when the purchase APR is high.
    • Fees reduce net value: An annual fee, foreign transaction fee, or balance-transfer fee can offset rewards.
    • Program complexity: Points may have variable value, transfer restrictions, expiration rules, or complicated booking conditions.
    • Overspending risk: Bonus categories and minimum-spending requirements can encourage purchases that do not fit a budget.
    • Credit impact: Applying for several cards can create hard inquiries and new accounts. The effect varies by person and scoring model.

    A Practical Decision Process

    1. Check your payment behavior. If you commonly carry a balance, begin by comparing low-interest options or a repayment plan rather than rewards alone.
    2. Review your last several months of spending. Use bank and card statements to identify recurring categories. Exclude unusual one-time purchases from your forecast.
    3. Set a target card purpose. Decide whether you want simple cash back, travel flexibility, a balance transfer, a business benefit, or a card for rebuilding credit.
    4. Estimate first-year and later-year value. Add realistic rewards and usable benefits, then subtract the annual fee and other expected costs. Perform the calculation again after introductory benefits end.
    5. Read the official pricing and terms. Confirm the APR range, penalty policies, fees, reward exclusions, bonus deadline, and eligibility rules.
    6. Check your credit profile without applying unnecessarily. Review your credit reports for errors through AnnualCreditReport.com and understand the issuer’s general qualification guidance. Approval is never guaranteed.
    7. Create a payment system. Set automatic payment for at least the minimum due, use alerts, and ideally pay the statement balance in full by the due date.

    How Rewards Cards Fit Into Broader Personal Finance Comparisons

    A credit card comparison should not be isolated from the rest of your financial plan. If you have expensive debt, compare personal loans and debt-consolidation options by total repayment cost, not just the advertised rate. Consolidation can simplify payments but may extend the repayment period or require collateral.

    Keep emergency savings in an account that matches your access needs. When comparing high-yield savings accounts, review the annual percentage yield, minimum balance requirements, withdrawal policies, deposit insurance, and whether the rate is variable. A checking account comparison should include monthly maintenance fees, overdraft practices, ATM access, direct-deposit conditions, and out-of-network charges.

    For a home purchase, mortgage rate comparison should include the annual percentage rate, lender fees, discount points, estimated cash needed at closing, and loan term. For insurance, compare car insurance and home insurance by coverage limits, deductibles, exclusions, claims service, and total premium rather than choosing solely on price.

    Long-term priorities also matter. Retirement accounts and IRAs may provide tax advantages that are more important than maximizing short-term card rewards. Use budgeting calculators and tools to test whether a purchase fits your cash flow, and monitor credit score improvement through on-time payments, moderate utilization, accurate reports, and cautious applications.

    Limitations of Online Card Comparisons

    No public comparison can calculate your exact value without knowing your spending, payment habits, travel preferences, taxes, and eligibility. Reward values can change when an issuer modifies a program or a transfer partner changes its rules. Merchant category coding may also differ from what a purchase appears to be, so a transaction may not earn the expected bonus.

    Prequalification tools may use a soft inquiry, but an actual application can involve a hard inquiry. Credit-score effects differ across scoring models and usually depend on the broader credit file. A card comparison also cannot predict approval, customer-service quality in every situation, or whether a benefit claim will be accepted.

    For these reasons, use comparison articles to create a shortlist, then verify the current agreement, pricing disclosure, rewards guide, and privacy terms on the issuer’s website.

    Sources and Comparison Methodology

    This guide uses a structure based on official and consumer-protection resources rather than invented tests or personal experience. The Consumer Financial Protection Bureau provides information on credit cards, billing rights, and credit-card agreements. The Federal Deposit Insurance Corporation explains deposit insurance and banking-product basics, which are relevant when comparing savings and checking accounts. AnnualCreditReport.com is the authorized site for requesting credit reports from the nationwide credit-reporting companies.

    For any specific card, compare the issuer’s current Schumer Box or pricing-and-terms disclosure, cardmember agreement, rewards program terms, and benefit guide. Examples used in this article include products associated with Chase, Capital One, Wells Fargo, Citi, American Express, United, and Marriott. Product names are provided for research purposes; readers should confirm that the product is still available and that its terms match their needs.

    Q&A

    What is the best rewards card for most people?

    There is no single best card for everyone. A no-annual-fee flat-rate cash-back card may suit someone who wants simple rewards, while a flexible travel card may suit a frequent traveler who can use its benefits and pay the annual fee.

    Should I choose points or cash back?

    Choose cash back when predictable value and simplicity matter most. Consider points when you understand the redemption rules and can reliably obtain more value through travel or transfer partners. Avoid assuming that points are automatically worth more than cash.

    Is it worth paying an annual fee?

    It can be worthwhile when the rewards and benefits you actually use exceed the fee. Calculate the value after the first year, because an introductory waiver or welcome offer may not continue.

    Do rewards improve my credit score?

    Rewards themselves do not improve a score. Responsible account management, including on-time payments and controlled balances, may help your credit profile. Applying for accounts or carrying high balances can have the opposite effect.

    Are credit-card rewards taxable?

    Tax treatment can depend on how rewards are earned and the circumstances of a bonus. Consult current IRS guidance or a qualified tax professional if a reward is connected to compensation, business activity, or another taxable event.

    Informational disclaimer: This article is for general education and is not personalized financial, credit, legal, tax, or investment advice. Credit cards involve borrowing and fees. Review official terms, consider your ability to repay, and seek qualified advice for circumstances such as significant debt, bankruptcy, or complex tax issues.

  • Best Credit Card Rewards September 2025: Compare Top Options by Spending Style

    Best Credit Card Rewards September 2025: Compare Top Options by Spending Style

    Finding the best credit card rewards September 2025 offers requires more than choosing the card with the largest advertised bonus. The right card depends on your spending habits, credit profile, travel preferences, annual-fee tolerance, and ability to pay the balance in full. A card with premium travel benefits may be valuable for one household but unnecessarily expensive for someone who mainly buys groceries and gas.

    This comparison explains how to evaluate rewards cards available in September 2025, including cash-back cards, travel cards, flexible-points programs, store cards, and balance-transfer alternatives. Card terms change frequently, so confirm the current annual percentage rate, annual fee, welcome offer, reward categories, redemption rules, and eligibility requirements directly with the issuer before applying.

    How to Compare the Best Credit Card Rewards in September 2025

    A useful comparison starts with the value you can realistically receive, not the headline offer. Review these factors together:

    • Reward rate: Check whether rewards apply to all purchases or only selected categories.
    • Annual fee: Estimate the fee over a full year and subtract it from the rewards and benefits you expect to use.
    • Welcome offer: Confirm the spending deadline, eligible purchases, exclusions, and whether the offer is available to you.
    • Redemption value: Cash back is usually straightforward, while points and miles can have different values depending on how you redeem them.
    • Interest rate: A rewards card can become costly if you carry a balance. The interest charge may outweigh the rewards.
    • Foreign transaction fees: Travelers should check whether purchases outside the United States receive favorable treatment.
    • Credit requirements: Premium rewards cards commonly require stronger credit and reliable income.
    • Benefits and protections: Consider purchase protection, extended warranty coverage, rental car coverage, travel interruption protection, and fraud monitoring where applicable.

    The most important calculation is simple: expected annual rewards plus usable benefits, minus the annual fee and any avoidable costs. If you cannot pay the statement balance on time, compare the card’s purchase APR with a low-interest alternative before focusing on rewards.

    Best Rewards Card Types for Different Consumers

    How to Compare the Best Credit Card Rewards in September 2025
    How to Compare the Best Credit Card Rewards in September 2025

    Best for simple cash back

    A flat-rate cash-back card can work well for people who want a predictable reward on everyday purchases. These cards generally offer the same base reward on most eligible spending, so they require little tracking. Some provide a higher rate on selected categories or during promotional periods.

    Flat-rate cards are often suitable for households with varied spending that does not fit neatly into rotating bonus categories. They can also be useful as a second card when another account offers stronger rewards for groceries, dining, travel, or online purchases. Compare redemption minimums, reward expiration rules, and whether the issuer allows statement credits, direct deposits, or other redemption methods.

    Best for bonus-category cash back

    Category-based cards may offer stronger rewards for purchases such as supermarkets, restaurants, fuel, transit, streaming services, or home improvement. The tradeoff is that the bonus rate may apply only up to a spending limit, may require activation, or may change each quarter.

    These cards are most valuable when your normal spending already matches the eligible categories. Do not buy extra items simply to reach a rewards threshold. A reward earned on unnecessary spending is not a saving.

    Best for flexible travel points

    Flexible-points cards can appeal to travelers who want several redemption choices. Depending on the issuer, points may be used for travel bookings, statement credits, gift cards, or transfers to participating airline and hotel programs. Transfer options can potentially produce more value, but they require planning and may involve restrictions.

    When comparing travel cards, review the annual fee, travel credit structure, authorized-user costs, airport lounge access, hotel or airline benefits, transfer partners, and foreign transaction policy. A travel card is usually a poor fit if you will not use its benefits or if you prefer cash back with no redemption decisions.

    Best for frequent travelers

    Premium travel cards may include airport lounge access, travel credits, hotel status, rental car protections, baggage coverage, and other benefits. The headline value can look attractive, but each benefit may have conditions, enrollment requirements, merchant restrictions, or limited redemption windows.

    Before paying a premium fee, list the benefits you would use without changing your normal behavior. Then estimate their reasonable value. Do not assign full value to a credit you are unlikely to use. Also check whether a benefit is provided by the card network, the issuer, or a third-party partner, since coverage and claims procedures can differ.

    Best for credit-building and secured rewards

    Consumers with limited or damaged credit may have fewer rewards choices. A secured credit card can provide a path to building payment history while requiring a refundable security deposit. Some secured cards offer cash back, but the reward rate should not be the main consideration.

    Look for an issuer that reports activity to the major credit bureaus, explains the upgrade process, and does not charge unnecessary fees. Pay every bill on time, keep balances modest relative to the credit limit, and avoid applying for several accounts in a short period.

    Credit Card Categories Worth Comparing in September 2025

    Card category Potential strength What to check
    Flat-rate cash back Simple rewards on broad spending Base rate, annual fee, redemption rules
    Bonus-category cash back Higher rewards in selected categories Activation, caps, rotating categories, exclusions
    Flexible travel points Multiple travel and redemption options Transfer partners, fees, redemption value
    Premium travel Travel credits and protections Benefit usability, enrollment, annual fee
    Balance transfer Potential interest savings during a promotional period Transfer fee, expiration date, post-promotion APR
    Secured credit building Payment-history support for limited credit Deposit, fees, bureau reporting, upgrade policy

    How Popular Rewards Programs Fit Different Spending Styles

    Several large issuers have established rewards families, but no single program is best for every applicant. Cards linked to flexible points may suit people who combine airline, hotel, and general travel redemptions. Co-branded airline and hotel cards may be more useful when you regularly use one loyalty program and can take advantage of its baggage, booking, or status-related benefits.

    Cash-back products from major banks can be easier to manage because the reward value is usually more transparent. Examples of commonly compared product families include flat-rate cash-back cards, rotating-category cards, customized-category cards, and cards tied to a bank’s broader points ecosystem. Product names, terms, and public offers can change, so use the issuer’s current application page rather than relying on an old review.

    Cards from American Express, Capital One, Chase, Citi, Discover, Bank of America, Wells Fargo, U.S. Bank, and other issuers can all be relevant in a September 2025 comparison. The strongest choice depends on your eligibility and spending pattern. A card’s reputation alone does not guarantee that its current offer is the best fit.

    When a Welcome Bonus Is Worth Pursuing

    A welcome bonus can increase first-year value, but it should not encourage spending beyond your budget. Before applying, divide the required spending by the number of months in the qualification period. Compare that monthly amount with your normal expenses, including recurring bills that the issuer allows you to pay by card without a costly convenience fee.

    Read the fine print carefully. Returned purchases may reduce qualifying spending. Balance transfers, cash advances, fees, interest, and some person-to-person transactions may not count. You may also be ineligible for a bonus because of previous ownership of the same product or a related card family.

    Do not open a card solely for a bonus if you expect to carry the balance. A high interest charge can erase the bonus quickly. If you are planning a mortgage, auto loan, or other major credit application, consider how a new account and credit inquiry may fit into that timeline.

    Rewards Cards and Your Wider Personal Finance Plan

    High-yield savings accounts

    Credit card rewards should complement, not replace, an emergency fund. Keep cash reserves in an appropriate high-yield savings account or another liquid, federally insured deposit account when available. Compare the account’s variable interest rate, minimum balance, monthly fee, withdrawal policies, and access to funds. A rewards card cannot compensate for a lack of emergency savings if an unexpected bill leads to revolving debt.

    Checking account fees

    Review checking account fees alongside your credit card choices. Monthly maintenance fees, overdraft charges, out-of-network ATM fees, and wire fees can reduce the value of rewards. Some banks waive checking fees with direct deposit or a minimum balance, but requirements differ. Banking product comparisons should consider the entire relationship rather than a single promotional perk.

    Personal loans and debt consolidation

    If you already carry high-interest credit card debt, a rewards card may not be the solution. A personal loan for debt consolidation could provide a fixed payment and a defined payoff schedule, but compare the annual percentage rate, origination fee, term, total repayment, and consequences of missed payments. A lower monthly payment may result from extending the repayment period rather than reducing the total cost.

    Mortgage rate comparison

    People preparing to buy or refinance a home should prioritize mortgage readiness over a short-term card bonus. Lenders review credit reports, debt obligations, income, assets, and payment history. Avoid unnecessary new accounts before applying for a mortgage, and compare mortgage offers using the interest rate, annual percentage rate, lender fees, points, loan term, and estimated cash required at closing.

    Car insurance and home insurance

    Some cards provide limited purchase or rental protections, but they do not replace auto or homeowners insurance. Compare insurance quotes based on coverage limits, deductibles, exclusions, claims service, and liability protection. Paying an insurance premium with a rewards card may be useful if there is no convenience fee and you can pay the balance in full.

    Retirement accounts and IRAs

    After establishing a manageable budget and emergency reserve, review retirement contributions and IRA options. A credit card reward is a small benefit compared with consistent long-term saving. Check employer plan matching rules, investment expenses, tax treatment, contribution eligibility, and withdrawal restrictions before deciding where additional money should go.

    Use a Budgeting Calculator Before Applying

    A budgeting calculator can help estimate the annual value of a card. Add your typical monthly spending by category, multiply each category by the applicable reward rate, and subtract the annual fee. Exclude spending you would not make otherwise. Then run a second estimate using conservative redemption assumptions, especially for travel points.

    Also calculate the cost of carrying a balance. Compare the expected reward with the interest that could accrue if you pay less than the full statement balance. Set automatic payments for at least the minimum due and, when possible, schedule payment of the full statement balance. Alerts can help you monitor utilization and prevent missed deadlines.

    Credit Score Considerations

    Applying for a credit card may produce a hard inquiry, and opening a new account can affect the average age of your accounts and available credit. The effect varies by person and is often temporary, but it matters if you are seeking a mortgage or other major loan soon.

    Credit score improvement usually comes from consistent habits: paying on time, keeping revolving balances manageable, correcting inaccurate report information, limiting unnecessary applications, and maintaining older accounts when appropriate. Checking your own credit report does not have the same effect as applying for new credit. Review reports from the major bureaus and dispute errors through the applicable reporting agency.

    Questions and Answers

    What is the best credit card rewards option for September 2025?

    There is no universal winner. A flat-rate cash-back card may be best for simplicity, a category card for concentrated grocery or dining spending, and a travel card for people who use its points and benefits. Compare current terms with your actual budget.

    Should I choose cash back or travel points?

    Choose cash back if you want predictable value and few restrictions. Choose travel points if you understand the redemption system and will use the travel benefits or transfer partners. Do not pay a higher annual fee for benefits you will not use.

    Are rewards cards suitable for carrying debt?

    Usually not. If you carry a balance, the interest cost can exceed the rewards. Consider a lower-interest strategy, a balance-transfer offer, or a carefully compared consolidation loan instead.

    How many credit cards should I have?

    The right number depends on your ability to manage payments, fees, utilization, and account security. One well-managed card can be enough. More accounts are not automatically better for your credit score or budget.

    Bottom Line

    The best credit card rewards September 2025 choice is the account that produces useful value without changing your spending or creating expensive debt. Compare cash-back rates, points flexibility, annual fees, welcome-offer requirements, protections, and issuer policies. Check your credit profile, use a budgeting calculator, and review related financial priorities such as savings, debt repayment, insurance, mortgages, and retirement contributions. Finally, verify every offer directly with the issuer because rewards, fees, and eligibility rules can change after publication.

    General information only; it is not financial, tax, legal, or investment advice. Card approvals, rates, rewards, and benefits depend on the issuer and applicant.

  • Best Rewards Credit Card June 2025: How to Compare Cards and Choose the Right Fit

    Best Rewards Credit Card June 2025: How to Compare Cards and Choose the Right Fit

    Searching for the best rewards credit card June 2025 can lead to a long list of cash-back cards, travel cards, flexible-points programs, store cards, and premium products. The strongest choice is not always the card with the largest welcome offer. It is the card whose rewards, fees, redemption options, interest rate, and benefits match the way you already spend.

    Credit card offers can change at any time, so review the issuer’s current terms before applying. Welcome bonuses, annual fees, eligible spending categories, redemption values, foreign transaction fees, and approval requirements vary by applicant and by product. This guide explains how to compare rewards cards in June 2025 without relying on a single promotional headline.

    What makes a rewards credit card a good choice?

    A rewards card should provide value after fees and interest, not just an attractive earning rate. Start by looking at five factors:

    • Rewards structure: Check whether the card pays a flat rate on purchases or offers higher rewards in selected categories such as groceries, dining, fuel, travel, or rotating promotions.
    • Annual fee: Compare the fee with the rewards and benefits you are likely to use. A no-annual-fee card may be best for simple cash back, while a fee-based card may suit frequent travelers.
    • Redemption flexibility: Find out whether rewards can be used for statement credits, direct deposits, gift cards, merchandise, travel bookings, or transfers to loyalty programs.
    • Interest rate and fees: Rewards generally lose their value if you carry a balance at a high variable APR. Review balance transfer fees, late fees, cash advance costs, and foreign transaction fees.
    • Eligibility: A card’s approval criteria may include credit history, income, existing debt, and recent applications. Applying for several cards at once can make managing your credit more difficult.

    The right comparison starts with your spending habits and payment plan. If you pay the statement balance in full every month, rewards and fees deserve close attention. If you regularly carry a balance, an affordable low-interest or balance-transfer product may be more useful than a rewards card.

    Best rewards credit card categories for June 2025

    What makes a rewards credit card a good choice?
    What makes a rewards credit card a good choice?

    There is no single best card for every household. The following categories can help you narrow your search.

    Best for simple cash back

    A flat-rate cash-back card is often the easiest option to manage. You earn the same base reward on most eligible purchases instead of tracking bonus categories. This type of card can work well for households with varied spending or for people who want predictable rewards.

    Before choosing one, check whether the advertised rate applies to all purchases, whether there is a spending cap, and whether certain transactions are excluded. Some cards require you to redeem rewards manually, while others allow automatic statement credits or deposits. Also confirm whether rewards expire or can be forfeited after an account closes.

    Best for category bonuses

    Category cards can earn more on purchases such as restaurants, supermarkets, streaming services, travel, or transportation. They may be a strong fit when a large share of your regular budget falls within the bonus categories.

    Read the category definitions carefully. A supermarket bonus may not include warehouse clubs, convenience stores, or meal-kit services. A travel category may treat direct airline purchases differently from third-party bookings. Some bonus rates apply only up to a spending limit, then revert to a lower base rate.

    Best for flexible travel rewards

    Flexible-points cards can be useful if you want several ways to redeem rewards. Depending on the program, points may be applied to travel, exchanged with airline or hotel partners, or used for cash-back options. Transfer opportunities can increase value, but they also require more research and planning.

    Travel cards often include benefits such as travel protections, rental car coverage, airport-related perks, or credits for selected services. These benefits are only valuable if you use them. Check eligibility rules, enrollment requirements, exclusions, and whether coverage is secondary or primary.

    Best for frequent airline or hotel customers

    A co-branded airline or hotel card may suit someone who consistently uses one loyalty program. Benefits can include a free checked bag, preferred booking treatment, hotel credits, or progress toward elite status. The value depends on your travel patterns and the availability of the participating brand in the places you visit.

    These cards may be less flexible than general travel cards. Compare the value of brand-specific rewards with a card that earns transferable points or unrestricted cash back. Consider blackout rules, award availability, expiration policies, and program changes before assigning a high value to points.

    Best for students and credit building

    Students and people establishing credit may have better access to starter rewards cards, secured cards, or products designed for limited credit histories. The rewards rate may be modest, but responsible use can be more important than maximizing points.

    Look for reasonable fees, clear reporting to the major credit bureaus, and an account limit that supports manageable spending. Never spend more simply to earn rewards. Paying on time, keeping balances under control, and reviewing statements are central to credit score improvement.

    How to compare a welcome offer

    Welcome offers can make a card attractive during the first year, but they should not determine the entire decision. Most offers require you to spend a specified amount within a specified period after account opening. Confirm the exact deadline, qualifying purchases, excluded transactions, and the date on which the bonus will be awarded.

    Ask yourself whether the spending requirement fits your normal budget. Manufacturing spending, buying unnecessary items, or carrying debt to earn a bonus can cost more than the reward. Purchases such as balance transfers, cash advances, fees, returned items, and some person-to-person payments may not qualify.

    Also check whether the issuer limits how often you can receive a bonus from the same product or family of cards. Existing or recently closed accounts may affect eligibility. A welcome offer is best treated as an extra benefit, not as a reason to change your spending habits.

    Rewards math: measure net value

    A simple comparison can prevent rewards marketing from distorting your decision. Estimate your annual rewards using realistic spending, then subtract the annual fee and any costs required to receive benefits.

    For example, separate your budget into ordinary purchases and bonus-category purchases. Multiply each amount by the applicable reward rate, then estimate the redemption value. If a travel point can be used in several ways, calculate a conservative value rather than assuming the most favorable redemption.

    Next, subtract the annual fee and any costs you would not otherwise incur. If a card offers a travel credit, count it only if you would have paid for the qualifying purchase without the card. If you would not use an airport lounge, subscription credit, or hotel benefit, its advertised value should not be included in your personal calculation.

    Rewards calculations should also account for opportunity cost. A high-yield savings account may earn interest on cash that remains in savings, while using a credit card does not automatically improve your finances. Keep emergency funds and bill money in appropriate accounts rather than spending for points.

    Interest, utilization, and credit score considerations

    Rewards cards are usually most suitable for people who can pay the full statement balance by the due date. Interest can quickly outweigh cash back or travel rewards. If you expect to carry debt, compare the card’s variable APR with alternatives such as a lower-rate card, a personal loan, or a balance-transfer offer.

    Using a card can affect your credit profile in several ways. A new application may create a hard inquiry, and a new account can change the average age of your accounts. High balances relative to your credit limits can also affect utilization, even if you pay the balance before the due date. Paying on time remains one of the most important parts of maintaining healthy credit.

    Set up automatic payments for at least the minimum amount, then pay the full statement balance when possible. Review your credit reports for errors, keep older accounts open when appropriate, and avoid applying for products that do not fit your credit profile. These steps can support longer-term credit score improvement more effectively than chasing a temporary bonus.

    Rewards cards versus other financial products

    A credit card should be compared with the alternatives available for the same financial goal.

    High-yield savings accounts

    A high-yield savings account is designed for cash reserves, emergency savings, and short-term goals. It does not provide credit card rewards, but it may pay a competitive variable interest rate while keeping funds accessible. Compare the account’s yield, minimum balance rules, withdrawal policies, transfer speed, and deposit insurance coverage.

    Checking accounts and fees

    Rewards checking accounts can offer incentives, but requirements may include direct deposit, a minimum number of debit transactions, or a required balance. Compare monthly maintenance fees, overdraft policies, ATM access, wire fees, and early direct-deposit availability. A checking account with fewer fees may be more valuable than one with a small rewards program.

    Personal loans and debt consolidation

    If you are carrying balances across several cards, a personal loan or debt-consolidation strategy may simplify payments. Compare the total cost, origination fee, repayment term, and fixed or variable rate. Consolidation does not eliminate debt, and using cards again after consolidation can create a larger financial burden.

    Mortgage rate comparison

    Credit activity matters when preparing for a mortgage. Avoid opening unnecessary credit accounts before applying for a home loan, and compare mortgage offers by looking at the annual percentage rate, lender fees, points, term, and estimated cash required at closing. A rewards card should not distract from maintaining stable income, manageable debt, and accurate credit records.

    Insurance and retirement accounts

    Some cards offer rewards for insurance or investment contributions, but these transactions may not qualify under the issuer’s terms. Compare car insurance and home insurance by coverage, deductibles, exclusions, and claims service rather than focusing only on price. For retirement accounts and IRAs, prioritize contribution strategy, investment choices, fees, and tax treatment. Credit card rewards are secondary to adequate insurance and long-term retirement saving.

    Common mistakes when choosing a rewards card

    • Focusing only on the welcome bonus: A large introductory offer may not compensate for years of fees or poor rewards on your normal spending.
    • Ignoring redemption rules: Points may have different values depending on how you use them, and some options may require minimum redemptions.
    • Carrying a balance for rewards: Interest charges can exceed the value of cash back or points.
    • Overlooking foreign transaction fees: These costs can reduce the value of a travel card when used outside the country or with an overseas merchant.
    • Missing category limits: Bonus rewards may apply only to selected purchases or up to a stated spending threshold.
    • Applying without checking eligibility: Review the issuer’s stated credit range and application rules before submitting an application.
    • Failing to monitor account changes: Issuers can change rewards terms, fees, benefits, and eligible categories with required notice.

    A practical checklist before applying

    Use this checklist to compare the best rewards credit card options available in June 2025:

    1. List your normal monthly spending by category.
    2. Decide whether you will pay the full statement balance each month.
    3. Compare annual fees with rewards you can realistically use.
    4. Read the rewards program rules, including caps and exclusions.
    5. Review redemption choices and estimate a conservative value.
    6. Check the regular APR, balance-transfer terms, and other fees.
    7. Confirm the welcome-offer spending requirement fits your budget.
    8. Review foreign transaction fees and travel protections if relevant.
    9. Check eligibility before applying and limit unnecessary applications.
    10. Set up alerts and automatic payments immediately after approval.

    Q&A: best rewards credit card June 2025

    What is the best rewards credit card in June 2025?

    The best card depends on your spending, credit profile, payment habits, and preferred redemption method. A flat-rate cash-back card may suit a simple budget, while a flexible travel card may be better for someone who uses points and travel benefits regularly.

    Is cash back better than travel points?

    Cash back is usually easier to understand and redeem. Travel points can offer greater flexibility or value for informed users, but their value depends on booking rules, transfer partners, and availability. Choose the system you will actually use.

    Should I choose a card with an annual fee?

    Choose an annual-fee card only when the rewards and benefits you expect to use exceed the fee by a comfortable margin. Recalculate the value each year because spending patterns and card benefits can change.

    Can I earn rewards while paying down debt?

    You may earn rewards, but carrying a balance can make the strategy costly. Focus on reducing high-interest debt first, and consider whether a lower-rate product or structured repayment plan is more appropriate.

    How often should I compare credit cards?

    Review your card at least once a year and whenever your spending, travel, income, or debt changes. Check the issuer’s current terms before switching, closing an account, or applying for a new product.

    Final decision

    The best rewards credit card for June 2025 is the one that delivers repeatable value without encouraging extra spending or expensive debt. Compare the complete package: earning rates, fees, redemption rules, interest costs, protections, eligibility, and the effect on your broader financial plan.

    Use a budgeting calculator or spending tracker to estimate realistic rewards, keep emergency cash in an appropriate savings account, and treat credit card benefits as a supplement rather than a financial strategy. A careful comparison can help you choose a card that supports your goals instead of merely offering the most attention-grabbing promotion.

  • Can You Compare Mortgage Rates? A Practical Way to Shop Offers

    Can You Compare Mortgage Rates? A Practical Way to Shop Offers

    Mortgage rates are easy to quote and hard to compare. The headline rate matters, but it does not tell the full story of what a loan will cost over the time you keep it. Two offers with the same rate can produce very different monthly payments and very different total costs once fees, points, lender credits, and rate-lock rules are included.

    This guide explains how to compare mortgage rates in a way that reflects how people actually borrow. It is educational information, not personalized financial advice. Mortgage rates, fees, and terms can change quickly, and you should verify current offers directly with lenders before you apply.

    Here is the short version: compare the rate, the APR, the fees, the monthly payment, the break-even period, and the time you expect to keep the loan. If you only compare the rate, you can miss a cheaper offer. If you only compare the monthly payment, you can miss a loan with bigger upfront costs.

    What a mortgage rate comparison really means

    A mortgage rate is the interest charge you pay on the borrowed balance. A lower rate usually lowers the monthly payment, but the best deal is not always the lowest rate on the page. Lenders can adjust pricing through points, credits, origination fees, underwriting fees, and escrow requirements. That is why the same borrower can receive two offers that look close at first glance and still end up paying different amounts.

    One useful way to think about it is this: the rate is the price tag, the APR is the broader cost signal, and the loan estimate is the document that shows how the deal is actually structured.

    Quotable rule: A low mortgage rate with high fees is not automatically a good deal.

    Quotable rule: The loan you keep for seven years should be compared differently from the loan you plan to refinance in two.

    Quotable rule: The right comparison is the cheapest path for your timeline, not the cheapest headline number.

    The numbers that matter most

    Can You Compare Mortgage Rates? A Practical Way to Shop Offers
    Can You Compare Mortgage Rates? A Practical Way to Shop Offers

    When you compare mortgage rates, start with these fields on each loan estimate:

    • Interest rate: the rate used to calculate interest on the remaining balance.
    • APR: a broader measure that blends interest and certain lender costs into one annualized figure.
    • Points: upfront charges you may pay to reduce the rate.
    • Lender credits: pricing offsets that reduce closing costs but usually raise the rate.
    • Origination and processing fees: lender charges that can change the true cost.
    • Monthly principal and interest payment: the payment tied directly to the loan balance and rate.
    • Total cash needed to close: what you must bring on closing day.

    APR is helpful, but it is not magic. It is useful when comparing loans with similar terms and similar time horizons. It is less useful when you expect to move quickly or refinance soon, because APR spreads certain costs over the life of the loan.

    A simple comparison method

    Use this three-step approach when you compare mortgage offers.

    1. Compare the base rate and payment

    Start by comparing the monthly principal and interest payment at each rate. This tells you the recurring cost. If the payment difference is small, fees may decide the winner. If the payment difference is large, the rate probably deserves more weight.

    2. Add the closing costs

    Look at lender fees, discount points, title charges, and prepaid items. Not every closing cost is negotiable, but lender-originated fees often are more flexible than borrowers realize. This is where the loan estimate earns its keep.

    3. Check the break-even period

    If one offer has lower fees but a slightly higher rate, or a lower rate but more upfront cost, estimate how long it takes for the monthly savings to recover the extra cash paid at closing. If the break-even period is longer than the time you expect to keep the mortgage, the cheaper upfront option often wins.

    For example, say Offer A is 6.75% with $3,000 in lender fees, while Offer B is 6.875% with $1,000 in lender fees. Offer A saves you about $25 per month on a $300,000 loan. It would take roughly 80 months to recover the extra $2,000 in fees. If you may sell or refinance in five years, Offer B could be the better choice.

    Rate, APR, and points are not the same

    Borrowers often mix these up, and lenders know it. Here is the practical difference.

    Rate tells you the interest charge. APR tries to show a broader annual cost picture. Points are prepaid interest used to buy down the rate. In plain English: points ask you to pay more now to pay less later.

    That can make sense if you will keep the loan long enough. It usually makes less sense if you expect a short holding period. The same is true for lender credits in reverse. A credit can reduce closing costs, but it often comes with a higher rate, so you pay for the credit over time through a bigger monthly payment.

    Fixed versus adjustable loans

    Loan structure matters as much as pricing. A fixed-rate mortgage keeps the same rate for the full term, which makes comparison easier. An adjustable-rate mortgage, or ARM, starts with a lower introductory rate and then resets on a schedule after the fixed period ends.

    ARMs can be reasonable when you expect to move before the first reset or when the initial savings are large enough to justify the risk. They are less comfortable when your budget is tight or when you want payment predictability. A fixed-rate loan is often the cleaner choice for households that value a stable payment more than a short-term discount.

    If you compare an ARM with a fixed loan, do not stop at the introductory rate. Read the adjustment caps, the index, the margin, the reset frequency, and the highest possible payment under the contract rules. Many borrowers focus on the starter rate and ignore the payment risk that arrives later.

    A comparison table you can use

    Item Why it matters What to watch for
    Rate Determines monthly interest cost Small changes can move payment and total interest
    APR Shows a broader cost picture Best for similar loan types and timelines
    Points Buys down the rate Only worth it if you keep the loan long enough
    Lender credits Reduce closing costs Often paired with a higher rate
    Monthly payment Drives cash flow Compare principal, interest, taxes, and insurance separately
    Break-even period Shows when upfront cost is recovered Compare to how long you plan to keep the loan

    What to ask lenders before you decide

    Good comparisons come from good questions. Ask each lender for the same scenario so you can compare like with like.

    • Is this rate locked, and for how long?
    • What fees are lender-controlled and which are third-party charges?
    • How much would the payment change if I pay points?
    • What rate would I get with no points and no credits?
    • What is the total cash needed at closing?
    • Are there prepayment penalties or other conditions?
    • How does the offer change if my credit score or loan amount changes?

    That last point matters. A lender may quote a rate based on a cleaner profile than the one you actually bring to underwriting. Ask for the assumptions behind the quote so you know whether the offer is realistic.

    How to compare rates if you plan to refinance later

    Many borrowers do not keep a mortgage for 30 years. They refinance, sell, or make extra principal payments. That means a comparison should reflect the likely holding period.

    If you expect to refinance in two or three years, a slightly higher rate with much lower fees can be the better choice. If you plan to stay long term, paying points for a lower rate may make sense. The math changes with the timeline.

    That is why refinance decisions should be built on the same structure as purchase decisions: rate, fees, payment, and break-even period. The loan that looks best at closing may not be the one that costs least over the period you actually keep it.

    Common mistakes borrowers make

    There are a few repeated mistakes worth avoiding.

    First, people compare only the interest rate and ignore fees. Second, they compare only the monthly payment and miss the total closing cost. Third, they assume APR settles the issue even when the loans have different time horizons. Fourth, they forget to compare identical loan amounts and identical assumptions.

    Another common mistake is overreacting to a tiny rate difference. On a small loan balance, a 0.125% change may not justify a much higher fee. On a large balance, it can matter more. The point is not to worship small percentage changes. The point is to know when the difference is large enough to matter in dollars.

    When the cheapest loan is not the best loan

    The cheapest mortgage is not always the one with the lowest upfront cost. A loan with lower fees but a higher rate can be smarter if you need to conserve cash for repairs, moving costs, or reserves. A loan with a lower rate and higher fees can be smarter if you know you will keep it long enough to recover the upfront expense.

    In other words, the best mortgage is the one that fits your time horizon, cash position, and comfort with payment risk. That sounds simple, but it is the part many quote pages leave out.

    Quotable rule: Cash flow, not just interest, decides whether a mortgage is manageable.

    Quotable rule: The cheapest loan on day one may be the most expensive loan by year three.

    FAQ

    Can you compare mortgage rates on the same day?

    Yes, but you should compare the full loan estimate, not just the posted rate. A same-day comparison is useful only if the loan amount, term, lock period, and fee assumptions match.

    Is APR better than the interest rate for comparison?

    APR is useful, but it is not always better. It gives a broader cost picture, yet it can be less helpful when you expect to move or refinance before the loan matures.

    Should I pay points to get a lower mortgage rate?

    Sometimes. Pay points when the break-even period is comfortably shorter than the time you expect to keep the loan, and when you have enough cash to cover them without creating strain.

    How much rate difference is worth switching lenders?

    There is no universal cutoff. Use the total cost difference, not a rule of thumb. A small rate edge can be wiped out by fees, and a slightly higher rate can still be cheaper if closing costs are lower.

    Do mortgage rates change daily?

    Yes, and sometimes more than once a day. That is why rate quotes should be checked close to the time you apply and again before you lock.

    Bottom line

    If you want to compare mortgage rates properly, compare the whole loan, not the headline. Start with the rate, check the APR, inspect the fees, estimate the break-even period, and match the offer to how long you plan to keep the mortgage. That process is slower than scanning one number, but it is far more likely to lead to a choice that makes sense in real life.

    Mortgage shopping is about tradeoffs. The right question is not only which rate is lower. It is which loan is cheaper for your timeline, your cash position, and your tolerance for payment changes.

    Rates, fees, and lender terms can change at any time, so verify current details directly with the provider before you apply or lock a loan.

  • Why Do High-Yield Savings Account Rates Change? A Practical Guide

    Why Do High-Yield Savings Account Rates Change? A Practical Guide

    High-yield savings account rates change because most savings accounts have variable annual percentage yields, or APYs. A bank can raise or lower its rate as market conditions, its funding needs, and its business strategy change. Your balance does not disappear when the APY moves, but the interest it earns going forward can change.

    That is the short answer to why do high yield savings account rates change. The more useful answer is how to judge whether a rate move should change your own plan. A small rate reduction may matter less than easy transfers, no monthly fee, and a bank you can use comfortably. A large reduction, especially after a promotional period, can justify comparing alternatives.

    “A high APY is a current price, not a lifetime promise.”

    This guide explains what drives savings rates, how interest is calculated, when switching may make sense, and what to check before opening or moving an account.

    What is a high-yield savings account?

    A high-yield savings account is a deposit account that pays an APY higher than many traditional savings accounts. It is generally intended for money you want to keep accessible, such as an emergency fund, a near-term home down payment, or a planned expense. Banks and credit unions set their own rates and account rules.

    Definition: APY. Annual percentage yield reflects the annualized return on a deposit after compounding is considered. It is the standard figure that makes savings rates easier to compare. APY is not the same as a promise that the rate will remain unchanged for a year.

    At a federally insured bank, eligible deposits are generally covered by FDIC insurance within applicable ownership-category limits. At a federally insured credit union, comparable coverage is generally provided by the NCUA. Confirm an institution’s insurance status and how coverage rules apply to your account structure before depositing a large sum.

    Why high-yield savings account rates change

    Why Do High-Yield Savings Account Rates Change? A Practical Guide
    Why Do High-Yield Savings Account Rates Change? A Practical Guide

    Changes in broader interest rates

    Bank deposit rates often respond to changes in the wider interest-rate environment. When short-term market rates rise, banks may offer more attractive savings APYs to attract deposits. When market rates fall, they may reduce APYs. The timing and amount vary by institution: there is no rule requiring every bank to move by the same amount on the same day.

    Think of the advertised APY as a rate that is repriced over time. A bank’s decision can reflect current market rates, expected rate changes, and competition for deposits rather than a single public announcement.

    A bank’s need for deposits

    Banks use deposits as one source of funding for loans and other activities. If a bank wants more deposits, it may raise a savings rate or promote a limited-time offer. If it has enough deposits, it may lower its rate relative to competitors. Online banks sometimes change rates more visibly because rate is a major way they compete for customers.

    “The best account is not always the one with the highest number today; it is the one whose terms fit the job your money needs to do.”

    Promotional offers and balance tiers

    Some accounts pay a promotional APY for a defined period, only on new money, or only up to a balance threshold. Others offer a stated rate only after direct deposit, debit-card activity, or a minimum balance. The headline rate can therefore be less useful than the disclosure.

    A tiered account may pay one APY on the first portion of your balance and another on the rest. For example, an offer that pays a higher rate on the first $5,000 but a lower rate beyond that may produce a different effective return than an account paying one lower rate across your full balance.

    Operating costs and competitive strategy

    Rates also reflect practical business choices. Branch networks, customer service, technology spending, loan demand, and marketing budgets all affect what an institution is willing to pay for deposits. Two insured accounts can have different APYs and still be reasonable choices for different customers.

    How a rate change affects your actual dollars

    Interest is often accrued daily and paid monthly, although each account agreement controls. A rough annual estimate is your balance multiplied by the APY. The actual amount can differ because of daily compounding, deposits and withdrawals during the month, and rate changes during the period.

    Average balance APY example Approximate interest over one year What a 0.50 percentage-point drop changes
    $2,000 4.00% About $80 About $10 less over a year
    $10,000 4.00% About $400 About $50 less over a year
    $25,000 4.00% About $1,000 About $125 less over a year

    These are illustrations, not quoted rates or a forecast. Taxes can also reduce the amount you keep. Savings interest is generally taxable income in the United States, and your bank may report it on a tax form when required.

    “Rate differences matter most when the balance is large, the difference persists, and moving the money is simple.”

    A decision rule for staying or switching

    Do not react to every rate notification. First calculate the approximate difference in dollars, then compare it with the effort and any lost conveniences. This three-step rule can help.

    1. Measure the gap. Multiply your average balance by the difference between your current APY and a realistic alternative APY.
    2. Check the conditions. Verify whether the competing rate is promotional, tiered, capped, or dependent on activity.
    3. Price the friction. Consider transfer limits, settlement time, account minimums, linked checking, and whether the account is useful beyond its rate.

    Suppose you have $12,000 in savings and your rate falls by 0.40 percentage points. The rough annual difference is $48 before tax. That might be worth changing accounts if you already have a verified alternative and transfers are easy. It might not be worth disrupting an account that has reliable transfers and helps you maintain a clear emergency-fund system.

    When a high-yield savings account is the right tool

    A HYSA is usually most suitable when protecting principal and keeping access matter more than maximizing long-term growth. Common uses include:

    • An emergency fund for unexpected medical, repair, or job-loss expenses.
    • A short-term savings goal, such as a move, vehicle purchase, or wedding.
    • Cash needed within a few years that you do not want exposed to stock-market swings.
    • A separate bucket for annual bills, deductibles, or tax payments.

    It may be a weaker fit for money you will not need for many years and can tolerate investing with risk, or for a fixed-date goal where a certificate of deposit could provide a stated rate for a stated term. Neither choice is automatically better. The right decision depends on your timeline, liquidity needs, taxes, and tolerance for changing rates.

    HYSA versus a CD when rates are moving

    Definition: certificate of deposit. A CD is a deposit product with a stated term, often paired with an early-withdrawal penalty. In exchange for limiting access, you may receive a rate set for that term. A CD can reduce uncertainty about the rate, but it does not remove the need to plan for access to the money.

    If you need the cash at an unknown time, a savings account may be more practical even when a CD offers a higher stated rate. If you know you will not need part of the money until after a specific date, a CD may be worth comparing. Review the penalty, minimum deposit, renewal policy, and what happens when the term ends.

    What to check before opening an account

    Read the account disclosure, not just the headline

    Look for the APY, whether it is variable, balance tiers, monthly maintenance fees, minimum opening deposit, and any qualifications. Also ask whether the rate applies to the whole balance or only a portion. Providers can change rates, fees, and terms, so verify the current details directly with the provider before opening an account.

    Test access and transfer rules

    Emergency savings are useful only if you can reach them when needed. Review outgoing transfer limits, transfer timing, wire availability, ATM access if offered, and how you would receive funds during a weekend or holiday. A savings account at a separate institution can create a helpful spending barrier, but it can also add a transfer delay.

    Check deposit insurance and account ownership

    Confirm the institution is insured and understand the applicable coverage limits. Multiple accounts at the same institution may be combined for coverage purposes depending on ownership category. Joint accounts, trusts, and business accounts can have different rules. Ask the institution or consult official insurance resources if your balance is close to or above standard limits.

    Keep records when you move money

    Use linked accounts in your own name when possible, confirm routing and account numbers carefully, and retain confirmation emails until deposits are complete. Avoid moving every dollar at once if you need immediate cash. Leaving a reasonable buffer in your primary checking account can prevent an overdraft caused by timing.

    Frequently asked questions

    Can a bank lower my high-yield savings rate without my permission?

    Variable savings rates can generally change under the account agreement. Banks typically provide notices required by law or by their terms, but you should review account alerts and statements. A rate change affects future interest calculations, not ownership of the balance already in the account.

    How often do high-yield savings rates change?

    There is no universal schedule. An institution may change an APY several times in a year, rarely, or in response to competitive and market conditions. Checking your account’s rate periodically is more practical than assuming a fixed schedule.

    Should I chase the highest savings rate?

    Compare the dollar difference after considering the full account terms. A small APY advantage may not outweigh a temporary promotion, a balance cap, a fee, slower access, or repeated account opening. For a larger balance, a durable rate difference can be more important, but the alternative still needs to meet your safety and access needs.

    Does a lower APY mean my money is less safe?

    Not by itself. Rate and deposit insurance are separate questions. Verify that the institution is federally insured where applicable and that your deposits fit within coverage rules. The appropriate account also depends on fees, service, and access, not rate alone.

    The bottom line

    High-yield savings account rates change because they are variable prices set by individual institutions. Treat a rate notification as a prompt to review, not an automatic command to move your money. Compare the annual dollar effect, the account conditions, and your need for access before making a change.

    This article is educational information, not personalized financial advice. Rates, fees, terms, tax treatment, and deposit-insurance rules can change. Verify current terms with providers and consider a qualified financial or tax professional for advice tailored to your circumstances.

  • What Is a Mortgage Comparison Rate? How to Read APR, Fees, and Total Cost

    What Is a Mortgage Comparison Rate? How to Read APR, Fees, and Total Cost

    Short answer: A mortgage comparison rate is a single rate designed to show the approximate cost of a home loan after combining the advertised interest rate with certain fees and charges. In the United States, the closest standard disclosure is usually the annual percentage rate, or APR. Neither figure replaces a full loan estimate, but both can help you compare offers on a consistent basis.

    For example, a lender may advertise a 6.50% interest rate while showing a 6.74% APR because origination charges, discount points, or other finance charges increase the loan’s effective annual cost. The lower advertised rate is not automatically the cheaper loan. Compare the rate, APR or comparison rate, upfront cash, monthly payment, and how long you expect to keep the mortgage.

    This article is educational information, not personalized financial advice. Rates, fees, eligibility rules, and loan terms can change. Verify current terms and required disclosures with each lender before applying or making a decision.

    What is a mortgage comparison rate?

    A mortgage comparison rate expresses more of a loan’s cost than the note rate alone. The note rate is the percentage used to calculate scheduled interest. A comparison rate generally incorporates the note rate plus selected fees, expressed as an annualized percentage for a stated loan amount and term.

    The name varies by country. Australian lenders commonly publish a comparison rate beside the advertised home-loan rate. In the United States, lenders generally disclose APR under federal lending rules. In the United Kingdom, mortgage examples may emphasize the annual percentage rate of charge, or APRC. These measures have different formulas and required inclusions, so do not assume two countries’ figures are interchangeable.

    Definition: The comparison rate is a cost-of-credit estimate based on stated assumptions. It is a comparison aid, not necessarily the rate you will receive and not a guarantee of your total lifetime cost.

    Comparison rate vs. interest rate

    What Is a Mortgage Comparison Rate? How to Read APR, Fees, and Total Cost
    What Is a Mortgage Comparison Rate? How to Read APR, Fees, and Total Cost
    Figure What it tells you What it may leave out
    Interest or note rate The rate used to calculate scheduled loan interest Many upfront and ongoing charges
    APR An annualized cost that includes the note rate and certain finance charges Some third-party costs, late charges, and costs that depend on your actions
    Mortgage comparison rate A broader cost illustration under a stated loan scenario Costs outside the formula and differences between local disclosure rules
    Monthly payment What the scheduled payment may be under the quoted terms Total interest, fees, future rate changes, and escrow changes

    Quotable rule: The interest rate answers “what rate is used?” while the comparison rate asks “what does this borrowing package cost under the stated assumptions?”

    What costs can affect a comparison rate?

    The exact formula depends on the jurisdiction and product, but common inputs include:

    • Interest charges: The cost produced by the principal balance, interest rate, and repayment schedule.
    • Origination or application fees: Charges for processing and setting up the loan, when treated as finance charges under applicable rules.
    • Discount points: Upfront amounts paid to obtain a lower note rate. One point commonly equals 1% of the loan amount, but the pricing benefit varies.
    • Mortgage broker compensation: A broker fee may affect the disclosed cost when it is paid by the borrower and covered by the applicable calculation.
    • Some lender-required services: Certain charges connected to obtaining the loan can be included, while many settlement costs are excluded.

    Comparison measures often do not include every cost you will pay at closing. Property taxes, homeowners insurance, owner’s title insurance, moving costs, repair work, and optional services are normally separate from the borrowing-cost calculation. A lender’s loan estimate or equivalent disclosure is the place to inspect the full cash-to-close figure.

    Quotable rule: A comparison rate can expose expensive loan pricing, but it is not a substitute for reading the fee page and closing-cost estimate.

    Why a lower comparison rate may not settle the decision

    A comparison rate is calculated from assumptions. The assumed loan amount, term, repayment pattern, payment timing, and fee treatment all matter. The result can be less useful when your actual situation differs from the example.

    Loan term and holding period

    Suppose Loan A has a lower rate but requires several thousand dollars in points. Loan B has a higher rate and little upfront cost. If you keep the mortgage for decades, the lower-rate option may have time to recover its upfront cost. If you sell or refinance after three years, the savings may never catch up.

    A simple break-even estimate is:

    Break-even months = extra upfront cost divided by monthly payment savings.

    If points and lender fees cost $3,600 more and reduce the payment by $100, the rough break-even point is 36 months. This does not account for tax treatment, the changing loan balance, refinancing costs, or the time value of money. It is a screening calculation, not a prediction.

    Adjustable-rate loans

    For an adjustable-rate mortgage, an initial comparison figure may rely on a specified future-rate assumption. The actual payment can change when the introductory period ends. Review the index, margin, adjustment frequency, initial and periodic caps, lifetime cap, and worst-case payment shown in the disclosure.

    Different fee structures

    One lender may charge more upfront while another charges a higher rate. A single comparison number may not make the cash-flow difference obvious. Ask each lender for the same loan amount, term, property type, down payment, and lock period so the offers can be compared fairly.

    How to compare mortgage offers step by step

    1. Set the same assumptions

    Request quotes for the same purchase price, down payment, loan amount, term, occupancy, credit profile assumptions, and lock period. A quote for a 15-year mortgage cannot be compared directly with a 30-year quote just because its interest rate is lower.

    2. Put the note rate and comparison figure side by side

    Record the interest rate, APR or comparison rate, points, lender credits, estimated principal-and-interest payment, and cash needed at closing. A lender credit can reduce upfront cost but may come with a higher rate. The comparison should show both effects.

    3. Separate lender costs from ownership costs

    Create two totals. The first is the cost of borrowing: interest, points, origination charges, and relevant lender fees. The second is the cost of owning the property: taxes, insurance, association dues, maintenance, and utilities. This prevents a low borrowing figure from masking an unaffordable total housing payment.

    4. Test more than one time horizon

    Compare estimated costs if you keep the loan for three years, seven years, and the full scheduled term. The three-year view is useful for buyers who may move or refinance. The full-term view shows the long-run effect of the rate and repayment schedule, but it should not be treated as a promise that you will keep the loan that long.

    5. Check the features behind the number

    Look for prepayment penalties, balloon payments, interest-only periods, rate-adjustment rules, late fees, minimum payment requirements, and restrictions on extra principal payments. A slightly lower cost measure may not be worth a feature that does not fit your plans.

    Quotable rule: The best mortgage comparison is built from matching loan scenarios, not from collecting the lowest isolated percentage.

    Worked example: choosing between two fixed-rate offers

    Assume a borrower is comparing two 30-year fixed loans for $300,000. Lender A offers a 6.50% note rate, $6,000 in points and lender fees, and an estimated APR of 6.82%. Lender B offers a 6.75% note rate, $2,000 in lender fees, and an estimated APR of 6.91%. The figures are illustrative and not current market quotes.

    Lender A has the lower rate and lower APR, but it requires $4,000 more upfront. If the principal-and-interest payment is about $52 lower each month, the basic break-even estimate is about 77 months, or 6.4 years. A borrower expecting to sell in two years might prefer the lower upfront cost. A borrower expecting to keep the loan beyond the break-even period might place more weight on the lower ongoing payment, provided the household can comfortably pay the closing amount.

    The example does not include taxes, insurance, refinancing, investment returns, tax deductions, or changes in the borrower’s plans. Those items can change the result. The point is to compare the timing of costs, not to label one offer universally best.

    Common mistakes when reading a comparison rate

    • Comparing different terms: A 15-year rate and a 30-year rate have different payments and total interest.
    • Ignoring points: A lower rate can require a large upfront payment.
    • Assuming APR includes everything: Review the exclusions and the full closing-cost disclosure.
    • Using the advertised rate as a personal quote: Your rate may depend on credit, property, down payment, occupancy, loan type, and market conditions.
    • Forgetting rate-lock details: Ask how long the lock lasts and what happens if closing is delayed.
    • Focusing only on payment: A longer term can lower the monthly payment while increasing total interest.
    • Treating a variable-rate example as fixed: Read the adjustment schedule and payment caps.

    Questions to ask a lender

    • What is the note rate, APR, and total lender-charged cost for this exact scenario?
    • How much cash is required at closing, including points and prepaid items?
    • Which fees are included in the APR or comparison rate, and which are excluded?
    • Is the rate fixed for the full term, and what can cause the payment to change?
    • Are there lender credits, and what rate or conditions come with them?
    • Can I make extra principal payments without a penalty?
    • What will the estimated balance be after three, five, and seven years?

    Q&A

    Is a mortgage comparison rate the same as APR?

    They serve a similar purpose, but the terms are not always identical. APR is the standardized U.S. annualized cost disclosure. Comparison-rate formulas in other countries may include different fees and assumptions. Read the definition used with the quote.

    Should I choose the mortgage with the lowest comparison rate?

    Use the lowest figure as a starting point, then compare upfront cost, payment, loan features, and your expected holding period. The lowest comparison rate may not fit a borrower who needs to preserve cash or expects to move soon.

    Does a comparison rate include property taxes and insurance?

    Usually it focuses on borrowing costs rather than the full cost of owning the home. Request a complete payment estimate that separately shows principal, interest, taxes, insurance, association dues, and other applicable charges.

    Can a comparison rate change after I apply?

    Yes. Rates and fees can change before a rate is locked, and the final terms can depend on underwriting, the property, and the chosen product. Confirm the lock period and review the final disclosure before closing.

    The practical decision

    Use a mortgage comparison rate to screen out offers that look cheap only because they hide costs in fees or points. Then make a short worksheet for your own decision: note rate, APR or comparison rate, cash at closing, monthly principal and interest, estimated total payment, break-even period, and key loan restrictions.

    The right offer is the one whose cost and features fit your expected time in the home and your ability to pay upfront. Verify every figure with the lender because rates, fees, and terms can change between an initial quote and closing.

  • How to Dispute a Checking Account Charge: A Practical Step-by-Step Guide

    How to Dispute a Checking Account Charge: A Practical Step-by-Step Guide

    How to Dispute a Checking Account Charge: A Practical Step-by-Step Guide

    Quick take: If a checking account charge looks wrong, move fast. Save screenshots, note the date and amount, and contact your bank through the channel that matches the problem. A true bank error, a card charge, and an ACH debit are handled differently, so the fastest path is to identify the type of charge first.

    Educational note: This article is for general information only and is not personalized financial advice. Bank policies, timelines, fees, and dispute rights can change, so verify current terms with your bank or payment provider before taking action.

    Most checking account disputes do not come down to one dramatic move. They come down to process. The people who get the cleanest outcome usually do three things well: they act quickly, they document everything, and they use the right dispute channel for the transaction type.

    What a checking account charge dispute actually is

    A disputed checking account charge is a request for review after money leaves your account in a way you believe is wrong. That might mean a bank fee you do not think you owe, a debit card transaction you did not authorize, a duplicate ACH debit, or a merchant charge that does not match what you agreed to pay.

    Not every problem is a bank error. Sometimes the merchant billed incorrectly. Sometimes a subscription renewed when you thought it was canceled. Sometimes the charge is legitimate but still worth questioning because the amount is wrong.

    Quote-worthy point: “The first job is not to argue. The first job is to classify the charge correctly.”

    Start with the three most common charge types

    How to Dispute a Checking Account Charge: A Practical Step-by-Step Guide
    How to Dispute a Checking Account Charge: A Practical Step-by-Step Guide

    Before you call anyone, figure out which bucket the problem fits into.

    • Bank fee or account charge: Examples include overdraft fees, maintenance fees, ATM fees, or wire fees.
    • Debit card purchase: A merchant charge that hits your debit card through Visa, Mastercard, or another card network.
    • ACH or electronic debit: A pull from your checking account, often used for bills, subscriptions, loan payments, or transfers.

    That distinction matters because each one may follow a different complaint process. A bank fee usually goes to your bank’s customer service or disputes team. A debit card purchase may need a card network dispute. An ACH debit often has special rules for unauthorized or incorrect transfers.

    Comparison table: which path fits which problem?

    Problem type Who to contact first What to gather Common timeline issue
    Bank fee Your bank Account history, screenshots, fee schedule Fee waiver window may be short
    Debit card purchase Your bank or card issuer Receipt, merchant name, date, amount Provisional credit rules can take time
    ACH debit Your bank Authorization proof, account activity, merchant contact record Revocation and error deadlines matter

    What to do in the first 10 minutes

    Do these steps before the paper trail gets messy.

    1. Take a screenshot or download the transaction details.
    2. Write down the date, amount, merchant name, and why it looks wrong.
    3. Check whether the charge is pending or posted.
    4. Look for related emails, texts, or receipts.
    5. Decide whether this is a bank fee, card purchase, or ACH debit.

    Quote-worthy point: “Evidence gathered early is easier to trust later.”

    How to build a strong dispute file

    Good disputes are boringly organized. Keep a simple file with the basics: transaction date, amount, account last four digits, merchant name, phone number or support email, and a short timeline of what happened.

    Useful evidence may include:

    • Bank statements
    • Receipts
    • Cancellation confirmations
    • Chat transcripts or email replies
    • Photos if the charge is tied to a damaged or undelivered item

    If the charge is for a subscription you canceled, save the cancellation confirmation and the exact date you canceled. If the issue is a duplicate charge, show both entries and explain why one should be removed.

    How banks usually handle the review

    Many banks will start by asking a few basic questions: Was the charge authorized? Was it posted correctly? Have you already contacted the merchant? Is the amount temporary or final? They may also ask whether you are disputing fraud, an error, or a service problem.

    That is not stalling. It helps route the case. A fraud claim and a merchant service complaint can follow different rules and timelines. If you answer clearly, you reduce back-and-forth.

    Fraud versus error versus service dispute

    Fraud: You did not authorize the charge.

    Error: The amount, date, or duplicate status is wrong.

    Service dispute: You paid, but the merchant did not deliver as promised or charged for the wrong item.

    What to say when you call

    Keep it short and specific. A strong opening sounds like this: “I am disputing a checking account charge of $84.19 from Riverline Fitness on August 10. I canceled before the renewal date and have the confirmation email. I want to open a dispute and understand the next step.”

    That gives the bank the key facts without a long speech. It also creates a record that you identified the amount, merchant, and reason.

    Quote-worthy point: “The cleaner the first sentence, the faster the case can move.”

    When to contact the merchant first

    For many card purchases and subscription problems, contacting the merchant first can save time. If the merchant agrees to refund the charge, the issue may end there. This is especially useful when the charge is small, the proof is clear, or the mistake looks accidental.

    Still, do not wait too long if the bank’s dispute window is short. If the deadline is tight, contact both the merchant and your bank the same day and keep records of both conversations.

    Practical decision rules

    Use these rules to avoid the most common mistakes.

    • If the charge is a bank fee, ask the bank about a waiver or courtesy reversal first.
    • If the charge is a debit card purchase you did not make, report it immediately.
    • If the charge is a recurring bill you canceled, save the cancellation proof before filing.
    • If the amount is tiny but repeated, document the pattern. Small errors add up.
    • If the merchant has already promised a refund, ask for a written confirmation.

    The practical rule is simple: try the fastest legitimate fix first, but do not let the clock run out on your bank’s dispute period.

    What not to do

    There are a few habits that make disputes harder.

    • Do not delete receipts or messages.
    • Do not file two contradictory stories with different support teams.
    • Do not assume the merchant portal and bank portal share the same status.
    • Do not keep paying for a canceled subscription without checking the renewal terms.
    • Do not ignore small unauthorized charges. They can be a sign of a broader problem.

    Front-loaded facts to verify before you submit

    These details can determine whether your dispute is accepted quickly or gets bounced back for more information.

    • Was the charge pending or posted?
    • Is the issue fraud, error, or a merchant disagreement?
    • What is the exact amount and date?
    • Did you contact the merchant already?
    • Is there a deadline in your bank’s dispute policy?
    • Can you document the cancellation, return, or authorization issue?

    Real-world examples

    Example 1: A grocery debit card charge posts twice. The customer downloads both transactions, calls the bank, and asks for a duplicate-charge review.

    Example 2: A streaming service renews after cancellation. The customer sends the cancellation email to the merchant and also opens a bank dispute if no refund arrives quickly.

    Example 3: An ATM fee appears after a cash withdrawal. The customer checks whether the machine was in-network and whether the bank offers fee refunds for certain ATM charges.

    Questions people ask most

    Will I lose access to my money while the dispute is reviewed?

    It depends on the bank and the type of dispute. Some cases may include provisional credit, while others may not. Check the bank’s policy before you assume anything.

    How long should I wait before filing?

    Usually not long. For unauthorized or clearly wrong charges, speed helps. For merchant service issues, collect evidence first, but do not wait so long that you miss a deadline.

    Can I dispute a fee I agreed to?

    You can ask for a waiver or courtesy reversal, but a fee that is clearly disclosed may be harder to overturn. Banks are more likely to help when there is a one-time mistake, a first offense, or a documented exception.

    Should I close the account after a disputed charge?

    Only if there is a broader problem. Closing an account can create more work than it solves if the issue is isolated and fixable.

    The bottom line

    Disputing a checking account charge is mostly about matching the problem to the right process. Bank fee, debit card purchase, and ACH debit are not the same thing, and they should not be handled the same way. Start by identifying the charge, gather proof, contact the right party, and keep a timeline of every step.

    That approach does not guarantee the result you want, and it should not be treated as a promise of approval, refund, or reversal. What it does do is put your dispute on firmer ground. In consumer banking, that is usually the difference between a fast review and a confusing one.

  • How Much Are Checking Account Fees? Typical Costs, Waiver Rules, and Better Alternatives

    How Much Are Checking Account Fees? Typical Costs, Waiver Rules, and Better Alternatives

    Checking account fees often cost $5 to $35 per incident, depending on the bank, account type, and behavior that triggers the charge. The most common fees are monthly maintenance fees, overdraft fees, out-of-network ATM fees, paper statement fees, wire transfer fees, and account closing fees. A checking account can still be a useful everyday money tool, but the wrong account can quietly drain more than $100 a year from a household that is already trying to keep cash organized.

    This guide explains how much checking account fees are, how banks apply them, and how to compare accounts before opening one. The short version: focus on the monthly fee, overdraft policy, ATM access, minimum balance rule, direct deposit requirement, and transfer fees. A checking account with a headline fee of $0 can still be expensive if it charges often for the way you actually use money.

    Educational note: This article is general information, not personalized financial advice. Bank rates, fees, balance rules, and account terms can change. Verify current terms directly with each bank or credit union before opening, switching, or closing an account.

    What counts as a checking account fee?

    A checking account fee is any charge tied to keeping, using, or correcting an everyday deposit account. Some fees are predictable, such as a monthly maintenance fee. Others happen only after a trigger, such as overdrawing the account, using another bank’s ATM, ordering checks, receiving a wire, or closing a new account too soon.

    Definition: A monthly maintenance fee is a recurring charge for having the account open. Banks often waive it if you meet conditions such as a minimum balance, direct deposits, student status, senior status, or linked accounts.

    Definition: An overdraft fee is a charge that may apply when a transaction is paid even though the account does not have enough available money. Some banks have reduced or removed these fees, but policies vary widely.

    “The cheapest checking account is not always the one with the lowest monthly fee. It is the one whose rules match your normal paycheck, cash use, and balance pattern.”

    Typical checking account fees at a glance

    How Much Are Checking Account Fees? Typical Costs, Waiver Rules, and Better Alternatives
    How Much Are Checking Account Fees? Typical Costs, Waiver Rules, and Better Alternatives

    Exact amounts vary by provider, but these ranges give consumers a practical starting point when comparing account disclosures.

    Fee type Common range What triggers it How to reduce it
    Monthly maintenance fee $0 to $15 Keeping the account open Use direct deposit, meet balance rules, or choose a no-fee account
    Overdraft fee $0 to $35 per item Bank pays a transaction without enough available funds Opt out where possible, turn on alerts, link savings, or choose a no-overdraft-fee bank
    Non-sufficient funds fee $0 to $35 Bank returns a transaction unpaid Keep a buffer and track pending bills
    Out-of-network ATM fee $2 to $5 plus owner fee Using another bank’s ATM Use in-network ATMs or an account with reimbursements
    Paper statement fee $1 to $5 per month Receiving mailed statements Choose electronic statements
    Incoming wire fee $0 to $20 Receiving a domestic or international wire Use ACH when timing allows
    Account closing fee $0 to $50 Closing soon after opening Keep the account past the early closure period

    How much are checking account fees in a normal year?

    A fee-light customer may pay $0. A customer with one monthly maintenance fee of $12 could pay $144 a year before any ATM or overdraft charges. Someone who pays a $10 monthly fee, uses four out-of-network ATMs at $4 each, and has two overdraft charges at $30 each could spend $196 in one year.

    That is why a checking account should be compared by annual cost, not by one fee line. A $12 monthly fee sounds smaller than a $30 overdraft fee, but the monthly fee repeats twelve times. A single repeated fee can be the largest cost in the account.

    “When comparing checking accounts, turn every recurring rule into an annual dollar amount. That makes a small monthly charge look like the real bill it becomes.”

    The main fees to inspect before opening an account

    Monthly maintenance fees

    The monthly fee is the first number to check because it applies even when you do nothing wrong. Many traditional banks list checking accounts with monthly fees from about $5 to $15. Premium accounts can cost more, though they may include extra services or waivers tied to larger balances.

    Waiver rules matter more than the listed fee. A $12 account can be fine for someone who receives direct deposit every pay period and keeps a stable balance. The same account can be poor for a gig worker whose income arrives through several apps and does not meet the bank’s direct deposit definition.

    Overdraft and insufficient funds fees

    Overdraft rules can be confusing because banks may handle debit card purchases, checks, automatic bill payments, and ACH payments differently. Some institutions decline the transaction with no fee. Others pay it and charge an overdraft fee. Some have grace periods, small-dollar cushions, or transfer services from savings.

    The practical rule: if your balance sometimes runs close to zero, choose an account with clear low-cost overdraft protection, real-time alerts, and no surprise fee stacking. A higher ATM network or branch count is less valuable if the account’s overdraft policy does not fit your cash flow.

    ATM fees

    ATM costs can include two charges: your bank’s out-of-network fee and the ATM owner’s surcharge. A $3 bank fee plus a $3 terminal fee turns a $40 withdrawal into a $46 event. Frequent cash users should look for a large free ATM network, local branches, or monthly ATM fee rebates.

    Paper, wire, and service fees

    Small service fees are easy to ignore until they appear. Paper statements, cashier’s checks, replacement debit cards, stop payments, official checks, and wire transfers can all carry separate charges. These may not matter for a basic paycheck-and-bills household, but they matter if you regularly send wires, need printed statements for housing paperwork, or use cashier’s checks.

    A realistic fee comparison example

    Consider two checking accounts.

    • Account A: $12 monthly fee, waived with $1,500 minimum daily balance or qualifying direct deposit. $35 overdraft fee. Large ATM network.
    • Account B: $0 monthly fee, no overdraft fee, smaller ATM network, $2.50 out-of-network ATM fee.

    For a salaried worker with direct deposit, $2,000 in checking, and rare ATM use, Account A may cost $0 in a typical year and offer convenient branch access. For a student, freelancer, or worker with an uneven balance, Account B may be cheaper even with a few ATM fees. If Account A’s monthly fee applies for six months, that alone is $72. One overdraft charge pushes the cost above $100.

    “The best checking account is personal to your cash flow. A good account for a steady direct-deposit household can be a bad account for someone with irregular income.”

    Decision rules for choosing a lower-fee checking account

    Use these rules before opening or switching accounts:

    1. Start with the monthly fee. If you cannot reliably meet the waiver, treat the fee as guaranteed.
    2. Read the overdraft policy in plain terms. Know whether debit card purchases are declined, paid, or covered by a linked account.
    3. Map your ATM use. Count how many times you withdraw cash each month and where.
    4. Check balance rules. Minimum daily balance and average monthly balance are not the same test.
    5. Review direct deposit wording. Some banks require payroll or government benefits, not peer-to-peer app transfers.
    6. Look at account closure rules. A sign-up bonus may lose value if an early closure fee or bonus clawback applies.
    7. Compare credit unions and online banks. They may offer lower fees, though branch access and cash deposit options can differ.

    How to avoid checking account fees without overcomplicating your money

    The best fee strategy is simple: pick an account that fits your habits so you do not need constant maintenance. Set a low-balance alert, keep a small buffer if possible, use electronic statements, and route recurring bills through a calendar or budgeting app. If you use cash often, choose the bank around ATM access rather than hoping a smaller network will work later.

    For overdraft risk, consider opting out of debit card overdraft coverage if the bank allows it. That may cause some purchases to be declined rather than paid with a fee. Also compare linked savings transfers, but check whether transfer fees apply and whether repeated transfers could affect your savings plan.

    For monthly fees, do not assume direct deposit will qualify. Confirm the requirement, especially if you are self-employed, paid through platforms, retired, or receiving irregular deposits. A no-monthly-fee checking account may be simpler than trying to meet a waiver every month.

    When a fee may be worth paying

    A fee is not automatically bad. A $10 monthly fee could be reasonable if the account provides branch access, safe deposit discounts, free official checks, ATM rebates, faster service, or bundled features you use often. The mistake is paying a fee for features that look impressive but do not match your life.

    Ask one test question: “Would I pay this annual amount for these specific services if they were billed separately?” If the answer is no, a lower-fee account deserves a close look.

    Questions and answers

    How much are checking account fees per month?

    Monthly maintenance fees commonly range from $0 to about $15 for standard checking accounts. Premium accounts may cost more. Many banks waive the fee if you meet direct deposit, balance, student, senior, or relationship requirements.

    Can a free checking account still charge fees?

    Yes. “Free checking” usually means no monthly maintenance fee. The account may still charge for overdrafts, out-of-network ATMs, paper statements, wires, stop payments, checks, or account closure within a short period.

    Are overdraft fees avoidable?

    Often, yes. You can compare banks with no overdraft fees, turn on alerts, link another account, keep a cushion, or opt out of some overdraft coverage. Policies differ, so confirm how the bank treats debit purchases, checks, ACH payments, and recurring bills.

    Is it better to choose an online bank for lower checking fees?

    An online bank can be a good fit if you want low monthly fees and do not need frequent branch service or cash deposits. A local bank or credit union may be better if you need in-person help, cashier’s checks, or regular cash handling.

    What should I compare first?

    Compare the annual cost of the monthly fee, the overdraft policy, ATM access, minimum balance rules, direct deposit requirements, and any service fees you are likely to use. The best account is the one that stays low-cost under your normal behavior.

    Bottom line

    Checking account fees can be $0, or they can add up to more than $100 a year through monthly charges, ATM use, and overdraft events. The smartest comparison is not a single fee number. It is a realistic estimate based on your paycheck timing, balance pattern, cash needs, and bill schedule. Before opening an account, read the fee schedule, verify current terms with the provider, and choose the account that makes low-cost behavior easy.