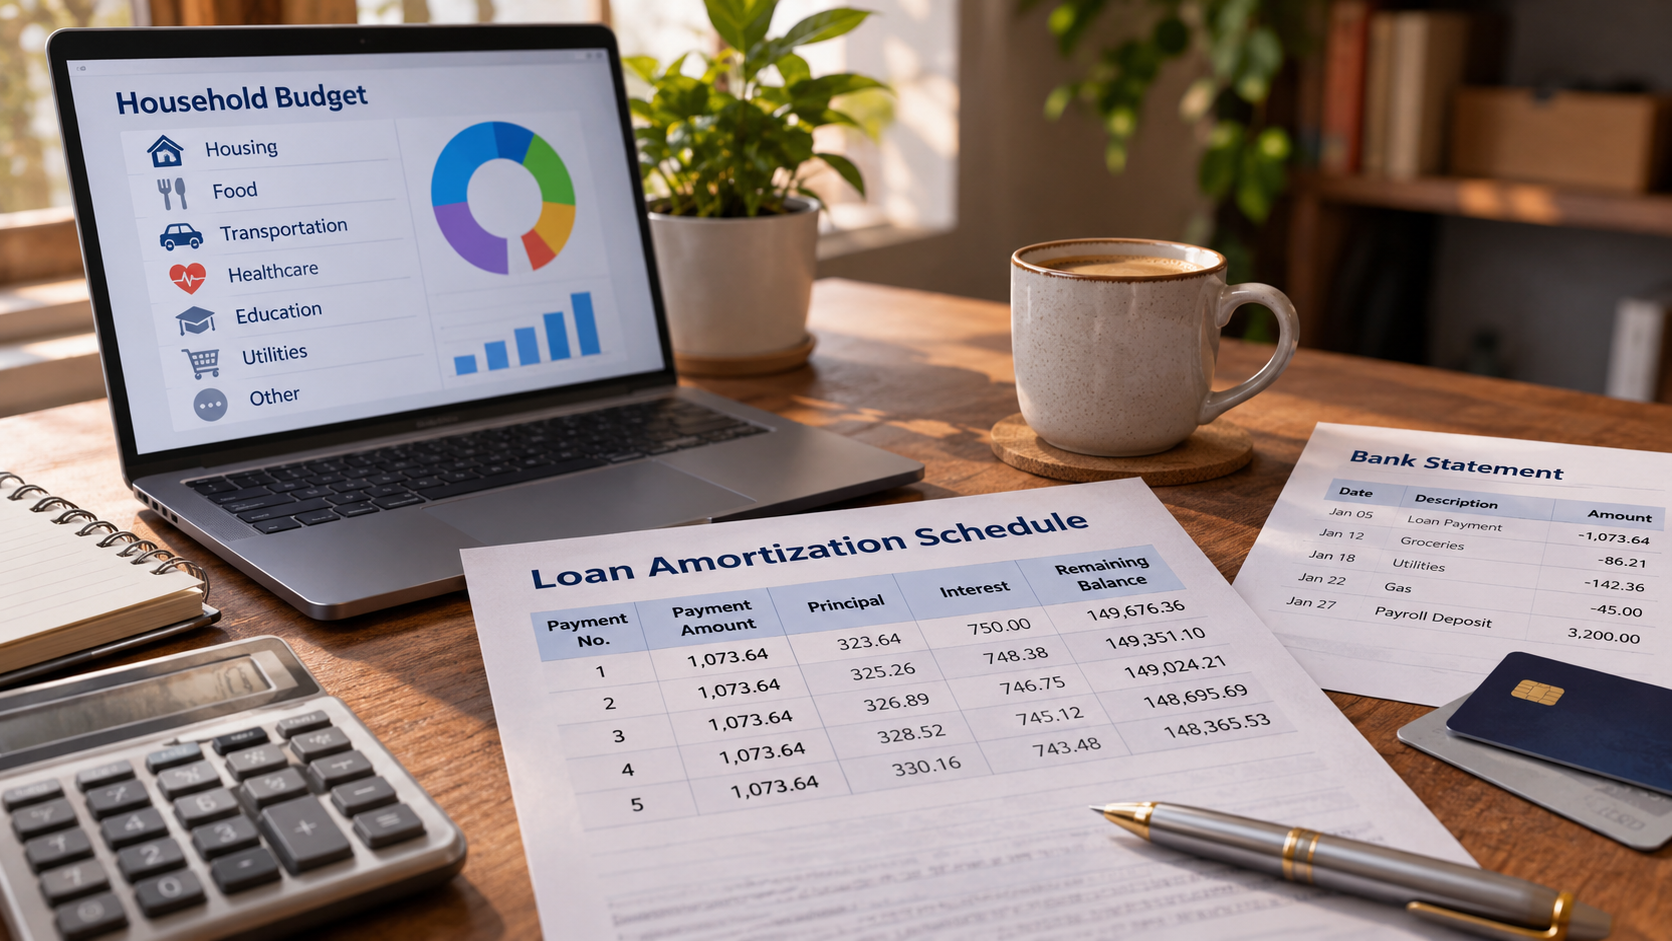
Knowing how to review a loan amortization schedule can make personal finance comparisons more accurate. A schedule shows how each payment is divided between principal and interest, how the balance changes over time, and how much the loan is expected to cost if you follow the original repayment plan.
This information is useful when comparing personal loans, debt-consolidation loans, auto loans, and mortgages. A loan with a lower monthly payment is not necessarily cheaper overall, and a lower advertised interest rate may not produce the lowest total cost after fees, loan length, or optional features are considered.
What Is a Loan Amortization Schedule?
A loan amortization schedule is a table that projects the payment activity of an installment loan. Typical columns include the payment number, scheduled payment, principal paid, interest paid, fees or extra charges where applicable, remaining balance, and sometimes the loan’s annual percentage rate or effective cost.
For a fully amortizing fixed-rate loan, the scheduled payment is usually the same each period, but the allocation changes. Early payments generally contain more interest because interest is calculated using the larger opening balance. As the balance declines, the interest portion typically falls and the principal portion rises. By the final scheduled payment, the balance should reach zero or a small rounding adjustment.
Amortization schedules are different from statements for revolving credit, such as most credit cards. Credit cards usually have variable balances, changing interest charges, and minimum-payment formulas rather than a fixed payoff table. They are also different from an interest-only loan, balloon loan, or adjustable-rate mortgage, where the balance may not decline in the same way throughout the term.
Why Review the Schedule Before Accepting a Loan?
The schedule translates loan marketing into a repayment timeline. It can help you answer practical questions:
- How much will be paid in total if every scheduled payment is made?
- How quickly does the balance decline?
- How much interest is paid during the first year compared with later years?
- What happens if an extra payment is applied to principal?
- Will a longer term make the payment easier but increase the total cost?
- Does the schedule match the lender’s offer and your understanding of the loan?
Reviewing the schedule also creates a common basis for comparing loans. For example, you can compare two personal loans using the same amount borrowed and a similar payoff date instead of focusing only on the monthly payment.
How to Review a Loan Amortization Schedule Step by Step
1. Confirm the basic loan assumptions
Start by checking the amount financed, interest rate, annual percentage rate, term, payment frequency, first payment date, and maturity date. Confirm whether the schedule assumes monthly, biweekly, or another payment frequency. A payment frequency can affect both timing and total interest.
Check whether the amount shown is the amount you receive or the amount financed after fees. An origination fee may be deducted from the money sent to you while interest is still calculated on the full amount financed. For a mortgage or auto loan, the financed amount may also include points, taxes, insurance, warranties, or other products.
2. Find the scheduled payment
Locate the regular payment amount and determine whether it includes anything beyond principal and interest. Mortgage payments often include escrow for property taxes and homeowners insurance, while an auto loan payment normally does not include car insurance. A lender’s total payment quote may therefore differ from the payment shown in the amortization table.
Ask whether the payment is fixed for the entire term. A fixed-rate loan generally has a stable principal-and-interest payment, while an adjustable-rate mortgage or variable-rate loan may be based on assumptions that change later. If the loan has a balloon payment, deferred interest, or an interest-only period, the schedule may not represent a simple fully amortizing loan.
3. Read the interest and principal columns together
For each row, compare the interest amount with the principal amount. The interest amount is usually based on the outstanding balance and the applicable periodic rate. The principal amount is the portion that reduces the balance. The scheduled payment should generally equal the principal and interest components, plus any listed charges.
A high interest share at the start of a long loan is not automatically an error. It reflects the fact that interest is charged while the balance is largest. However, an unexpectedly high amount may indicate that you are looking at a different rate, term, payment frequency, or financed amount than you intended.
4. Track the remaining balance
Review the balance after several milestones, such as the first payment, the end of the first year, the halfway point, and the final scheduled payment. This shows how quickly the debt is declining. On a long mortgage, the balance can decline slowly at first even when payments are made on time.
Compare the projected balance with your goal. If you plan to sell a home, refinance, trade in a vehicle, or consolidate debt later, the remaining balance helps estimate how much equity or payoff funding may be available. The actual payoff amount can differ from the schedule because of daily interest, fees, payment timing, or other contract terms.
5. Calculate the scheduled total cost
Multiply the scheduled payment by the number of payments, then add relevant upfront and ongoing charges. Subtract the amount actually received if you are measuring the cost of obtaining usable funds. This gives you a clearer comparison than the payment alone.
Do not confuse the interest total shown in a schedule with the loan’s complete cost. The schedule may exclude origination charges, application fees, late fees, prepaid interest, mortgage points, insurance, taxes, or optional products. The annual percentage rate is designed to reflect certain interest and credit costs, but its treatment depends on the product and the assumptions used.
6. Check the final row and rounding
The last row should normally show a zero balance, subject to rounding. If the final payment is much larger or smaller than the regular payment, investigate whether the loan has a balloon payment, deferred charges, an irregular first payment, or a schedule error.
Small differences can result from rounding each payment to cents. A lender’s payoff quote is the authoritative figure for closing an account, not a home-made spreadsheet estimate.
7. Test an extra-payment scenario
If you may pay more than required, ask how additional money is applied. A payment can be directed to accrued interest, fees, or principal. To reduce interest, extra funds generally need to be applied to principal after required amounts are satisfied, but your contract and lender’s procedures control.
Use a calculator or spreadsheet to model an extra monthly amount, an annual lump sum, or a one-time payment. Compare the new payoff date and interest total with the original schedule. Also check for a prepayment penalty, minimum extra-payment amount, or requirement to request a principal-only application.
Key Formulas and a Simple Example
For a standard fixed-rate loan, periodic interest can be approximated as:
Periodic interest = opening balance × periodic interest rate
The principal portion is generally:
Principal paid = scheduled principal-and-interest payment − periodic interest
Suppose a borrower has a fixed-rate installment loan with a regular payment of $400. In one month, $120 is allocated to interest and $280 to principal. The balance therefore falls by $280, assuming there are no additional fees or adjustments. In a later month, the payment might still be $400, but the interest portion could be lower and the principal portion higher because the balance has declined.
This example explains the direction of the changes but does not estimate the cost of any particular loan. Use the lender’s disclosed terms or a reputable calculator for a real comparison.
How to Compare Two Amortization Schedules
When comparing loans, hold as many assumptions constant as possible. Compare the same amount borrowed, similar repayment terms, and the same payment frequency. Then examine:
- APR: This can provide a broader cost comparison than the interest rate alone, subject to the disclosures and assumptions for the product.
- Total scheduled payments: This shows the amount paid under the original schedule, before considering possible changes.
- Fees: Include origination fees, points, broker charges, closing costs, and required add-on products where relevant.
- Balance reduction: A loan with a lower payment may leave a higher balance at a particular date.
- Flexibility: Review prepayment rules, rate changes, payment holidays, and refinancing conditions.
- Risk: Consider whether a variable rate, balloon payment, secured collateral, or late-payment consequences fit your finances.
A longer term often lowers the required monthly payment but may increase total interest because the balance remains outstanding for more periods. A shorter term commonly has a higher required payment but may reduce total interest. Neither option is universally best; the appropriate choice depends on cash flow, emergency savings, income stability, and other obligations.
Pros and Cons of Using an Amortization Schedule
Advantages
- It makes the principal and interest allocation visible.
- It helps compare total repayment costs instead of monthly payments alone.
- It supports planning for refinancing, selling, or paying off a debt.
- It can reveal whether an extra-payment strategy might shorten the term.
- It provides a way to check whether a lender’s explanation matches the contract.
Limitations
- A schedule is a projection and may not include every fee or future adjustment.
- Variable rates can make later rows uncertain.
- Actual payoff figures may include accrued daily interest and transaction charges.
- Escrow, taxes, insurance, and maintenance are often outside the principal-and-interest schedule.
- Prepayment modeling is unreliable if the lender applies extra money differently than expected.
- Rounding and payment-date differences can produce small discrepancies.
Connections to Other Personal Finance Comparisons
Loan analysis works best as part of a broader financial review. If you are considering debt consolidation, compare the new loan’s total cost with the existing debts and avoid treating a lower payment as proof of savings. A consolidation loan can extend repayment and may put secured assets at risk if it is backed by collateral.
Reviewing your checking account fees and maintaining an adequate emergency reserve can help prevent missed loan payments. High-yield savings accounts may offer a place for short-term reserves, but compare the account’s rate, access rules, fees, and variable-rate terms rather than assuming the highest advertised yield will remain available.
Credit cards and rewards should be evaluated separately from installment loans. Rewards do not offset interest if a balance is carried at a high rate. Credit score improvement may make refinancing more affordable, but applying for credit solely to chase a small rate change can have costs and should be assessed carefully.
For mortgages, compare rates, APR, points, closing costs, escrow assumptions, and the amortization schedule. For car ownership, evaluate the loan alongside car insurance, maintenance, and depreciation. Similar comparison principles apply to home insurance, retirement accounts and IRAs, and budgeting calculators: consider total cost, restrictions, risk, and how the product fits the full plan.
Reliable Sources and Comparison Methodology
This guide uses a general comparison methodology: identify the amount financed, rate structure, term, payment frequency, fees, total scheduled payments, projected balance, and risks; then compare products using consistent assumptions. Calculations should be checked against the written loan estimate, promissory note, account agreement, or closing disclosure.
The Consumer Financial Protection Bureau’s Ask CFPB provides consumer guidance on mortgages, credit, loans, and repayment issues. The Federal Trade Commission’s Credit, Loans, and Debt resources discuss borrowing and debt-related consumer concerns. These sources are useful starting points, but your loan documents and lender payoff statement control the terms of your specific account.
Concise Q&A
Does an amortization schedule show the exact payoff amount?
Not always. It usually shows projected scheduled payments. Request a current payoff quote to account for accrued interest, fees, payment timing, and lender-specific adjustments.
Why does the interest portion fall over time?
Interest is generally calculated from the outstanding principal balance. As principal is paid down, the interest calculated for later periods usually declines.
Is a lower monthly payment always better?
No. A lower payment may result from a longer term, a higher total interest cost, a variable rate, or a balloon balance. Compare total cost and remaining balance as well as affordability.
Should extra payments be made automatically?
Only after checking your emergency savings, higher-cost debt, contract terms, and lender procedures. Confirm that extra money is applied to principal and that no prepayment penalty applies.
Final Checklist
- Confirm the amount financed, rate, term, and payment frequency.
- Separate principal and interest from taxes, insurance, and other charges.
- Check the opening balance, milestone balances, and final balance.
- Compare total scheduled payments and all known fees.
- Review rate changes, balloon payments, late fees, and prepayment rules.
- Request clarification when the schedule does not match the contract.
- Use a current payoff quote before refinancing or paying off the loan.
Informational disclaimer: This article is for general educational purposes and is not financial, legal, tax, or lending advice. Loan terms vary by lender and borrower. Before signing, changing, or paying off a loan, review the official documents and consider consulting a qualified financial professional.
Leave a Reply